 Client Login
What a Fiduciary Really Means for Your Financial Advice
Today, you can buy a stock from your phone in seconds.
No broker. No phone call. No paper certificate. In many cases, no trading commission.
That sounds normal now. For most of Wall Street’s history, it would have been unthinkable.
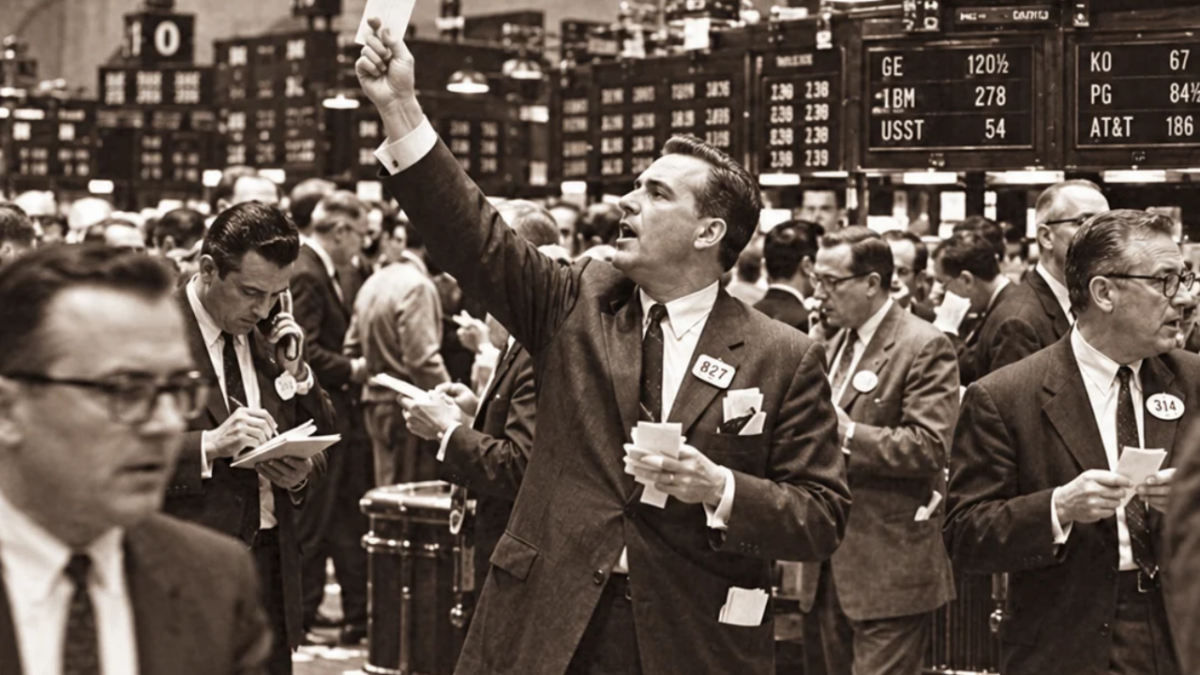
There was a time when buying a stock required calling a stockbroker, who contacted someone on a trading floor to execute the transaction. The broker controlled access to the market. That access was valuable, and Wall Street built an enormous industry around selling it.
Then technology made access nearly free.
The stockbroker should have disappeared with it.
Instead, something more interesting happened.
The title changed.
Stockbrokers became financial consultants. Financial consultants became financial advisors. Today, millions of investors assume the person sitting across from them is there primarily to provide advice.
But the history of the financial industry created an important distinction that still exists today: financial advisor vs. fiduciary.
Understanding that difference may tell you more about your advisor than the title printed on a business card ever will.
>> Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video. <<
It Started Under a Tree
The story goes back to May 17, 1792. Twenty-four stockbrokers gathered under a buttonwood tree near Wall Street and signed what became known as the Buttonwood Agreement.
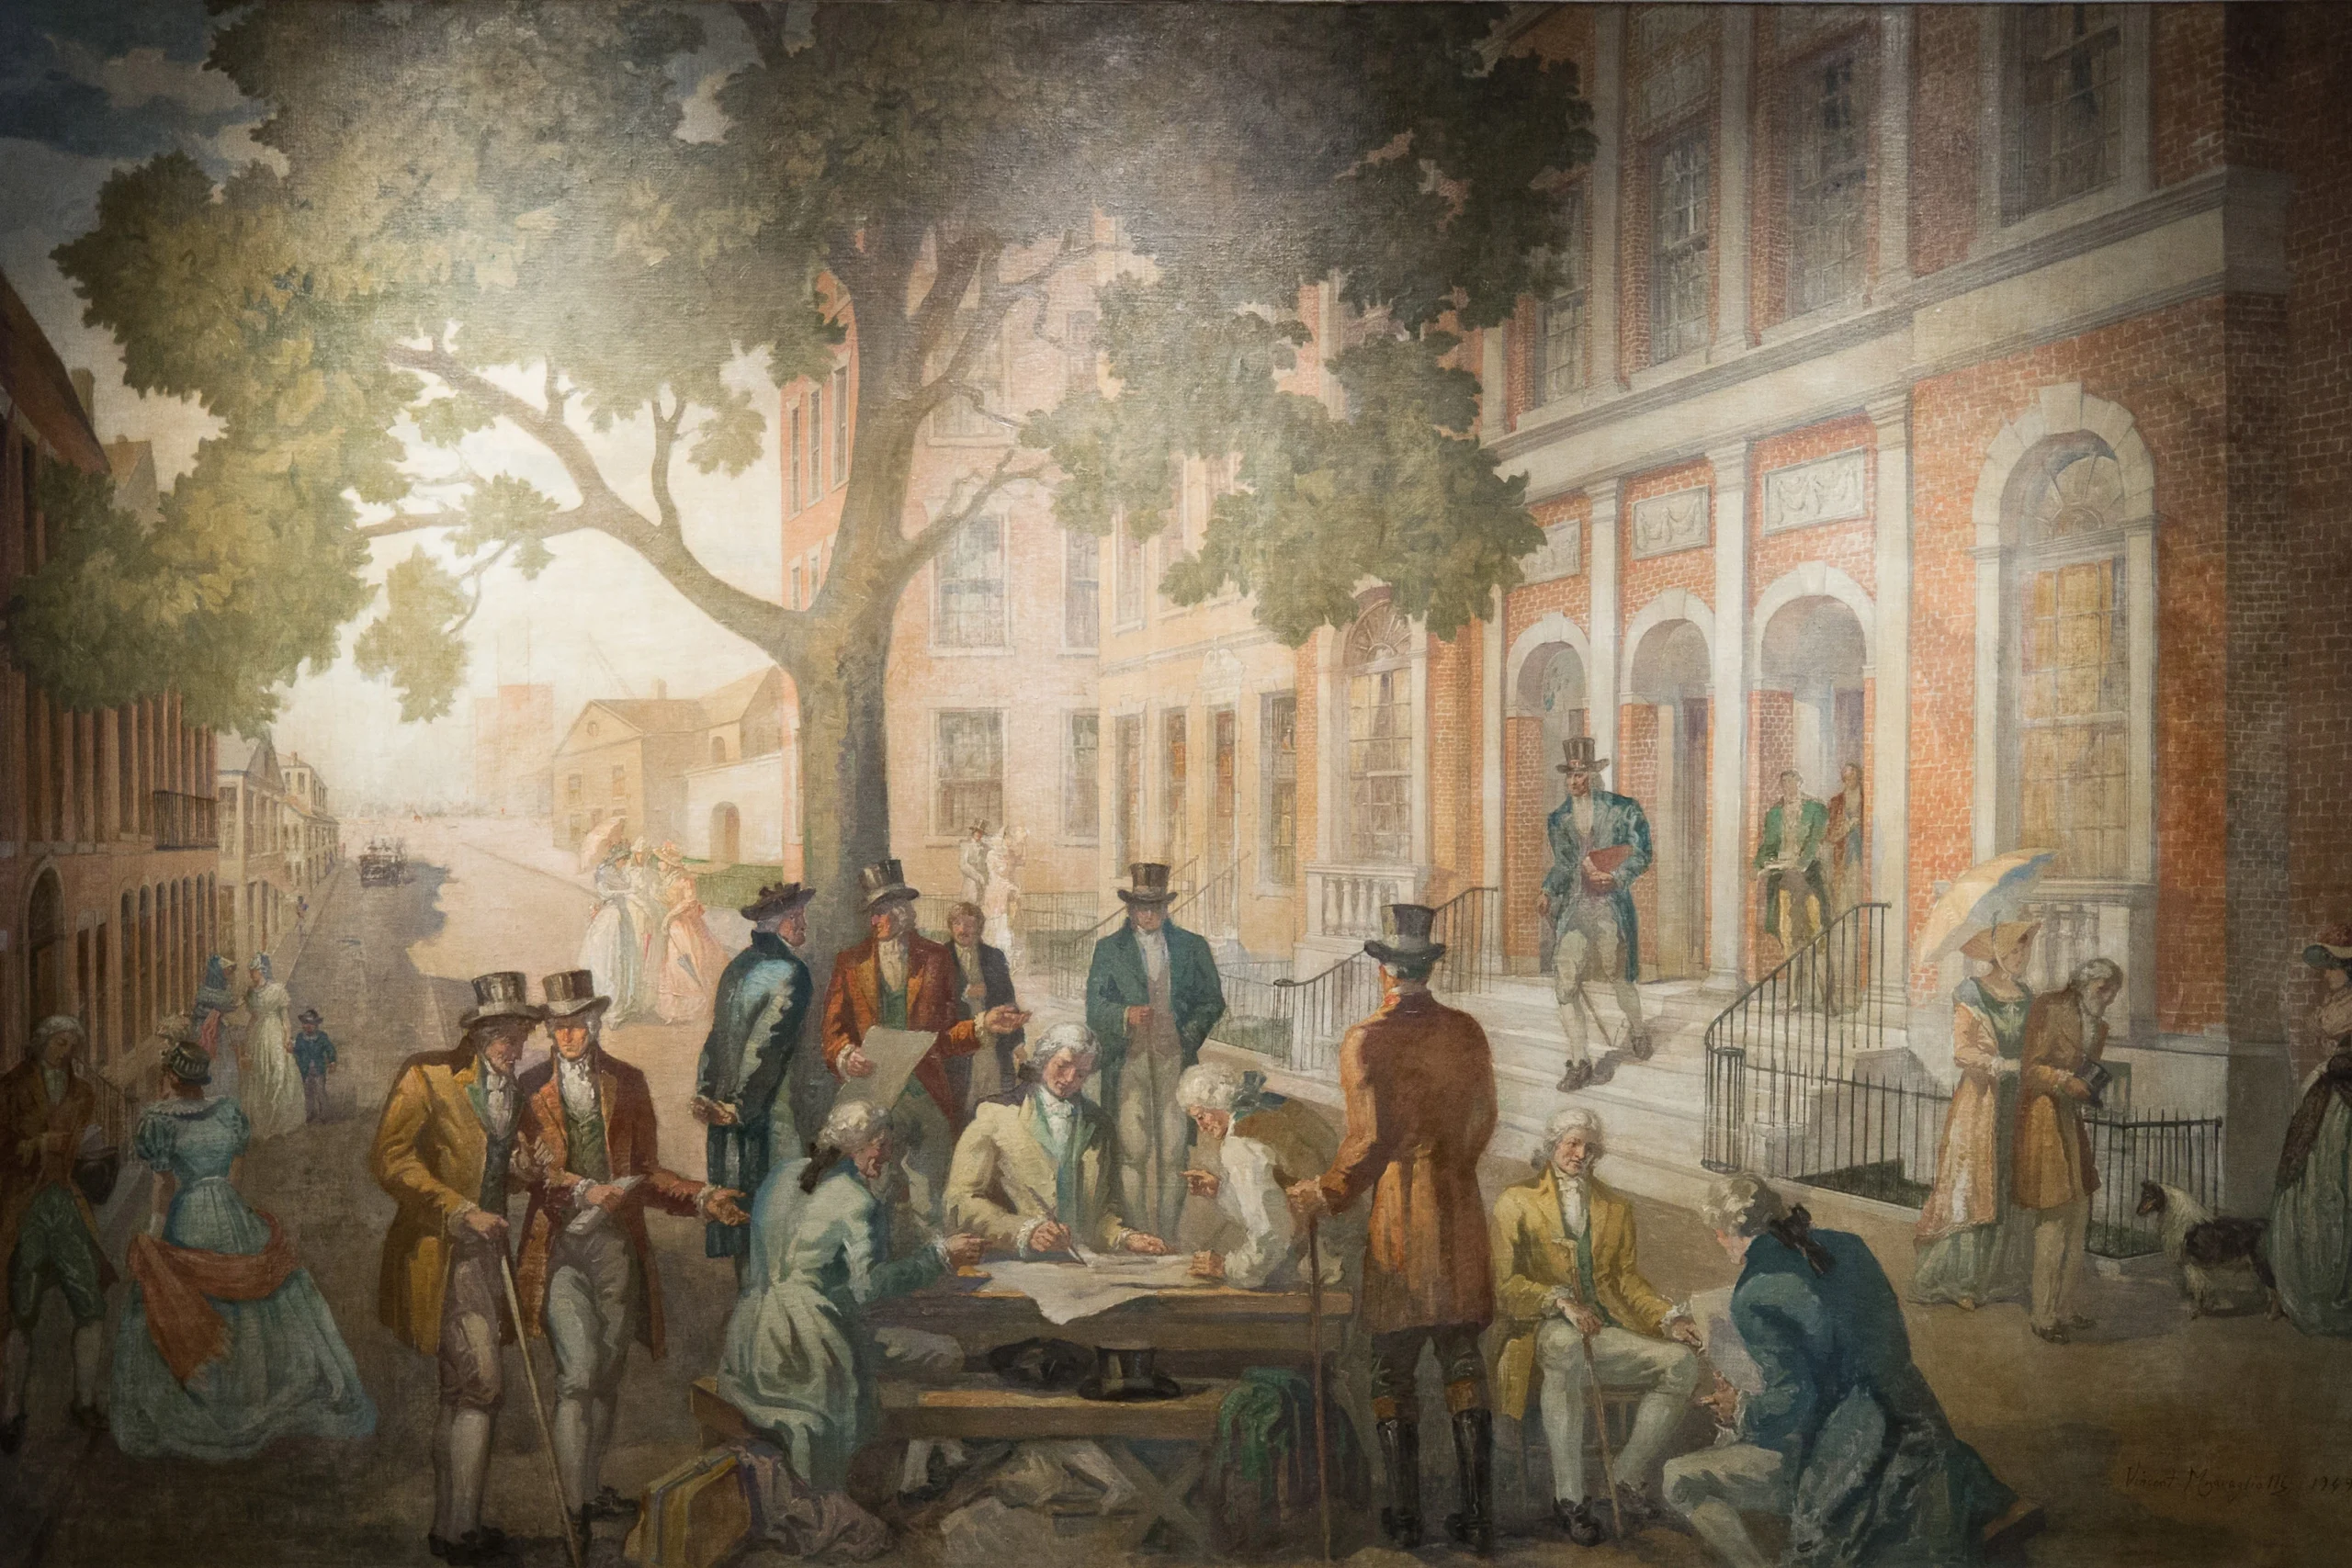
It contained two basic promises. The brokers agreed to charge a minimum commission, and they agreed to give preference to one another when conducting business.
That agreement helped lay the foundation for what eventually became the New York Stock Exchange.
More importantly, it established the basic economics of the brokerage business.
Brokers got paid when transactions happened. No transaction meant no commission.
For generations, that model made sense because investors couldn’t easily access financial markets without a broker.
Then everything started to change.
When Advice Became a Different Business
The stock market crash of 1929 ushered in a new era of financial regulation.
Congress passed the Securities Act of 1933 and the Securities Exchange Act of 1934. Then, in 1940, lawmakers passed the Investment Advisers Act.
That law helped establish a distinction that still matters today.
- A broker facilitates transactions.
- An investment adviser provides advice.
Those roles can come with different responsibilities to the client.
The concept of a fiduciary sits at the center of that distinction.
A fiduciary has a duty to put the client’s interests ahead of their own. That sounds like an obvious requirement for anyone giving financial advice, but the financial industry did not develop around a single standard.
Instead, two models grew alongside each other.
- One focused on selling financial products and completing transactions.
- The other focused on providing ongoing advice under a fiduciary standard.
From the outside, those professionals could look remarkably similar.
- Same office.
- Same suit.
- Same industry.
- Very different obligations.
Wall Street Saw the Conflict Early
Even some of Wall Street’s biggest names recognized the tension between advice and commissions.
Charles Merrill, one of the founders of Merrill Lynch, famously put brokers on salary rather than paying them based entirely on transactions.
The idea was simple.
If someone’s compensation increases every time a client trades, compensation can influence the advice that person gives.
Removing the transaction incentive could reduce that conflict. The model didn’t become the industry’s permanent standard.
Commission-based brokerage remained a powerful part of Wall Street for decades.
Then the economics underneath it began to collapse.
The Product Wall Street Sold Became Cheaper
For much of Wall Street’s history, brokers weren’t simply giving investors ideas.
They provided access.
By the late 20th century, technology started tearing down that barrier.
- Stock quotes went electronic.
- Index funds made broad market investing accessible.
- Personal computers brought trading into homes.
- Online brokerage accounts followed.
Then came one of the biggest blows to the traditional brokerage model.
In October 2019, Charles Schwab eliminated commissions on online stock and ETF trades. Major competitors quickly followed.
An activity that once supported an entire industry suddenly cost investors essentially nothing.
Think about what that meant.
For generations, Wall Street charged investors to execute trades.
Now investors could do it themselves from their phones.
When your core product becomes free, you need a new reason for clients to pay you.
That reason became advice.
The Stockbroker Didn’t Disappear. The Title Changed.
The language gradually shifted.
Stockbroker became financial consultant.
Financial consultant became financial advisor.
The new title sounded different because the service had changed. Investors increasingly wanted planning, guidance, tax strategy, retirement income advice, and help making decisions.
But the old brokerage model didn’t simply vanish.
Instead, the lines between brokerage and advice became harder for consumers to see.
That’s where the financial advisor vs. fiduciary conversation gets complicated.
Many financial professionals today hold more than one type of registration.
They may operate as an investment adviser in one situation and as a broker in another.
The industry calls this dual registration.
That means someone can provide fiduciary advice in certain parts of a relationship while also holding a brokerage registration that operates under a different regulatory framework, and get paid differently too.
The person sitting across from you may still carry the title “financial advisor” in both situations. That’s why the title alone tells you very little.
What Does Fiduciary Actually Mean?
A fiduciary financial advisor has a responsibility to put your interests ahead of their own when acting in a fiduciary capacity.
That distinction matters because financial recommendations can affect more than investment performance.
Consider the decisions investors make as they approach retirement:
- Which accounts should you withdraw from first?
- When should you claim Social Security?
- Should you convert traditional retirement assets to Roth?
- How should investment decisions coordinate with taxes?
- Does an insurance product solve an actual planning need?
- How should your estate plan fit with everything else?
These decisions rarely exist in isolation.
A true fiduciary relationship should begin with your financial life, not with a product someone wants to sell.
Why “Are You a Fiduciary?” May Not Be Enough
Here’s where things get tricky.
Ask a financial professional, “Are you a fiduciary?” and many can truthfully answer yes.
That doesn’t necessarily tell you whether they act as a fiduciary 100% of the time.
A dually registered professional may operate under a fiduciary standard in some circumstances while also maintaining a brokerage registration.
So the better question is more specific:
“Are you a fiduciary to me 100% of the time, in writing, without another registration that allows you to operate under a different standard?”
The answer should be easy to understand.
You shouldn’t need a law degree to figure out the relationship you’re entering.
Financial Advisor vs. Fiduciary: How to Check for Yourself
You don’t have to rely entirely on what an advisor tells you.
Financial professionals and advisory firms make regulatory disclosures available to the public.
Two documents can be particularly helpful.
Form ADV
Registered investment advisers file Form ADV.
It includes information about the firm’s business, services, fees, conflicts of interest, disciplinary history, and other important details.
Form CRS
Financial advisors and brokers may also provide Form CRS, short for Client Relationship Summary.
This document helps explain how the firm operates, what services it provides, how it gets paid, and potential conflicts.
Before hiring someone, read these documents. Look at how they receive compensation.
Check whether the person maintains a brokerage registration.
Then ask questions about anything you don’t understand.
Transparency shouldn’t require detective work.
Do You Even Need a Financial Advisor?
Not everyone does.
If you can build a diversified portfolio, stay invested through difficult markets, avoid chasing performance, coordinate your tax strategy, manage retirement withdrawals, and make major financial decisions without emotional interference, managing your money yourself may make sense.
You may also save a meaningful amount in advisory fees.
For everyone else, the question becomes whether professional advice delivers enough value to justify its cost.
A typical advisory fee around 1% can add up over time.
That means an advisor needs to provide value beyond simply choosing investments.
Good financial advice may include:
- Tax planning
- Retirement income strategy
- Investment management
- Behavioral coaching
- Social Security planning
- Risk management
- Estate planning coordination
- Withdrawal strategy
- Helping you make decisions when markets get difficult
An advisor shouldn’t exist simply because investing feels complicated. The relationship should make your overall financial life better.
Why Fiduciary Advice Matters More Today
Ironically, investing has never been easier.
You can build a diversified portfolio for very little money, and use AI to help run numbers. Financial information is everywhere. Trading costs have fallen dramatically.
The harder part now is making all the pieces work together.
- Investments affect taxes.
- Taxes affect retirement income.
- Retirement income affects Medicare premiums.
- Estate decisions affect heirs.
- Emotions affect nearly everything.
Modern financial advice should help coordinate those decisions. That’s also why understanding whether your advisor acts as a fiduciary matters.
You’re no longer paying someone simply to get you into the market.
You’re paying for judgment.
And when you’re paying someone for judgment, you should know whose interests come first.
The Stockbroker Evolved. Your Questions Should Too.
The financial industry has changed dramatically since 24 brokers met under a tree in 1792.
Paper certificates disappeared.
Trading floors became less important.
Commissions fell.
Technology gave individual investors access Wall Street once controlled.
Yet one question has survived every version of the industry:
Who does the person giving you financial advice ultimately work for?
The title on the business card won’t answer it.
“Financial advisor” can describe professionals working under very different business models.
Understanding the difference between a financial advisor and a fiduciary helps you look beyond the title and understand the relationship you’re actually entering.
Before you hand someone responsibility for decades of savings, ask how they’re registered, how they’re compensated, where conflicts could exist, and whether they will act as your fiduciary at all times.
You spent a lifetime building your wealth.
The advice you receive about it should put you first.
A Different Approach to Financial Advice
At Bonfire Financial, we believe financial advice should start with your complete financial life, not a product.
We operate as a fiduciary because we believe your interests should come first throughout the relationship.
Through the Bonfire Method, we bring investments, taxes, retirement income, insurance, and estate planning together into one coordinated strategy so you can see how each decision affects the rest. If you’re approaching retirement and want to understand whether all the pieces of your financial life are working together, learn more about the Bonfire Method.