Financial Advisor vs. Fiduciary: Why Wall Street Rebranded the Stockbroker

What a Fiduciary Really Means for Your Financial Advice

Today, you can buy a stock from your phone in seconds.

No broker. No phone call. No paper certificate. In many cases, no trading commission.

That sounds normal now. For most of Wall Street’s history, it would have been unthinkable.

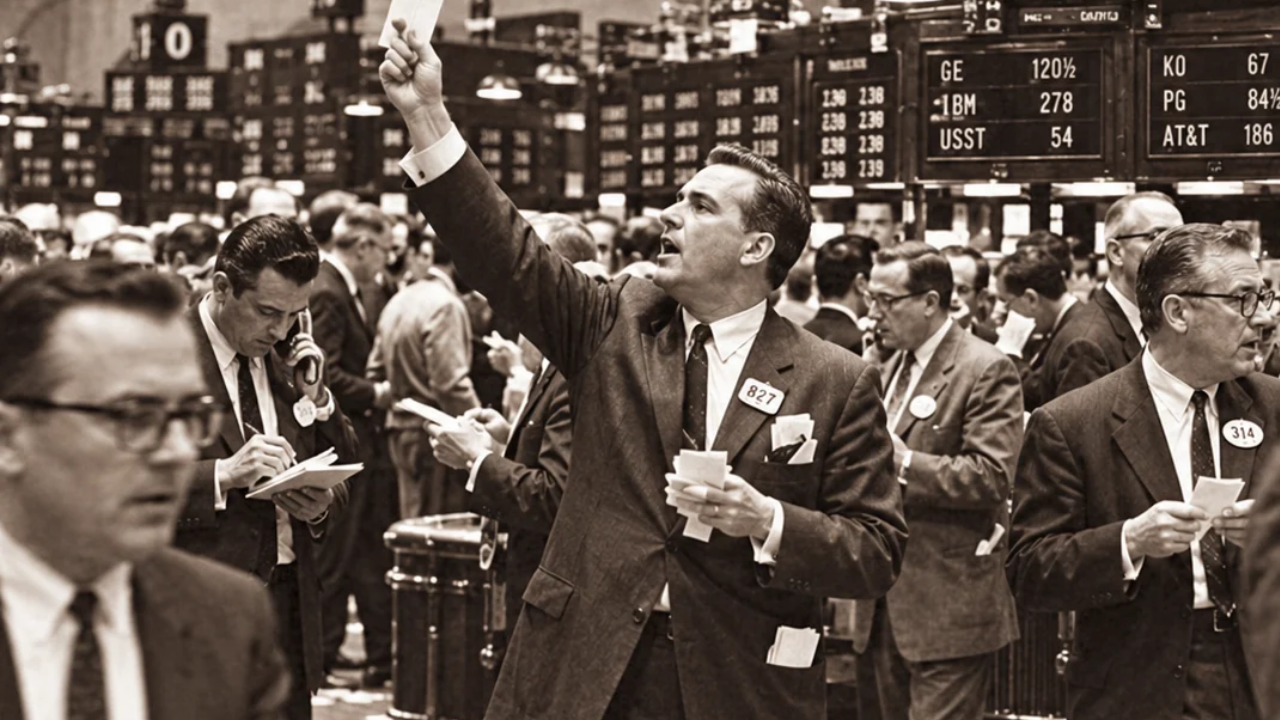
There was a time when buying a stock required calling a stockbroker, who contacted someone on a trading floor to execute the transaction. The broker controlled access to the market. That access was valuable, and Wall Street built an enormous industry around selling it.

Then technology made access nearly free.

The stockbroker should have disappeared with it.

Instead, something more interesting happened.

The title changed.

Stockbrokers became financial consultants. Financial consultants became financial advisors. Today, millions of investors assume the person sitting across from them is there primarily to provide advice.

But the history of the financial industry created an important distinction that still exists today: financial advisor vs. fiduciary.

Understanding that difference may tell you more about your advisor than the title printed on a business card ever will.

>> Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video. <<

It Started Under a Tree

The story goes back to May 17, 1792. Twenty-four stockbrokers gathered under a buttonwood tree near Wall Street and signed what became known as the Buttonwood Agreement.
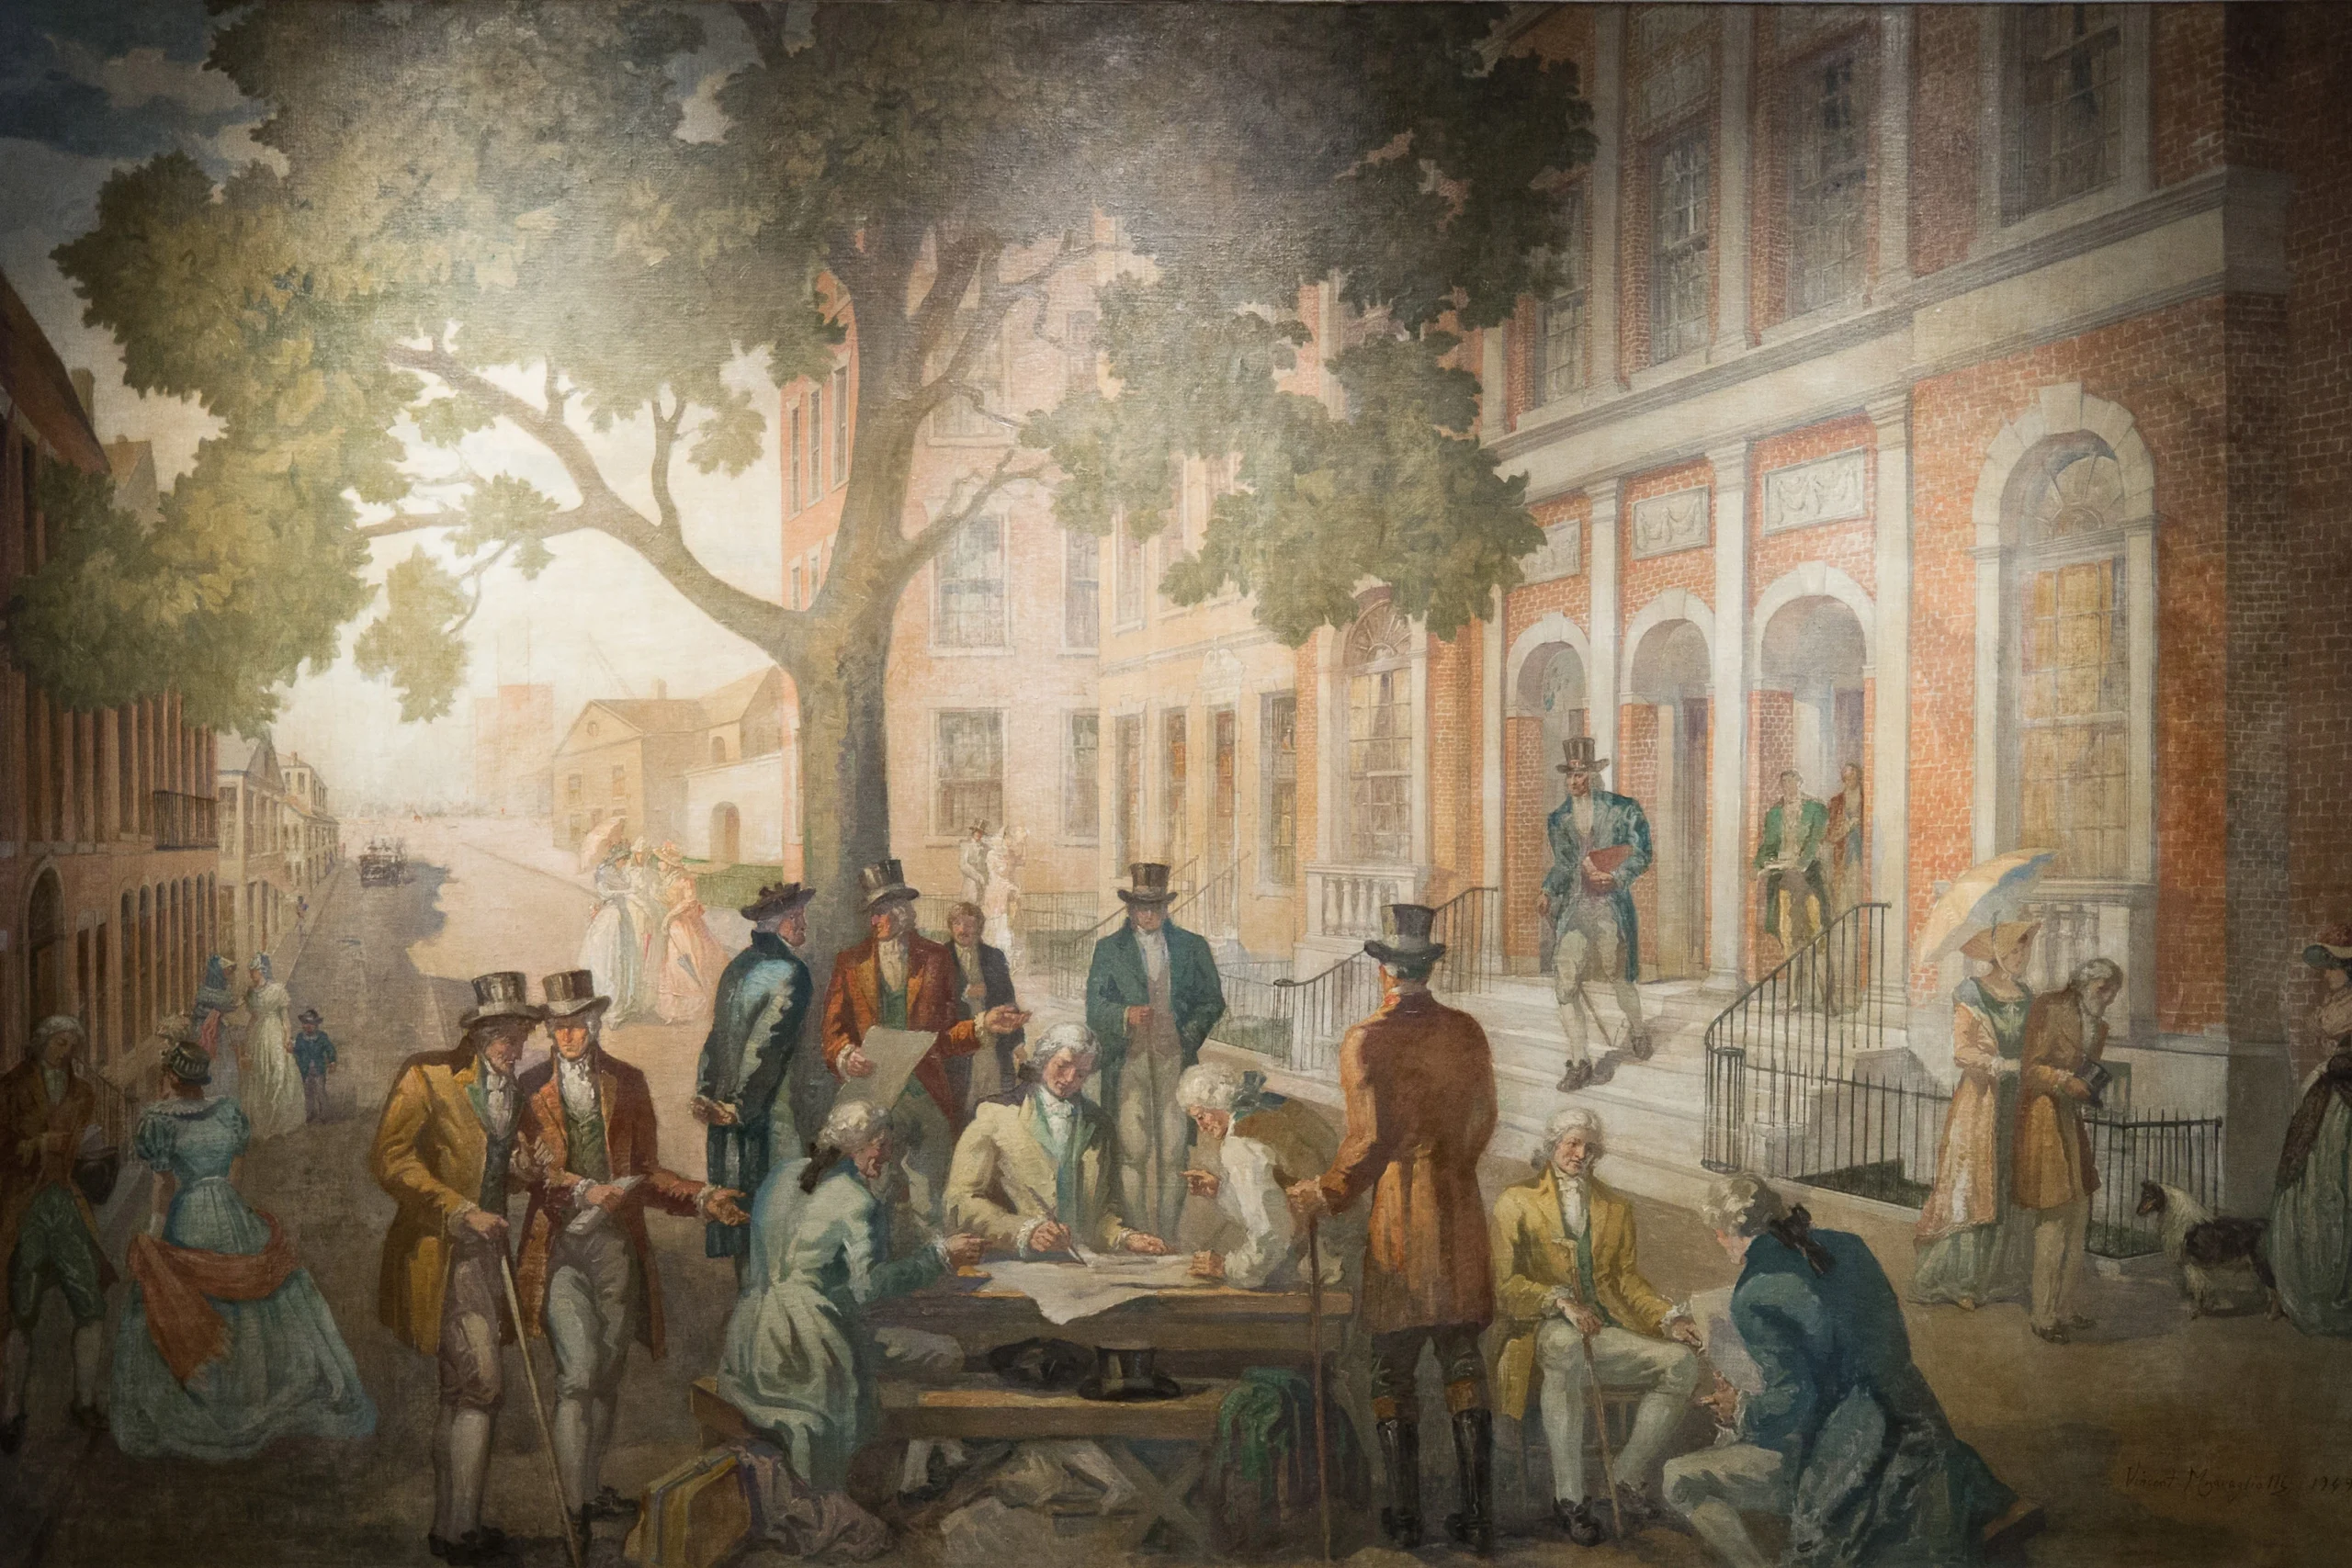
Buttonwood-Agreement-Financial-Advisor-Fiduciary-History

It contained two basic promises. The brokers agreed to charge a minimum commission, and they agreed to give preference to one another when conducting business.

That agreement helped lay the foundation for what eventually became the New York Stock Exchange.

More importantly, it established the basic economics of the brokerage business.

Brokers got paid when transactions happened. No transaction meant no commission.

For generations, that model made sense because investors couldn’t easily access financial markets without a broker.

Then everything started to change.

When Advice Became a Different Business

The stock market crash of 1929 ushered in a new era of financial regulation.

Congress passed the Securities Act of 1933 and the Securities Exchange Act of 1934. Then, in 1940, lawmakers passed the Investment Advisers Act.

That law helped establish a distinction that still matters today.

  • A broker facilitates transactions.
  • An investment adviser provides advice.

Those roles can come with different responsibilities to the client.

The concept of a fiduciary sits at the center of that distinction.

A fiduciary has a duty to put the client’s interests ahead of their own. That sounds like an obvious requirement for anyone giving financial advice, but the financial industry did not develop around a single standard.

Instead, two models grew alongside each other.

  • One focused on selling financial products and completing transactions.
  • The other focused on providing ongoing advice under a fiduciary standard.

From the outside, those professionals could look remarkably similar.

  • Same office.
  • Same suit.
  • Same industry.
  • Very different obligations.

Wall Street Saw the Conflict Early

Even some of Wall Street’s biggest names recognized the tension between advice and commissions.

Charles Merrill, one of the founders of Merrill Lynch, famously put brokers on salary rather than paying them based entirely on transactions.

The idea was simple.

If someone’s compensation increases every time a client trades, compensation can influence the advice that person gives.

Removing the transaction incentive could reduce that conflict. The model didn’t become the industry’s permanent standard.

Commission-based brokerage remained a powerful part of Wall Street for decades.

Then the economics underneath it began to collapse.

The Product Wall Street Sold Became Cheaper

For much of Wall Street’s history, brokers weren’t simply giving investors ideas.

They provided access.

By the late 20th century, technology started tearing down that barrier.

  • Stock quotes went electronic.
  • Index funds made broad market investing accessible.
  • Personal computers brought trading into homes.
  • Online brokerage accounts followed.

Then came one of the biggest blows to the traditional brokerage model.

In October 2019, Charles Schwab eliminated commissions on online stock and ETF trades. Major competitors quickly followed.

An activity that once supported an entire industry suddenly cost investors essentially nothing.

Think about what that meant.

For generations, Wall Street charged investors to execute trades.

Now investors could do it themselves from their phones.

When your core product becomes free, you need a new reason for clients to pay you.

That reason became advice.

The Stockbroker Didn’t Disappear. The Title Changed.

The language gradually shifted.

Stockbroker became financial consultant.

Financial consultant became financial advisor.

The new title sounded different because the service had changed. Investors increasingly wanted planning, guidance, tax strategy, retirement income advice, and help making decisions.

But the old brokerage model didn’t simply vanish.

Instead, the lines between brokerage and advice became harder for consumers to see.

That’s where the financial advisor vs. fiduciary conversation gets complicated.

Many financial professionals today hold more than one type of registration.

They may operate as an investment adviser in one situation and as a broker in another.

The industry calls this dual registration.

That means someone can provide fiduciary advice in certain parts of a relationship while also holding a brokerage registration that operates under a different regulatory framework, and get paid differently too.

The person sitting across from you may still carry the title “financial advisor” in both situations. That’s why the title alone tells you very little.

What Does Fiduciary Actually Mean?

A fiduciary financial advisor has a responsibility to put your interests ahead of their own when acting in a fiduciary capacity.

That distinction matters because financial recommendations can affect more than investment performance.

Consider the decisions investors make as they approach retirement:

  • Which accounts should you withdraw from first?
  • When should you claim Social Security?
  • Should you convert traditional retirement assets to Roth?
  • How should investment decisions coordinate with taxes?
  • Does an insurance product solve an actual planning need?
  • How should your estate plan fit with everything else?

These decisions rarely exist in isolation.

A true fiduciary relationship should begin with your financial life, not with a product someone wants to sell.

Why “Are You a Fiduciary?” May Not Be Enough

Here’s where things get tricky.

Ask a financial professional, “Are you a fiduciary?” and many can truthfully answer yes.

That doesn’t necessarily tell you whether they act as a fiduciary 100% of the time.

A dually registered professional may operate under a fiduciary standard in some circumstances while also maintaining a brokerage registration.

So the better question is more specific:

“Are you a fiduciary to me 100% of the time, in writing, without another registration that allows you to operate under a different standard?”

The answer should be easy to understand.

You shouldn’t need a law degree to figure out the relationship you’re entering.

Financial Advisor vs. Fiduciary: How to Check for Yourself

You don’t have to rely entirely on what an advisor tells you.

Financial professionals and advisory firms make regulatory disclosures available to the public.

Two documents can be particularly helpful.

Form ADV

Registered investment advisers file Form ADV.

It includes information about the firm’s business, services, fees, conflicts of interest, disciplinary history, and other important details.

Form CRS

Financial advisors and brokers may also provide Form CRS, short for Client Relationship Summary.

This document helps explain how the firm operates, what services it provides, how it gets paid, and potential conflicts.

Before hiring someone, read these documents. Look at how they receive compensation.

Check whether the person maintains a brokerage registration.

Then ask questions about anything you don’t understand.

Transparency shouldn’t require detective work.

Do You Even Need a Financial Advisor?

Not everyone does.

If you can build a diversified portfolio, stay invested through difficult markets, avoid chasing performance, coordinate your tax strategy, manage retirement withdrawals, and make major financial decisions without emotional interference, managing your money yourself may make sense.

You may also save a meaningful amount in advisory fees.

For everyone else, the question becomes whether professional advice delivers enough value to justify its cost.

A typical advisory fee around 1% can add up over time.

That means an advisor needs to provide value beyond simply choosing investments.

Good financial advice may include:

  • Tax planning
  • Retirement income strategy
  • Investment management
  • Behavioral coaching
  • Social Security planning
  • Risk management
  • Estate planning coordination
  • Withdrawal strategy
  • Helping you make decisions when markets get difficult

An advisor shouldn’t exist simply because investing feels complicated. The relationship should make your overall financial life better.

Why Fiduciary Advice Matters More Today

Ironically, investing has never been easier.

You can build a diversified portfolio for very little money, and use AI to help run numbers. Financial information is everywhere. Trading costs have fallen dramatically.

The harder part now is making all the pieces work together.

  • Investments affect taxes.
  • Taxes affect retirement income.
  • Retirement income affects Medicare premiums.
  • Estate decisions affect heirs.
  • Emotions affect nearly everything.

Modern financial advice should help coordinate those decisions. That’s also why understanding whether your advisor acts as a fiduciary matters.

You’re no longer paying someone simply to get you into the market.

You’re paying for judgment.

And when you’re paying someone for judgment, you should know whose interests come first.

The Stockbroker Evolved. Your Questions Should Too.

The financial industry has changed dramatically since 24 brokers met under a tree in 1792.

Paper certificates disappeared.

Trading floors became less important.

Commissions fell.

Technology gave individual investors access Wall Street once controlled.

Yet one question has survived every version of the industry:

Who does the person giving you financial advice ultimately work for?

The title on the business card won’t answer it.

“Financial advisor” can describe professionals working under very different business models.

Understanding the difference between a financial advisor and a fiduciary helps you look beyond the title and understand the relationship you’re actually entering.

Before you hand someone responsibility for decades of savings, ask how they’re registered, how they’re compensated, where conflicts could exist, and whether they will act as your fiduciary at all times.

You spent a lifetime building your wealth.

The advice you receive about it should put you first.

A Different Approach to Financial Advice

At Bonfire Financial, we believe financial advice should start with your complete financial life, not a product.

We operate as a fiduciary because we believe your interests should come first throughout the relationship.

Through the Bonfire Method, we bring investments, taxes, retirement income, insurance, and estate planning together into one coordinated strategy so you can see how each decision affects the rest. If you’re approaching retirement and want to understand whether all the pieces of your financial life are working together, learn more about the Bonfire Method.
Will AI Replace Your Financial Advisor?

Do You Still Need a Financial Advisor in the Age of AI?

Artificial intelligence can analyze investments, run retirement projections, compare tax strategies, and process enormous amounts of financial information in seconds.

That raises an obvious question: Do you still need a financial advisor?

AI already handles tasks that once required hours of research and analysis. Ask whether you can retire at 62, and AI can evaluate your income, investments, spending, Social Security, taxes, and life expectancy. It can test what happens if you retire earlier, spend more, convert part of an IRA to a Roth, or experience a major market decline.

Those capabilities will only improve.

But financial planning involves more than finding the mathematically correct answer. Your finances connect to your family, fears, goals, health, priorities, and behavior.

That distinction could determine what the financial advisor of the future looks like.

>> Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video. <<

AI Is Already Changing Financial Planning

Consider a couple wondering whether they can retire. The numbers say yes.

One spouse still hesitates because her father needed years of expensive care after retirement. Her husband wants to help their daughter buy a home nearby so they can spend more time with their grandchildren.

Suddenly, “Can we retire?” becomes a very different question.

What they really want to know is whether they can retire without becoming a financial burden while still helping their family.

AI can calculate the scenarios. A good financial advisor needs to uncover the question behind the question.

That human context matters because two people with identical portfolios may need very different financial plans.

One investor may value security after watching their parents struggle financially. Another may regret spending decades being overly cautious and want to enjoy more of their wealth while they remain healthy.

A spreadsheet can treat those investors the same.

A thoughtful advisor should not.

Information and Advice Aren’t the Same Thing

AI excels at processing information.

It can identify options, calculate tradeoffs, explain financial concepts, and evaluate more scenarios than a person could reasonably calculate alone.

Financial decisions rarely happen in perfect conditions, though.

Markets fall. Family members need help. Health changes. Priorities shift. Fear and excitement influence decisions.

That creates a gap between knowing what you should do and actually doing it.

Morningstar studied nearly 23,000 mutual funds and exchange-traded funds over the 10 years ending in 2025. The funds produced an aggregate annual return of 9.9%, while the average dollar invested earned 8.7%.

That represents a 1.2 percentage-point annual gap.

Morningstar notes that investor behavior does not explain every bit of that difference. People naturally add and withdraw money for legitimate reasons. Still, poorly timed buying and selling can keep investors from capturing the returns their investments generate.

In other words, owning a good investment does not guarantee a good investing experience.

Vanguard has also estimated that behavioral coaching from a financial advisor may add approximately 1.5 percentage points of value annually. That figure represents an estimate, not a guaranteed return.

The larger point matters more.

Sometimes an advisor creates value by preventing a client from making an expensive decision during the worst possible moment.

What Happens When Humans Use AI?

The future may not require choosing between a financial advisor and artificial intelligence.

Research suggests the combination could matter more.

One study partnered with a large European savings bank and compared three approaches to investment advice: AI alone, a human alone, and AI-generated recommendations reviewed by a human banker.

The experiment included 137 customers making real investment decisions.

Researchers found that human review did not reduce the quality of the AI-generated advice. Clients also followed the recommendations more closely when a person delivered AI-assisted advice, particularly when the investment involved more risk.

The human and AI combination increased adherence to the advice by 15.5 percentage points within the experiment.

Technology generated the analysis. A person helped make the recommendation usable.

That distinction matters because financial advice creates little value if someone never acts on it.

AI Can Make Professionals Better, But It Can Also Make Them Wrong

Another experiment involving 758 Boston Consulting Group consultants provides an interesting look at how AI affects professional work.

Consultants who used AI completed 12.2% more tasks and finished them 25.1% faster. On tasks suited to the technology, their performance improved by more than 30%.

The research did not specifically study financial advisors, so those numbers do not transfer directly to financial planning.

Still, the results show how AI can expand what a skilled professional can accomplish.

A financial advisor could use AI to evaluate more retirement scenarios, identify patterns across complicated financial information, prepare clearer explanations, or reduce repetitive analytical work.

Then the research uncovered an important problem.

When consultants received a task outside AI’s capabilities, those using AI became 19 percentage points less likely to reach the correct answer than consultants working without it.

Researchers described this uneven capability as the “jagged technological frontier.”

AI may solve one complicated problem extremely well and struggle with another that looks surprisingly similar.

The bigger danger comes from how convincing a bad answer can sound. An incorrect AI response may still appear polished, logical, and confident.

That means financial professionals need more than access to AI. They need enough experience and judgment to know when to question it.

Think of AI as a copilot, not an autopilot.

Do Investors Trust AI With Their Money?

Trust also changes depending on the financial question.

The FINRA Investor Education Foundation studied more than 1,000 American adults and found an interesting divide.

When participants evaluated projections about stock and bond performance, 34% trusted information from AI and 33% trusted information from a financial professional.

For general market information, the two sources essentially tied.

Personal advice produced a different result.

When participants evaluated portfolio-allocation recommendations, 37% trusted the financial professional compared with 30% who trusted AI.

As the decision became more personal, people placed greater trust in another person.

That suggests a natural division of labor.

AI can process information, perform calculations, and test possibilities at enormous speed. A qualified financial advisor can evaluate those results, apply them to a client’s actual life, and help determine which decision makes sense.

So, Will AI Replace Your Financial Advisor?

It may replace some of what financial advisors traditionally do.

If someone primarily provides investment reports, gathers information, or performs basic calculations, AI will continue to put pressure on the value of those services.

A strong financial advisor should offer much more.

They should understand what matters to you, identify risks you may overlook, explain your choices clearly, coordinate different parts of your financial life, and help you stay disciplined when emotions start driving decisions.

Technology can strengthen each of those capabilities when an advisor uses it correctly.

That leads to a better question than “AI or a financial advisor?”

Is your financial advisor using AI to give you better advice?

What Should You Expect From a Financial Advisor in the Age of AI?

Before deciding whether your advisor still provides enough value, consider three questions:

Are they acting as a fiduciary?

A fiduciary carries a responsibility to put your interests first.

Do they understand more than your numbers?

Your retirement plan should reflect your goals, family, concerns, priorities, and the life you actually want to live.

Are they using modern technology to improve your plan?

Ignoring AI makes little sense when the technology can help advisors analyze more possibilities and work more efficiently. Blindly trusting it makes equally little sense.

The strongest financial advisors may learn to do both.

They can use AI for speed, scale, and analytical power while applying human judgment before a recommendation reaches the client.

The Future of Financial Advice

AI probably will not eliminate great financial advisors.

It will change what clients should expect from them.

Calculations that once took hours may happen in seconds. Research will become easier. Scenario analysis will grow more sophisticated.

As technology handles more of that work, the human parts of financial planning may matter even more.

  • Judgment
  • Context
  • Accountability
  • Behavior
  • Trust.

You should not have to choose between better technology and a better human relationship.

The financial advisor of the future will need to provide both.

What Does Fee Only Really Mean

The financial world has a jargon problem. It is filled with terminology that feels like it was designed to confuse people. And for decades, some parts of the industry preferred it that way. When clients do not fully understand how advisors get paid, it becomes easier for advisors to hide conflicts of interest, justify unnecessary expenses, or disguise sales incentives as financial guidance.

But there is one term that cuts through a huge amount of that confusion: fee only.

This single phrase tells you almost everything you need to know about the type of advice you are getting, the level of transparency you can expect, and whether your advisor is required to put your interests ahead of their own. At Bonfire Financial, we believe fee only advice is the future of the industry and the clearest path to an honest, trust centered financial relationship.

Today we are going to break down exactly what fee only means, how it compares to commission based advice, why the fiduciary standard matters, and how to protect yourself in a world where not all advisors are required to work in your best interest. Let us dive in.

Listen Now: iTunes | Spotify | iHeartRadio | Amazon Music

Why the Term “Fee Only” Matters More Than Most People Realize

Most people assume their financial advisor works for them. They believe the advice they receive is based on what is best for their financial future, not what is best for the advisor’s paycheck. But unfortunately, that is not always the case.

There are three main types of advisors:

  1. Commission based advisors

  2. Fee based advisors

  3. Fee only advisors

These terms sound similar, but the differences are massive.

A commission based advisor gets paid when they sell something. It could be a mutual fund, an annuity, a life insurance policy, or even a stock transaction. Every recommendation is tied to a payout.

A fee based advisor is a mix of both. They can charge a fee and also collect commissions. This creates one of the most confusing and dangerous environments for clients because you never know which hat they are wearing when they give you advice.

A fee only advisor, which is what we are at Bonfire Financial, gets paid only by the client and only through a transparent fee arrangement. Fee only advisors cannot accept commissions on the products they recommend.

Why does this matter?

Because the way an advisor gets paid directly shapes the advice you receive. If someone makes money when you buy or sell a product, the incentives shift. Suddenly, the advice you receive might not be about what is best for you. It might be about what keeps their mortgage paid that month.

Fee only removes those conflicts. It creates a clean, transparent, and aligned relationship where your advisor only wins when you win.

How Commission Based Advice Became the Industry Norm

To understand why fee only matters, we have to look back at how the financial industry operated for decades.

Before financial planning became a profession, most advisors were essentially stockbrokers. Their job was to call clients and recommend trades.

  • Buy this stock.
  • Sell that fund.
  • Switch into this new product.

Every single trade generated a commission. If an advisor could convince a client to buy something or sell something, they got paid. It did not matter whether the advice was good, bad, or neutral.

This created three dangerous realities:

1. Advisors could profit regardless of performance.

A client could lose money and the advisor could still get paid.

2. Advisors were incentivized to create activity even when unnecessary.

Buying and selling generated income. Holding did not.

3. Advisors could recommend expensive, high commission products even when cheaper, better solutions existed.

Clients rarely knew the difference.

This setup created a system where investors could not always trust whether a recommendation was truly for their benefit or simply profitable for the advisor.

And while the industry has evolved, this commission based model is still alive today.

The Suitability Standard vs the Fiduciary Standard

(Why You Should Care)

One of the biggest problems with commission based advice is the standard advisors are held to.

Commission based advisors follow the suitability standard.

Fee only fiduciaries follow the fiduciary standard.

Let us look at what that means.

The Suitability Standard: A Low Bar

Under suitability, an advisor only has to demonstrate that a recommended product is “suitable” for someone of your general profile.

For example:

  • You are 40

  • You make 150,000 dollars a year

  • You have moderate risk tolerance

If a product could be considered reasonable for someone in that demographic, it meets the suitability requirement.

The advisor does not have to choose the best option.

  • They do not have to choose the cheapest option.
  • They do not have to disclose conflicts.
  • They do not have to put you first.

This is an incredibly low bar.

The Fiduciary Standard: A Higher Level of Care

Fee only Registered Investment Advisors (RIAs) are held to a true fiduciary standard.

This means:

  • They must act in your best interest.

  • They cannot put their compensation ahead of your outcome.

  • They must disclose conflicts.

  • They cannot sell commission based products.

  • They must recommend the best option available, not just a suitable one.

This is a completely different universe of advice.

The Hidden Conflicts Many Investors Never See

When someone can earn a commission, several conflicts appear whether they want them to or not.

Here are the biggest ones.

1. Advisors might recommend a product because it pays more.

Annuities, private REITs, insurance products, and certain mutual funds can pay commissions as high as 5 to 10 percent.

If two products accomplish the same goal but one pays a big commission, which one will a commission based advisor be tempted to recommend?

2. Advisors might encourage unnecessary trading.

If selling generates income, sales magically become more appealing.

3. Advisors might prioritize their own cash flow needs over your goals.

It might not be intentional.
It might not be malicious.
But it happens.

4. Advisors are not required to disclose these conflicts upfront.

Most people only discover these details buried in long documents filled with legal language.

This is the opposite of transparency.

The Power of Fee Only Advice

Fee only eliminates all of the above.

Here is what fee only advisors cannot do:

  • They cannot collect commissions.

  • They cannot be paid more for selling specific products.

  • They cannot hide compensation in product costs.

  • They cannot recommend something because it pays better.

What fee only advisors can do:

  • Charge a clear, transparent fee.

  • Put the client first.

  • Provide unbiased advice.

  • Focus on planning, not product sales.

  • Build long term relationships based on trust.

This is why fee only advice has become the gold standard among educated investors and why more people are seeking RIAs instead of commission based advisors.

How Fee Only Advisors Actually Get Paid

Fee only advisors typically charge one of three ways.

1. Hourly Fees

Like attorneys or accountants. Not our favorite model because clients often rush conversations or avoid asking questions.

2. Flat or Project Based Fees

Great for specific projects like financial plans, retirement strategies, or education planning.

3. AUM Fees (Assets Under Management)

A percentage of assets the advisor manages. For example, 1 percent per year on one million dollars equals ten thousand dollars annually.

This fee covers:

  • Portfolio management

  • Ongoing planning

  • Consultations

  • Strategy work

  • Adjustments

  • Support during major life changes

AUM fees align incentives because the advisor only grows their revenue when your portfolio grows. Your success becomes their success.

How to Know if an Advisor is Truly Fee Only

Sadly, many advisors use confusing language to appear fee only when they are not.

Here are five questions you should always ask:

1. Do you accept commissions of any kind?

The answer must be a clear, direct “no”.

2. Are you always acting as a fiduciary?

Not sometimes. Not only when convenient. Always.

3. Are you dually registered?

If yes, they can switch hats between fee only and commission.

4. How are you compensated?

They should be able to explain it in one clean sentence.

5. Can I see your Form ADV?

This document legally outlines how they get paid.

Any hesitation is a red flag.

Why Fee Only Protects Your Financial Future

Fee only advice is not just about fees.
It is about trust, transparency, and alignment.

When you choose a fee only fiduciary, you get:

  • Clear recommendations

  • No hidden agendas

  • Advice rooted in your best interests

  • More confidence in your long term plan

  • A healthier advisory relationship

Money is emotional. It is tied to your goals, your family, your future, and your security. You deserve an advisor who treats your financial life with the care and clarity it deserves.

Why Bonfire Financial Chose Fee Only

Bonfire Financial was built from the belief that clients deserve transparency, honesty, and unbiased advice. There should never be a moment where a client wonders:

“Are you recommending this because it helps me or because it pays you more?”

That question should not exist in a healthy advisory relationship.

By choosing the fee only RIA model, Bonfire Financial removed all product based compensation and all commission conflicts. When we sit across from a client, we can give clear, direct, transparent advice without worrying about how a product pays or whether a transaction generates revenue.

Fee only allows us to:

  • Dive deeper into planning

  • Spend more time understanding clients

  • Give unbiased recommendations

  • Build long term trust

  • Support families through major life events

  • Focus on what is best for you

This model creates what we consider the healthiest and most ethical advisor client relationship.

Final Thoughts: Fee Only Is the Standard Every Investor Deserves

The financial industry can be confusing, and that confusion often benefits advisors who profit from opacity. But you do not have to accept that. You can choose a relationship built on transparency and aligned incentives.

Fee only advice is not a marketing buzzword. It is a higher standard of care, a commitment to honesty and a structure that ensures your interests come first.

At Bonfire Financial, it is the only way we believe financial advising should work.

If you want to explore what fee only advice looks like for your family, schedule a call with us today to learn more.

Your financial future deserves clarity. Fee only gives you that clarity.

What Is a Fiduciary Financial Advisor? And how a free lunch could cost you.

If you’re looking for trustworthy financial advice, one term you need to understand is: fiduciary financial advisor. It might sound like industry jargon, but it’s one of the most important distinctions in the financial planning world. Put simply, a fiduciary financial advisor is someone who is legally and ethically required to act in your best interest. Not all advisors are held to this standard, and that difference could cost you.

Today we’ll break down what it really means to work with a fiduciary advisor, how to know if yours is one, and why this matters when it comes to your money, your goals, and your peace of mind.

Listen Now:  iTunes |  Spotify | iHeartRadio | Amazon Music

What Is a Fiduciary Financial Advisor?

A fiduciary financial advisor is a professional who has a legal obligation to act solely in your best interest when providing financial advice or managing your investments.  This means the recommendations they give you must benefit you, not their paycheck. They must avoid conflicts of interest and fully disclose anything that could influence their advice.

That might sound obvious, shouldn’t every financial advisor do that? You’d think so, but unfortunately, many don’t.

Fiduciary in Action: What It Really Looks Like

Imagine you’re working with a financial advisor, and they present you with two investment options:

  • Investment A pays the advisor a higher commission

  • Investment B is nearly identical but pays the advisor much less (or nothing)

Under the fiduciary standard, if Investment B is in your best interest, that’s the one the advisor must recommend, even if it means they earn less. It’s not just about ethics. It’s the law.

That’s a huge deal when you’re talking about life savings, retirement accounts, and generational wealth. But without the fiduciary obligation, nothing stops an advisor from choosing the option that’s more lucrative for them, even if it costs you more.

Why the Fiduciary Standard Exists

The financial services industry hasn’t always had a great reputation. From high-commission sales tactics to conflicts of interest that aren’t always disclosed, the history is… let’s say, complicated. The fiduciary standard was created to protect clients from these conflicts. It’s meant to ensure that when you work with a financial advisor, you’re not just being sold something. You’re being advised, and the advice is in your best interest.

And yet, not everyone is held to this standard.

Wait, Not All Advisors Are Fiduciaries?

Correct. There are three basic types of advisors when it comes to fiduciary duty:

  1. Non-fiduciary brokers – These operate under a “suitability” standard. The investment just has to be suitable, not necessarily the best or most cost effective.

  2. Hybrid advisors – These can switch hats. In some accounts, they act as fiduciaries. In others, they can accept commissions. That dual role can create confusion.

  3. Fee-only fiduciary advisors – These are always fiduciaries. Fee-only advisors typically don’t accept commissions or sales incentives, which helps reduce conflicts of interest.

At Bonfire Financial, we chose to be a fee-only fiduciary firm because we didn’t want to operate in gray areas. We didn’t want to have to switch hats depending on the product or compensation structure. We wanted to build a business grounded in trust, because that’s what our clients deserve.

A Quick (and Real) Story: The Power of a Free Lunch

Let me paint a picture of what it doesn’t look like to act in a client’s best interest.

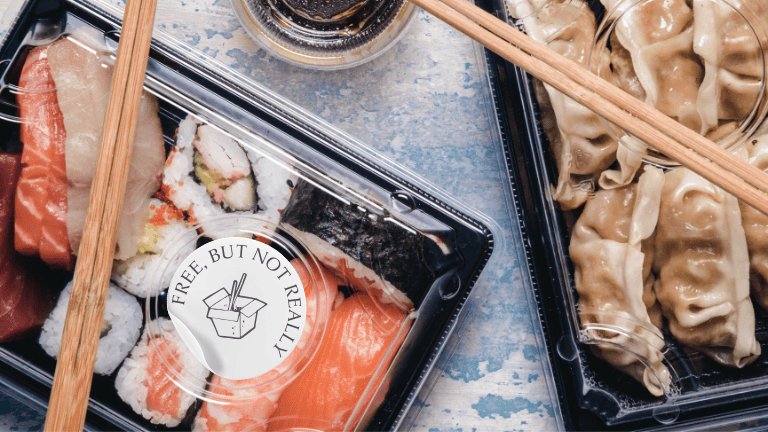
When I was early in my career at a large wirehouse, there was an informal group I jokingly called “The Lunch Hour Club.” Wholesalers, salespeople for investment products like mutual funds or annuities, would come in and treat advisors to lunch. Think sushi, steak sandwiches, the works!

In exchange? They hoped we’d recommend their products to our clients.

And sometimes, it worked.

Some advisors would literally recommend a mutual fund just because the wholesaler bought them a good meal. They weren’t necessarily bad people. But without a fiduciary standard, there was nothing stopping that kind of behavior.

It drove me nuts.

That experience was a big part of why I left and started my own independent firm. I didn’t want to operate in a system where a sandwich could steer someone’s retirement plan.

Transparency Is Key

Another cornerstone of fiduciary duty is disclosure. If there’s ever a potential conflict of interest, a fiduciary has to tell you. If an advisor owns a stake in a product they’re recommending or will be compensated in any additional way, you have a right to know before making a decision.

That doesn’t mean all commission-based advisors are unethical. Many are great people trying to do the right thing. But even good intentions can be overshadowed by unclear incentives and a lack of transparency.

With a fiduciary, you don’t have to wonder if you’re getting the full story. You are.

Trust Is the Real Currency

At the end of the day, this business is all about trust. When someone comes to us for financial advice, they’re not just asking where to invest. They’re trusting us with their future. Their kids’ college fund. Their retirement. Their legacy.

If you’re going to work with a financial advisor, you need to feel absolutely sure that they’re putting your interests first. That they’ll tell you the truth, even when it’s not convenient. That they’ll say no to a product or strategy that benefits them but doesn’t benefit you.

That’s the kind of relationship that lasts. That’s the kind of advisor you want in your corner.

How to Know If Your Advisor Is a Fiduciary

Here are a few key questions to ask:

  • Are you a fiduciary 100% of the time?

  • How are you compensated?

  • Do you ever earn money from third parties?

  • Are you a CFP®?

  • Will you put that in writing?

If any of the answers feel vague or avoidant, that’s a sign to dig deeper. A true fiduciary will be transparent and direct.

Why We Believe It Shouldn’t Be Optional

The fact that fiduciary duty is optional in parts of the financial industry is baffling. It’s like going to a doctor and not knowing if they’re being paid extra to prescribe a certain medication. You’d want to know, right?

We believe every financial relationship should start with this simple premise: put the client first. Always.

And if that means we make a little less on one decision? So be it. We’re playing the long game. Doing right by our clients has a way of working out.

Bottom Line: Choose Trust Over Hype

There will always be advisors out there chasing commissions, recommending high-fee products, or overpromising results. And there will always be flashy marketing campaigns pushing financial “solutions” that are more sizzle than substance.

But you don’t have to fall for it.

When you choose to work with a fiduciary advisor, you’re choosing clarity. You’re choosing transparency. You’re choosing a partnership built on trust—where your goals, your success, and your future come first.

And that’s how financial advice should work.

Need a fiduciary advisor you can trust?

At Bonfire Financial, we’re 100% fiduciary, 100% of the time. No commissions. No product pushing. Just honest advice built around you. If you want to see what that looks like, we’d love to talk.

Schedule a conversation with us at BonfireFinancial.com

4 Reasons to Hire a CFP ®

4 Reasons to Hire a CFP ®

Managing your finances can be difficult and time-consuming. However, finding someone to handle your finances can be just as challenging. Want a tip to make it easier? Hire A CFP ®.

People often ask us what is a CFP ®, how are they different from other financial advisors, and the reasons to hire a CFP ®. We are going to be breaking all that down for you today.

What Is a CFP® Professional?

First, it’s more than just an acronym. Unlike some designations that are worth little more than the paper they’re printed on, the CFP ® (CERTIFIED FINANCIAL PLANNER™) designation is one of the most esteemed financial certificates around.  Each CFP ® is held to an extremely high standard and requires an immense amount of work. Typically nine months to two years of study.

In the US, as of 2025,  there are only 101,505 CFPs ® and only 3,150 in the state of Colorado, according to the CFP® Board professional demographics.  The exam itself is a grueling 7-hour test that assesses the financial advisor’s ability to apply principles of financial planning. It covers all areas of insurance, investments, income taxes, retirement, estate planning, ethics and conduct, and financial plan development, among many other skills.

Beyond the test, there is so much more that goes into the certification. We have condensed it down to the top 4 Reasons to Hire a CFP®.

4 Reasons to Hire a CFP ®

  1. Fiduciary Standard
  2. Ethics Code
  3. Fitness Standards
  4. Experienced Life-Long Learners

Let’s dive into it:

1. Fiduciary Standard:

Currently, the SEC has NO uniform fiduciary standard that applies to all financial professionals who provide personalized investment advice. This means there is no oversight to protect consumers and clients from paying excessive commissions or receiving substandard performance. Consumers are exposed to even greater and unnecessary risks from products that may be deemed suitable (more on that here) for them but are inferior to other available options and not necessarily in their best interests.

The CFP ® Board has a Code and Fiduciary Standards that require CFP ® professionals to act in the best interest of the client at all times when providing financial advice. So, as a CFP ®, we have a legal requirement to act in your best interest, all the time. In addition to this standard as a true fiduciary, Bonfire Financial is also a Registered Investment Advisor which furthers this obligation.

2. Ethics Code:

All CFP ® practitioners agree to abide by a strict code of professional conduct, known as CFP ® Board’s Code of Ethics and Professional Responsibility, that sets forth ethical responsibilities to the public and clients. This ensures we act with honesty, integrity, competence, diligence, and offer services objectively.

It’s a pledge to protect the confidentiality of all client information, avoid or disclose and manage conflicts of interest and always act in the client’s best interests.

3. Fitness Standards:

Further, the CFP ® Board has also established specific character and fitness standards for the CFP ® certification. This ensures that an individual’s prior conduct would not reflect adversely upon the profession or the CFP ® certification marks. This helps you know that if you hire a CFP ® you won’t find out later that they have:

    • A felony conviction for theft, embezzlement, or other financially-based crimes.
    • A felony conviction for tax fraud or other tax-related crimes.
    • Revocation of a financial license (e.g. registered securities representative, broker/dealer, insurance, investment advisor).
    • A felony conviction for any degree of murder or rape.
    • A conviction for any other violent crime within the last five years.
    • A felony conviction for non-violent crimes (including perjury) within the last five years.
    • Personal or business bankruptcies.

4. Experienced Life-Long Learners:

CFP ® professionals are required to complete 3 years of experience related to delivering financial planning services to clients. They also must have a bachelor’s degree prior to earning the right to be a CFP ®. This real-life experience means that CFP ® professionals have practical financial planning knowledge. They can truly help you create a realistic financial plan that fits your individual needs.

Once certified, CFP ® professionals are required to maintain technical competence and fulfill ethical obligations. Every two years, they must complete a minimum of 30 hours of continuing education to stay current with developments in the financial planning profession and better serve clients.

Need more reasons to hire a CFP ®? We’d love to answer any other questions on what it means to have a CFP ® working for you, feel free to contact us.

At Bonfire Financial we pride ourselves on having a team of CERTIFIED FINANCIAL PLANNERs™ and we can’t wait to help you!


4 Reasons to Hire a CFP


Thank You For Your Subscription

You’re in! Thanks for subscribing to our monthly newsletter. We will be sending you market updates, financial insights and inspiring travel ideas soon but in the meantime check out our blog, join us on Instagram or pop over to Pinterest.

Your Appointment Request has been Received

Thank you for reaching out! We are excited to learn more about you. Someone from our team will be in touch shortly.

Sign up now

Join us around the fire for monthly market updates, financial insights and inspiring travel ideas.

.

Sign up now

Receive tips

Give us a call

(719) 394.3900
(844) 295.0069