The Best Investment Strategies for High-Income Earners: $100K, $300K and $600K+

Smart Investment Strategies for High-Income Earners

Financial advice should change as your income grows.

A strategy that works well for someone earning $100,000 may leave major opportunities on the table for someone earning $300,000 or $600,000. Higher income creates more flexibility, but it also introduces additional tax exposure, investment choices, and retirement planning decisions.

The goal is not simply to save more money. You need to use the right accounts, manage taxes intentionally, and build a financial structure that supports both your current lifestyle and your future goals.

Here are several investment strategies for high-income earners at three different income levels.

Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.

Financial Strategies for Someone Earning $100,000

At the $100,000 income level, cash flow still plays a major role in financial planning.

You may earn a strong income, but housing costs, family expenses, debt payments, and everyday spending can limit how much you have available to invest. Your first priority should be making each dollar work as efficiently as possible.

Start With Your 401(k)

A workplace retirement plan often provides the easiest place to begin.

At a minimum, contribute enough to receive the full employer match. That match represents additional compensation, so failing to claim it means leaving money behind.

Once you receive the full match, consider increasing your contribution rate over time. People over age 50 may also qualify for catch-up contributions, which can create additional room for retirement savings.

You do not need to reach the annual maximum immediately. Choose an amount that allows you to save consistently without creating unnecessary financial pressure.

Consider a Roth IRA

A Roth IRA can add valuable tax diversification to your retirement strategy.

You contribute money after paying income taxes. The account can then grow tax-free, and qualified withdrawals generally remain tax-free during retirement.

Income limits may restrict direct Roth IRA contributions for some households. A financial or tax professional can help determine whether a backdoor Roth strategy makes sense for your situation.

Use a Health Savings Account

A health savings account, or HSA, can serve as both a healthcare tool and a long-term investment account.

HSAs offer three potential tax advantages:

  • Contributions may reduce taxable income.
  • Investments inside the account can grow tax-free.
  • Qualified medical withdrawals remain tax-free.

Many people use their HSA only for current medical bills. High-income earners may benefit from investing the balance and allowing it to grow for future healthcare expenses.

Financial Strategies for Someone Earning $300,000

At the $300,000 income level, your planning opportunities expand.

You may already contribute the maximum to your workplace retirement plan. You may also have additional cash available for investing, charitable giving, and long-term tax planning.

This is where financial coordination becomes increasingly important.

Explore a Mega Backdoor Roth

Some employer retirement plans allow after-tax contributions beyond the standard employee contribution limit.

When the plan also allows in-plan Roth conversions or qualifying rollovers, you may be able to use a strategy known as a mega backdoor Roth.

This approach can move a significant amount of money into a Roth account, where it may grow tax-free. However, not every workplace plan supports the necessary features.

Review your plan documents before attempting the strategy. Your plan administrator and financial advisor can help you confirm the available options.

Consider a Donor-Advised Fund

A donor-advised fund may help charitably inclined households organize their giving while creating potential tax benefits.

Instead of making the same charitable contribution every year, you can combine several years of donations into one larger contribution. This approach is often called charitable bunching.

The larger contribution may allow you to itemize deductions in that tax year. You can then recommend grants from the fund to qualified charities over time.

A donor-advised fund works best when charitable giving already forms part of your financial plan. The tax deduction should support your generosity, not drive it.

Build a Taxable Brokerage Account

Retirement accounts provide valuable tax benefits, but they also come with restrictions.

A taxable brokerage account adds flexibility. You can access the money before retirement, use it for major purchases, or rely on it during years when you want to manage taxable retirement withdrawals.

Taxable accounts also support long-term investment goals that do not fit neatly inside a retirement plan.

Use Tax-Loss Harvesting Carefully

Tax-loss harvesting involves selling investments that have declined in value and using those losses to offset taxable gains.

When used properly, this strategy may reduce your current tax bill while keeping your portfolio aligned with your long-term plan.

Tax-loss harvesting requires careful execution. You need to consider transaction costs, portfolio changes, and wash-sale rules before making trades.

Do not sell an investment solely to generate a tax loss. The decision should still make sense within your broader investment strategy.

Financial Strategies for Someone Earning $600,000 or More

At $600,000 or more, the planning landscape changes considerably.

You may have already maximized traditional retirement accounts, funded Roth strategies, and built a substantial taxable portfolio. Your next opportunities may involve business retirement plans, alternative investments, insurance strategies, and advanced tax planning.

These strategies can provide meaningful benefits, but they often require more coordination and longer commitments.

Evaluate a Cash Balance Plan

Business owners, partners, and certain highly compensated professionals may benefit from a cash balance plan.

A cash balance plan is a type of defined benefit retirement plan. Depending on your age, business structure, and plan design, it may allow you to contribute significantly more than a traditional 401(k).

These plans can create substantial tax deductions while accelerating retirement savings.

However, they also require consistent funding, professional administration, and careful design. A cash balance plan works best for someone with stable income who expects to maintain the plan for several years.

Review Insurance-Based Strategies

Some high-income earners explore permanent life insurance as part of a broader financial plan.

Certain policies can provide tax-deferred cash value growth and a death benefit. They may also create an additional source of funds later in life.

Insurance products can become expensive and complicated. They often require ongoing contributions, and poor policy design can reduce their effectiveness.

Treat insurance as a planning tool, not a substitute for a diversified investment portfolio. Review the costs, assumptions, and long-term obligations before committing.

Consider Private Investments

High-income and accredited investors may gain access to private investments that are not available through public markets.

These opportunities may include:

  • Private real estate
  • Limited partnerships
  • Private credit
  • Oil and gas investments
  • Private equity
  • Venture capital

Private investments can offer income, growth, diversification, or tax advantages. They can also carry higher fees, limited liquidity, reduced transparency, and greater investment risk.

Before investing, understand how long your money may remain locked up. Review the sponsor, track record, legal structure, fees, and underlying assets.

Explore Opportunity Zone Investments

Opportunity zone investments may provide tax benefits for investors who reinvest eligible capital gains into qualified funds.

The investment typically supports businesses or real estate projects in designated areas. Investors may receive favorable tax treatment on future appreciation when they meet specific holding requirements.

Tax advantages alone do not make an investment attractive.

You still need to evaluate the property, business plan, market fundamentals, management team, fees, and exit strategy. A poorly structured investment does not become a good investment simply because it offers tax benefits.

The Three-Bucket Investment Strategy

Regardless of income, investors should avoid relying on only one type of account.

Many people place most of their retirement savings into tax-deferred accounts such as traditional 401(k)s and IRAs. These accounts provide tax benefits today, but future withdrawals generally create taxable income.

Large tax-deferred balances can also lead to significant required minimum distributions later in retirement.

A more flexible approach uses three different tax buckets.

1. Tax-Deferred Accounts

Tax-deferred accounts may include traditional 401(k)s, 403(b)s, and traditional IRAs.

Contributions may reduce taxable income today. The investments can grow without annual taxation, but withdrawals generally count as taxable income.

2. Tax-Free Accounts

Tax-free accounts may include Roth IRAs and Roth 401(k)s.

You contribute after-tax dollars, but qualified withdrawals generally remain tax-free. Roth assets can provide valuable flexibility when managing retirement income and future tax brackets.

3. Taxable Accounts

Taxable accounts include standard brokerage and investment accounts.

These accounts do not provide the same upfront tax advantages, but they offer fewer withdrawal restrictions. Investors may also benefit from long-term capital gains rates, tax-loss harvesting, and greater access to their money.

Holding assets across all three buckets can give you more control over where your retirement income comes from each year.

That flexibility may help you manage taxes, fund large expenses, complete Roth conversions, or avoid drawing too heavily from one account.

Your Income Should Influence Your Financial Plan

Someone earning $100,000 may need to focus on cash flow, employer matching, Roth contributions, and HSA funding.

Another earning $300,000 may begin using mega backdoor Roth contributions, donor-advised funds, taxable investment accounts, and tax-loss harvesting.

Someone earning $600,000 or more may explore cash balance plans, private investments, opportunity zones, and carefully structured insurance strategies.

No single strategy works for every high-income household. Your income matters, but so do your age, goals, business structure, family needs, risk tolerance, tax situation, and retirement timeline.

Generic financial advice rarely accounts for all of those variables. A coordinated financial plan can help you identify which opportunities deserve your attention and which ones add unnecessary cost or complexity.

The right investment strategy should help you grow wealth, reduce avoidable taxes, and maintain enough flexibility to enjoy the life you are building today.

Build a Strategy Around Your Life

The Bonfire Method brings your investments, taxes, retirement income, and personal goals into one coordinated plan. Instead of relying on generic advice, we help you understand where you are today, identify the opportunities that fit your income level, and create a clear strategy for what comes next.

If you are ready to make more intentional decisions with your wealth, schedule a complimentary call and learn how the Bonfire Method can help you build a plan designed around your life.
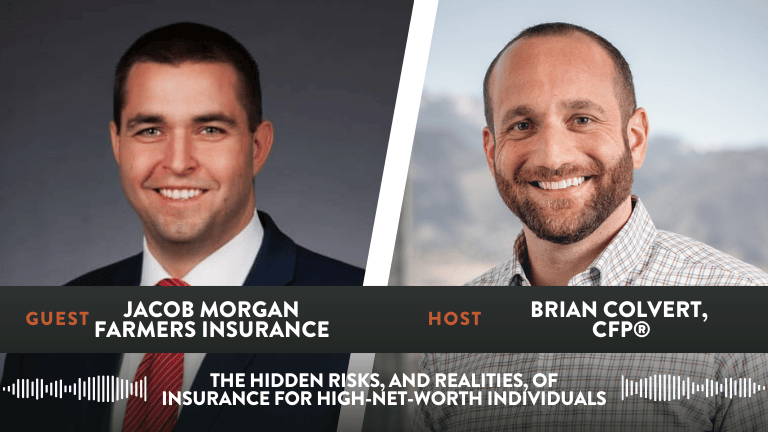
The Hidden Risks, and Realities, of Insurance for High-Net-Worth Individuals

Insurance for high net worth individuals

For high-net-worth individuals, wealth offers a sense of freedom, security, and choice. But with greater assets comes greater risk. While insurance is often seen as a check-the-box necessity, the truth is that many affluent individuals are unknowingly underinsured. This leaves them exposed to potential financial disaster in the event of a major claim.

Today we’re breaking down the hidden risks and how high-net-worth individuals can better protect their homes, vehicles, and lifestyles with the right insurance strategies. Drawing from a recent conversation with Jacob Morgan, a top 1% Farmers Insurance agent and President’s Council member, we’ll uncover the current trends, common mistakes, and smarter moves you should be making today.

Listen Now:

iTunes |  Spotify | iHeartRadio | Amazon Music

—–

Why Standard Insurance Isn’t Built for the Affluent

Most people begin their insurance journey by shopping for the cheapest premium. It makes sense when you’re starting out. But as your assets grow, that approach quickly becomes dangerous.

Standard policies often have coverage caps that don’t align with the true value of luxury homes, exotic cars, or high-end personal items. Additionally, claims service, deductibles, and replacement cost policies may not be designed for unique needs.

Jacob Morgan puts it plainly: “If you’re worth $10 million and living in a fire-prone area with a custom-built home, you’re in a totally different risk category. You’re not just another house on the block. You’re a one-of-a-kind risk.”

The Reinsurance Crisis: Why Premiums Are Skyrocketing

One of the key drivers of rising insurance premiums in recent years is the cost of   . Reinsurance is essentially insurance for insurance companies. When disasters like hurricanes, wildfires, and massive hailstorms happen, the losses get passed up the chain—and ultimately, back down to consumers.

In 2023 alone, the insurance industry lost $43 billion. By mid-2024, the industry had already hit that figure again. Reinsurance markets are tightening, especially in high-risk zones like:

  • California (wildfires, earthquakes)
  • Florida (hurricanes)
  • Colorado (hail, wildfires)
  • Texas (wind, flood)

These macro pressures are pushing premiums higher, and in some cases, making coverage harder to find altogether. For high-net-worth individuals, this means more scrutiny and significantly higher costs to insure homes in these areas.

Why Wealthy Individuals Are Hit Harder

Affluent clients often find themselves on the losing end of insurance pricing, but not by accident. The very things that make luxury living so desirable—beautiful locations, expansive properties, custom features—also make them high-risk to insure. Insurers are increasingly scrutinizing these properties and passing along higher costs to cover the growing risks and potential losses. Here’s why:

  1. Aggregation of Risk: Insuring a $20 million mansion is not the same as insuring ten $500,000 homes. A single loss can devastate a carrier’s bottom line.
  2. Location, Location, Risk: Luxury homes tend to be in scenic, exclusive areas—on the coast, in the mountains, or in rural getaways. These spots also happen to be more vulnerable to disasters and far from emergency services.
  3. Luxury = Higher Replacement Costs: A tile roof on a million-dollar home isn’t just more expensive—it can be exponentially more expensive. Add in custom cabinetry, imported finishes, and high-end tech, and you’re looking at rebuild costs far beyond what standard policies account for.

Common Insurance Mistakes High-Net-Worth Individuals

Despite having the means to afford proper protection, many wealthy individuals unknowingly fall into common insurance traps. These oversights often stem from a set-it-and-forget-it mentality, or from applying the same logic they used in their early financial lives. Let’s explore the most frequent mistakes and how to avoid them.

  1. Staying with the Same Policy for Too Long: Jacob shares that before he opened his agency, he had the same policy for 12 years without ever reviewing it. He later discovered major gaps in coverage. Your lifestyle evolves—your insurance should too.
  2. Chasing the Lowest Premium: While it might be tempting to price-shop insurance the same way you do flights or hotel rooms, this can lead to inadequate coverage. Insurance companies don’t create all policies equally—especially when it comes to endorsements and exclusions.
  3. Low Deductibles on High-Value Assets: Affluent individuals often keep deductibles low out of habit, but this can cost you thousands in premiums. Raising deductibles on high-value items like homes and luxury vehicles can significantly reduce your annual costs while making sense for your cash flow.
  4. Overinsuring Market Value Instead of Rebuild Cost: Many homeowners assume they should insure their home for its market value. In reality, insurance covers rebuild costs, not what Zillow says your home is worth.
  5. Skipping Liability and Umbrella Coverage: As wealth grows, so does visibility and the likelihood of being targeted in a lawsuit. Umbrella policies can be an inexpensive safeguard—often as little as $500 per year for millions in added protection.

Smarter Insurance Strategies for High-Net-Worth Individuals

If you’re building or preserving significant wealth, your insurance strategy needs to be just as sophisticated. It’s not only about coverage amounts. It’s about who manages your coverage, how often it’s reviewed, and what protections are in place when the unexpected happens. Here are some high-impact strategies that can dramatically improve your risk management approach.

  1. Work with an Agent Who Specializes in Affluent Clients: A knowledgeable agent can tailor policies based on your asset mix, lifestyle, and risk exposure. For example, a home in Vail, a yacht in Miami, and a classic car collection all require different layers of coverage and carriers that understand the nuances.
  2. Bundle Strategically: While bundling home and auto can provide discounts, sometimes splitting carriers is the better choice—especially if you have properties in multiple states.
  3. Review Policies Annually or After Major Life Changes: If you renovate your home, buy a new vehicle, acquire art, or add a vacation home, it’s time to review your policies. Even if nothing major changes, plan on an annual review to ensure you’re not overpaying or undercovered.
  4. Customize Coverage With Endorsements: High-value personal property often needs specialized endorsements. Think: collectibles, watches, wine collections, sports memorabilia, home offices, or smart-home systems. Avoid assuming that a standard policy fully covers these items.
  5. Embrace Higher Deductibles Where It Makes Sense: As Jacob suggests, if you can easily afford a $2,500 or $5,000 deductible on your home or car, consider increasing it. Use the savings to enhance your liability limits or invest in umbrella coverage.
  6. Invest in an Umbrella Policy: Liability claims can come from car accidents, injuries on your property, or even social media defamation. Umbrella insurance picks up where your primary coverage stops, providing extra peace of mind.

Jacob noted that in his book of business, only two umbrella claims have been made. Both were worth more than the premiums collected from hundreds of policies—and they saved the clients from serious financial harm.

Final Takeaway: Don’t Set It and Forget It

Insurance for high-net-worth individuals is not just a formality, it’s a strategic pillar of wealth protection. Unfortunately, too many people spend decades building wealth—only to risk it all on outdated or inadequate insurance coverage.

Here’s what to do next:

  • Review your current policies with a trusted agent
  • Assess your liability exposure, especially if you have multiple properties or vehicles
  • Ask about umbrella policies, higher deductibles, and tailored endorsements
  • Re-shop or review annually, especially if you live in a high-risk area

As Jacob Morgan put it, “Why would you go your whole life building wealth, only to lose it over a $500 insurance decision?”  Well said.

Ready to Protect What You’ve Built?

When it comes to high-net-worth insurance, working with the right expert makes all the difference. Jacob Morgan and his team specialize in protecting complex, high-value portfolios—from luxury homes and vehicles to vacation properties and beyond. Whether you’re reassessing your current coverage or building a more strategic risk management plan, Jacob can help ensure your insurance is aligned with your wealth.

Already working with us on your financial plan? Perfect. We’ll collaborate directly with Jacob to create a seamless, coordinated strategy that protects both your assets and your future.

📞 Contact Jacob Morgan at (719) 576-2638
📧 Email: [email protected]

Just mention this blog/podcast so he knows we sent you!

High Net Worth Financial Planning – What You Need to Know

High net worth financial planning is essential for preserving, growing, and strategically managing wealth. While having substantial assets may provide financial security, a well-structured financial plan ensures that your wealth aligns with your long-term goals, minimizes tax liabilities, and provides a clear roadmap for investments, estate planning, and risk management.

Many individuals with a high net worth question the need for financial planning because they aren’t worried about running out of money. However, as Brian discusses in The Field Guide podcast, a financial plan is more than just a tool —it is a blueprint for decision-making. It helps ensure that every financial move aligns with broader goals, whether it’s investments, taxes, estate planning, or philanthropy.

Even the wealthiest individuals benefit from a structured approach to their finances. In this guide, we break down why financial planning is essential for high net worth individuals and families, the key components of a strong financial plan, and how working with a fiduciary financial advisor can provide a roadmap to financial security and success.

Listen Now:

iTunes |  Spotify | iHeartRadio | Amazon Music

—–

Why Financial Planning Still Matters for Wealthy Individuals

Many assume that because they have substantial assets, they don’t need a financial plan. However, financial planning isn’t just for those worried about running out of money—it’s about making informed decisions, optimizing opportunities, and helping to ensure financial stability across generations.

Here’s why having a customized financial plan is crucial:

1. Ensuring Your Investments Align with Your Goals

A financial plan acts as a roadmap, helping you align your investments with your lifestyle, retirement, and legacy goals. Without a clear plan, it’s easy to make impulsive investment decisions that may not serve your long-term interests.

As Brian mentions, many clients approach him with specific investment ideas—such as buying Bitcoin or allocating more funds into tech stocks like Apple and NVIDIA, or other AI investments. However, without a plan, it’s impossible to determine whether these investments align with personal financial goals. Are you looking to grow wealth aggressively, or are you risk-averse and more focused on wealth preservation? These questions must be addressed before making investment decisions.

2. Managing Risk and Market Volatility

Even wealthy investors need to consider risk management. Market downturns, economic shifts, and unforeseen expenses can impact anyone. A solid financial plan ensures that you have diversified investments and strategies to mitigate risks.

In the podcast, Brian highlights how some investors chase trends without considering whether they can stomach the volatility. For example, Bitcoin may be a great long-term investment, but if a client is highly risk-averse and uncomfortable with large fluctuations in value, it may not be the right fit. A financial plan helps align investment choices with an individual’s risk tolerance and financial objectives.

3. Optimizing Tax Strategies

Those with substantial assets are often in higher tax brackets, making tax-efficient investing and estate planning essential. Without strategic tax planning, you could end up paying significantly more in taxes than necessary.

A good financial plan considers:

  • Which accounts to invest in for tax efficiency
  • When and how to withdraw funds to minimize tax liability.
  • Strategies for charitable giving to optimize deductions.

4. Legacy and Estate Planning 

Wealth preservation isn’t just about making money—it’s about ensuring your assets are passed down effectively. A well-structured estate plan as part of your larger financial plan ensures that your wealth is protected and allocated according to your wishes.

Many individuals fail to update their estate plans, leaving their heirs with unnecessary tax burdens or legal complications.

1,000 adults with over $3 million in investable assets were surveyed and found that only 48% of them had the three most basic planning documents in place: a will, a healthcare proxy and power of attorney. That is a shocking statistic. A financial plan helps you keep estate strategies up to date and aligned with your long-term vision.

5. Philanthropy and Charitable Giving

Many successful individuals want to leave a lasting impact through philanthropy. A financial plan helps structure tax-efficient charitable giving, maximizing the benefits for both you and your chosen causes.

Key Components of a Strong Financial Plan

To maximize and protect your wealth, your financial plan should include the following core components:

1. Investment Strategy & Asset Allocation

Investment planning goes beyond buying stocks and bonds—it’s about building a balanced portfolio tailored to your risk tolerance and financial objectives. Key strategies include:

  • Diversification: Spreading investments across various asset classes to minimize risk.
  • Alternative Investments: Private equity, hedge funds, and real estate can offer unique opportunities for wealth preservation and growth.
  • Tax-Efficient Investing: Using tax-advantaged accounts and strategies to reduce capital gains and income tax burdens.

2. Tax Optimization Strategies

Minimizing tax liabilities is one of the most valuable aspects of financial planning. Strategies include:

  • Tax-Loss Harvesting: Offsetting gains with losses to reduce taxable income.
  • Roth IRA Conversions: Managing income tax liabilities through strategic conversions.
  • Trusts & Charitable Giving: Using donor-advised funds or charitable remainder trusts to reduce tax exposure while fulfilling philanthropic goals.

3. Estate Planning & Wealth Transfer

Estate planning ensures that your assets are passed down efficiently. Key tools include:

  • Revocable & Irrevocable Trusts: Protecting assets from estate taxes and ensuring privacy.
  • Gifting Strategies: Annual gift tax exclusions and family limited partnerships to pass wealth tax-efficiently.
  • Business Succession Planning: If you own a business, structuring a succession plan is critical for maintaining generational wealth.

4. Risk Management & Insurance Planning

Risk management is a crucial component of high net worth financial planning. It ensures that your assets, income, and estate are protected against unforeseen circumstances such as market volatility, lawsuits, health crises, and other financial risks. A well-structured risk management strategy should include the following elements:

  • Asset Protection Strategies: Legal structures such as LLCs and asset protection trusts.
  • Life Insurance Planning: Using permanent life insurance as a tool for estate liquidity and wealth transfer.
  • Long-Term Care & Disability Planning: Ensuring you have adequate coverage in case of unforeseen health issues.

Common Mistakes High Net Worth Individuals Make Without a Financial Plan

Even those with substantial wealth can face financial pitfalls without a well-structured financial plan. Some of the most common mistakes high-net-worth individuals make include:

  • Lack of Investment Strategy: Without a clear investment strategy, individuals may take on excessive risk or miss out on key diversification opportunities. Over-concentration in certain stocks, industries, or asset classes can lead to significant financial losses.
  • Overlooking Tax Efficiency: Many wealthy individuals fail to take advantage of tax-efficient strategies, resulting in unnecessary tax burdens. Without proper planning, they may miss out on deductions, tax-deferred growth opportunities, and estate tax reduction strategies.
  • Neglecting Estate Planning: Failing to have a well-structured estate plan can lead to disputes, excessive estate taxes, and assets not being distributed as intended. A lack of trusts or beneficiary designations can create unintended complications for heirs.
  • Ignoring Risk Management: Wealthy individuals often underestimate risks such as lawsuits, asset protection, and long-term care expenses. Without proper insurance coverage or legal structures, their wealth could be vulnerable to unexpected claims or liabilities.
  • Spending Without a Long-Term Plan: A high income or large net worth does not guarantee financial security if spending habits are unchecked. Without a financial plan, individuals may deplete their wealth faster than expected, jeopardizing long-term goals like legacy planning or philanthropy.
  • Failing to Adapt to Market Changes: Financial markets fluctuate, and tax laws evolve. Without an ongoing financial strategy, individuals may miss opportunities to adjust their portfolios, capitalize on new tax incentives, or navigate economic downturns effectively.
  • Not Working with a Fiduciary Advisor: Many high net worth individuals rely on financial advice from brokers or advisors who may have conflicts of interest. Without a fiduciary advisor, they may receive guidance that prioritizes commissions over their best interests.
    A comprehensive financial plan helps mitigate these risks and ensures that high-net-worth individuals make informed strategic financial decisions. Working with an experienced financial planning team can help preserve wealth, reduce liabilities, and provide peace of mind for the future.

Final Thoughts

Financial planning is essential regardless of wealth level. A structured approach to investment strategy, risk management, tax optimization, and estate planning provides clarity, direction, and the ability to make informed financial decisions that align with long-term goals. Having a financial plan in place not only protects your assets but also allows you to take advantage of opportunities that align with your lifestyle and values.

By regularly reviewing and adjusting your financial plan, you can ensure that it remains relevant as your goals evolve and as financial markets shift. The right high net worth financial planning strategy allows you to build a legacy, protect your family’s future, and make confident financial decisions without unnecessary stress.

Next Steps- Get a Plan

If you’re looking for expert guidance tailored to your financial needs, our team at Bonfire Financial specializes in fiduciary, planning-based strategies designed to optimize your wealth. Contact us today to start building a financial plan that works for you.

Turning High Income into Lasting Wealth: Proven Strategies for High Earners

Strategies for High Earners

Earning a high income is an incredible advantage, but it doesn’t automatically mean you’re building real wealth. Many high earners, whether doctors, business owners, pilots, executives, or professionals, find themselves living an expensive lifestyle without accumulating enough assets to sustain it long-term. Without a strategy, even a seven-figure salary can disappear quickly.

If you’re making $400K, $600K, or even more annually, the key question isn’t how much you make, but what you do with it. This article explores strategies for high earners to maximize their income, build long-term wealth, and avoid financial pitfalls.

Listen Now:

iTunes |  Spotify | iHeartRadio | Amazon Music

—–

1. Automate Your Savings and Investments

One of the most effective strategies for high earners is automating savings. When money flows into your bank account, it’s easy to spend more than you intend. Automating your savings ensures you consistently put money aside before you even have the chance to spend it.

  • Max Out Your Retirement Accounts: Contribute the maximum allowable amount to your 401(k), IRA, or Roth IRA (if applicable). If you own a business, consider a SEP-IRA or Solo 401(k).
  • Set Up Automatic Transfers to Brokerage Accounts: High earners often hit retirement contribution limits quickly. A taxable brokerage account allows you to invest beyond those limits.
  • Leverage High-Yield Savings for Short-Term Goals: Automate transfers into high-yield savings accounts for planned expenses like vacations, home renovations, or large purchases.

By setting up these transfers to occur automatically, you remove the temptation to spend your entire paycheck and ensure consistent wealth accumulation.

2. Avoid Lifestyle Creep

A common trap for high earners is lifestyle inflation—the tendency to spend more as income increases. It’s easy to justify upgrading homes, cars, and vacations when your paycheck allows for it, but this can leave you with little to show for years of high earnings.

To combat lifestyle creep:

  • Define Your Wealth Goals: What does long-term financial success look like for you? Owning investment properties? Retiring early? Creating a passive income stream?
  • Keep Fixed Expenses in Check: Just because you can afford a bigger mortgage doesn’t mean you should take one. Be mindful of recurring costs like luxury car leases, club memberships, and high-end subscriptions.
  • Invest in Assets, Not Just Status Symbols: A $100,000 car loses value over time. A well-chosen $100,000 investment property generates income and appreciates in value.
    Maintaining a balanced approach to spending allows you to enjoy your wealth while securing your future.

3. Build Multiple Income Streams

Even high earners benefit from diversifying their income sources. Relying solely on a paycheck—even a large one—can leave you financially exposed if your industry changes or your role is impacted.

Consider these income streams:

  • Real Estate Investments: Rental properties provide consistent cash flow and potential appreciation.
  • Private Investments: Opportunities like private equity, venture capital, and angel investing can offer high returns, though they come with risk.
  • Side Businesses: Many professionals create consulting businesses, online courses, or digital products to diversify income.
  • Dividend Stocks and Bonds: A well-structured investment portfolio, specifically with dividend stocks,  generates passive income over time.

Building multiple income streams ensures financial stability and accelerates wealth accumulation.

4. Minimize Taxes Strategically

Taxes can significantly impact your ability to grow wealth. High earners must be proactive about tax planning to retain more of their income.

Key tax strategies for high earners:

  • Maximize Tax-Advantaged Accounts: Contribute to 401(k)s, HSAs, and Roth Conversions where possible.
  • Utilize Tax-Efficient Investments: Invest in municipal bonds, tax-efficient index funds, and real estate with depreciation benefits.
  • Take Advantage of Business Deductions: If you own a business, structure it to maximize deductions and reduce taxable income.
  • Work with a Tax Professional: A tax strategist can help identify deductions, credits, and investment structures that minimize your liability.

By implementing tax-efficient strategies, you can keep more of your earnings working for you.

5. Invest with a Long-Term Mindset

High earners sometimes fall into the trap of chasing quick returns or risky investments. A disciplined, long-term approach to investing is far more effective.

  • Diversify Your Portfolio: Don’t put all your wealth into a single stock, business, or asset class. Diversification is wildly important here.
  • Rebalance Regularly: Adjust your portfolio as market conditions change and your goals evolve.
  • Stay the Course: Market volatility is inevitable, but a long-term strategy yields strong results over time.
  • Invest in What You Understand: Avoid speculative investments unless you have deep knowledge of the space.

A well-structured investment strategy ensures your wealth grows steadily and sustainably.

6. Protect Your Assets and Plan for the Future

Earning and investing wisely is just part of the equation—protecting your wealth is equally important. Many high earners overlook estate planning, asset protection, and risk management.

  • Have Proper Insurance: Ensure you have adequate life, disability, and umbrella liability insurance.
  • Create an Estate Plan: Establishing a will, trusts, and power of attorney documents is crucial for protecting your assets and ensuring your wishes are carried out. Proper estate planning helps safeguard your wealth for future generations and provides clarity in managing your financial affairs.
  • Consider Asset Protection Strategies: High earners can be targets for lawsuits—proper legal structures (LLCs, trusts) can shield assets from unnecessary risk.

Planning for the future ensures that your wealth is preserved and passed on according to your wishes.

The Bottom Line:

Earning a high income is an incredible opportunity, but without a plan, it’s easy to end up with little to show for it. By automating savings, avoiding lifestyle creep, diversifying income, minimizing taxes, and investing wisely, you can turn your earnings into lasting wealth.

The key is consistency and discipline. Small, intentional decisions over time lead to big financial outcomes.

If you’re ready to take control of your finances and build real wealth, start implementing these strategies today. And if you’d like expert guidance in setting up a wealth plan tailored to your income and goals, reach out to us today and get the conversation started.

Thank You For Your Subscription

You’re in! Thanks for subscribing to our monthly newsletter. We will be sending you market updates, financial insights and inspiring travel ideas soon but in the meantime check out our blog, join us on Instagram or pop over to Pinterest.

Your Appointment Request has been Received

Thank you for reaching out! We are excited to learn more about you. Someone from our team will be in touch shortly.

Sign up now

Join us around the fire for monthly market updates, financial insights and inspiring travel ideas.

.

Sign up now

Receive tips

Give us a call

(719) 394.3900
(844) 295.0069