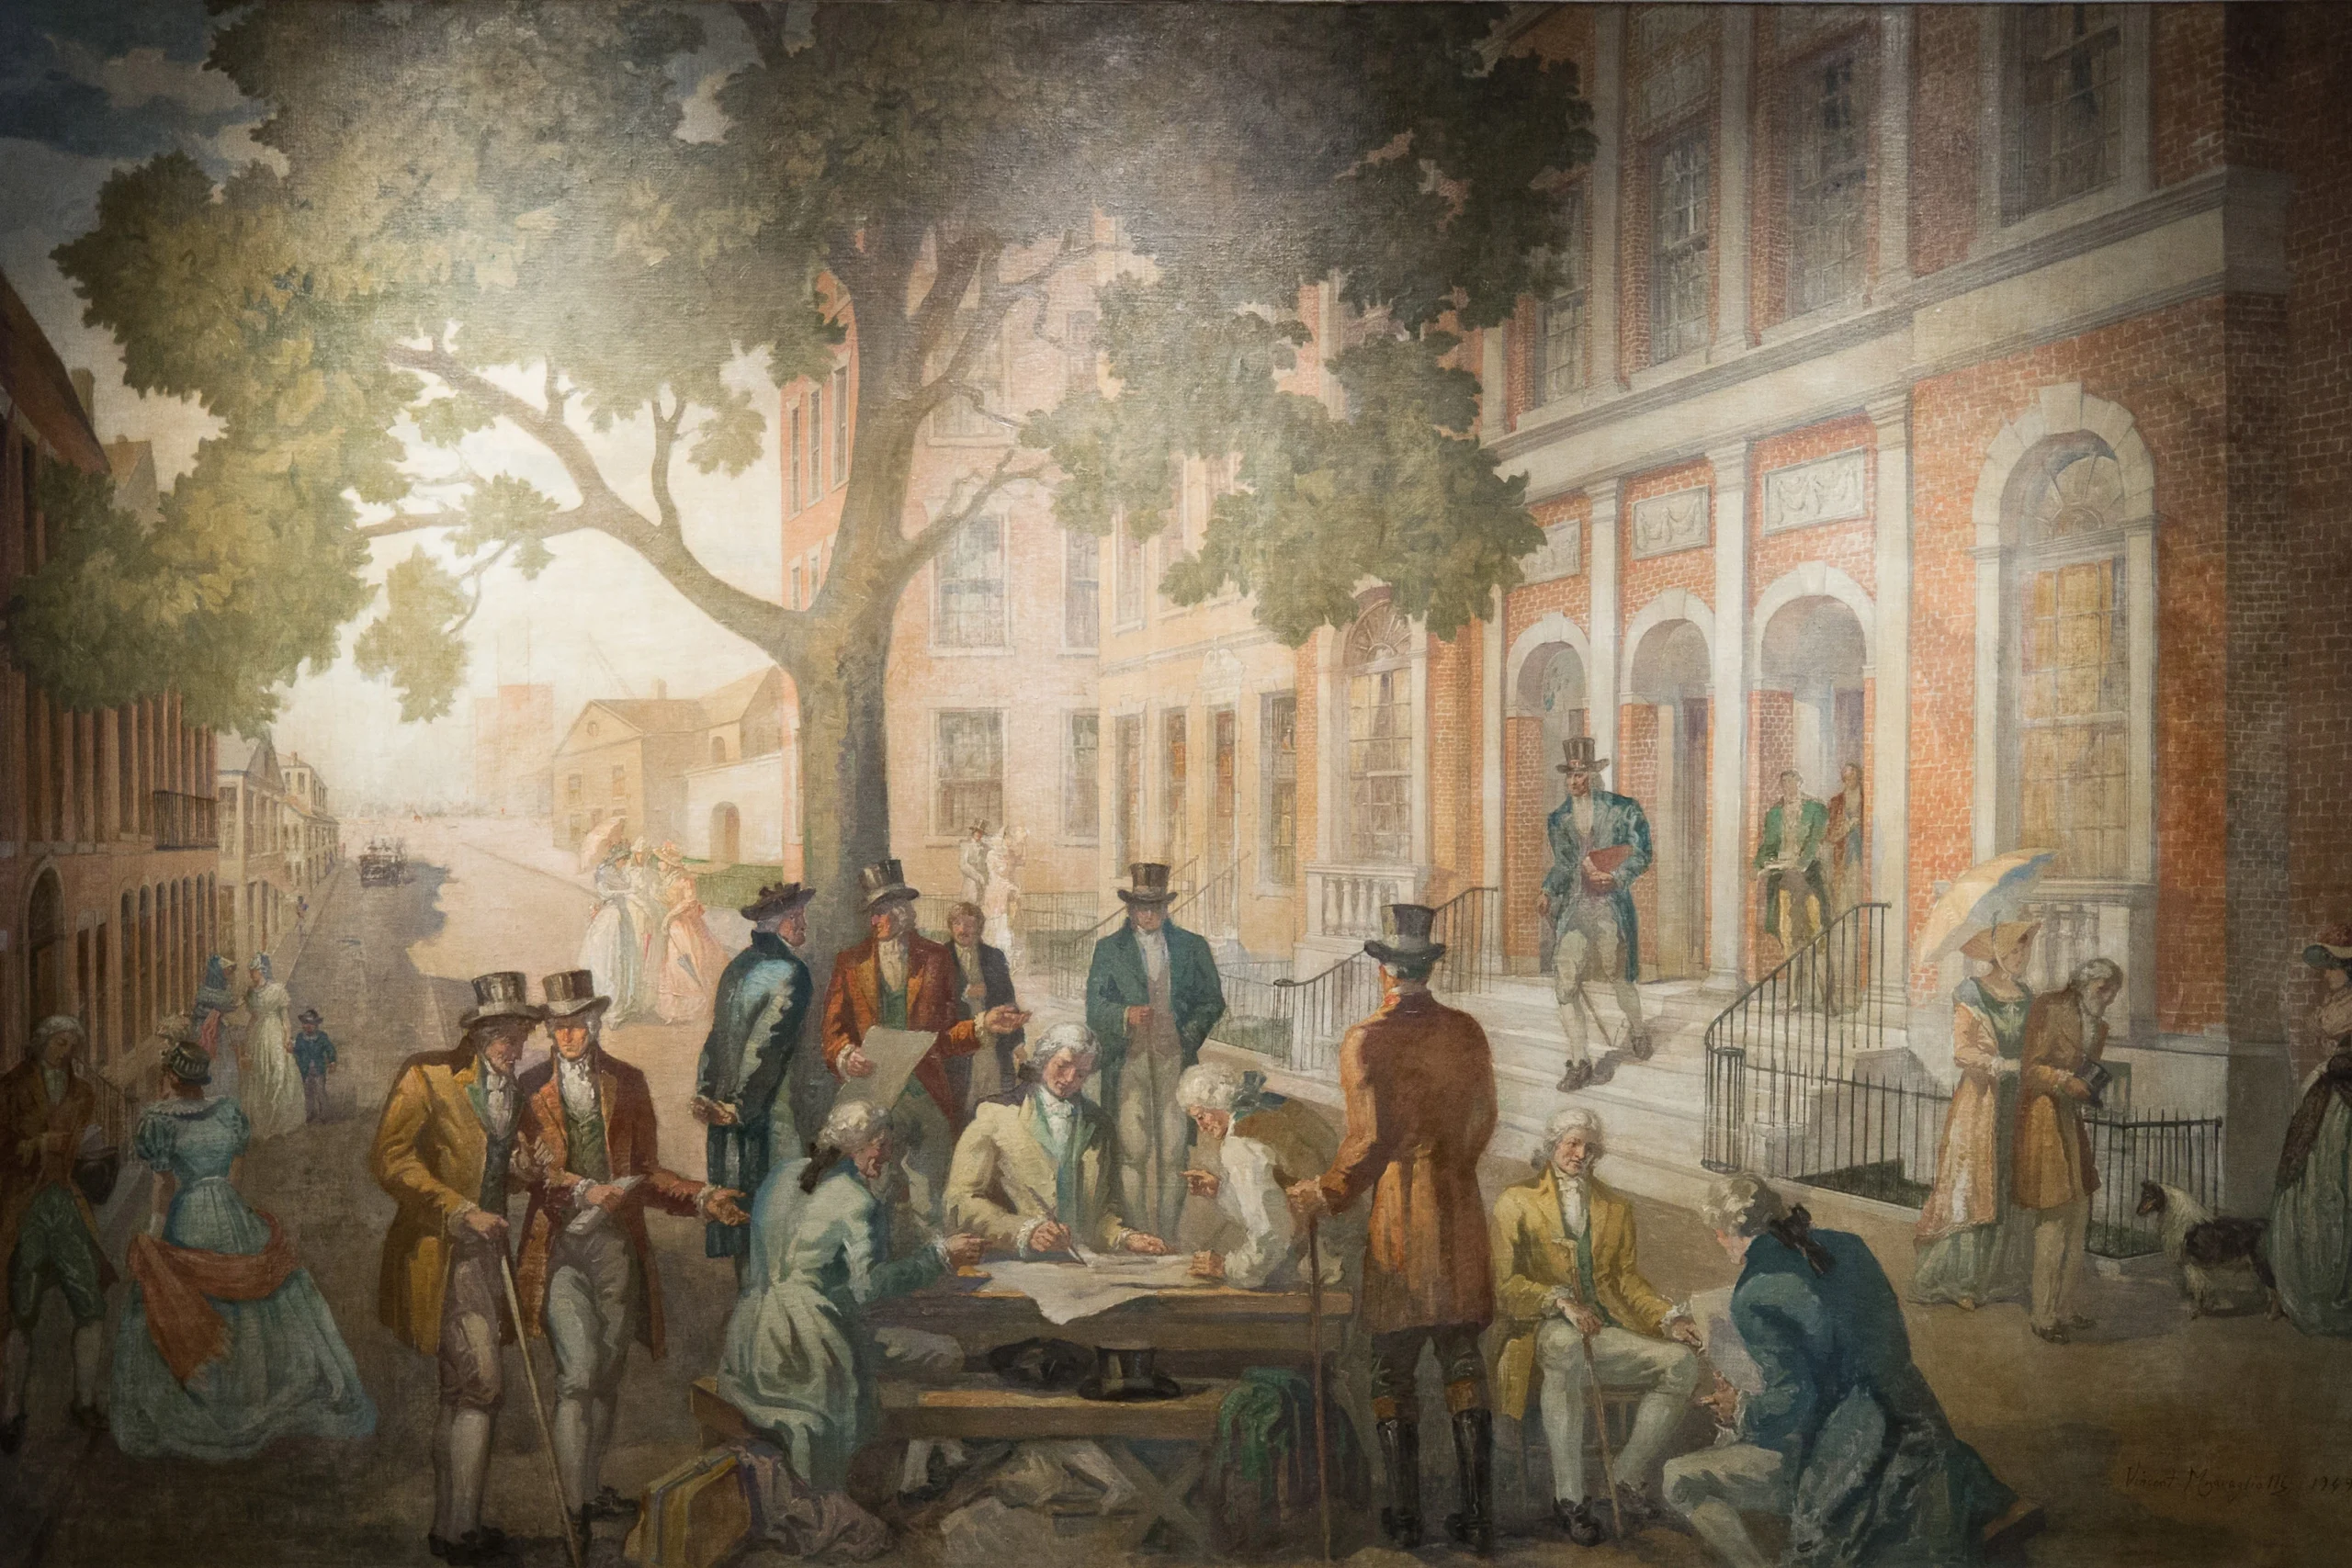Alternatives: Why Exclusive Doesn’t Always Mean Better
There’s a point when accumulating wealth changes the investment opportunities available to you.
Suddenly, financial firms begin offering private equity, hedge funds, private credit, and real estate deals. These exclusive investments promise access to opportunities beyond traditional stocks and bonds.
The pitch sounds compelling. Wealthy investors get access to sophisticated strategies, potentially higher returns, and opportunities unavailable to the average person.
But does investing in alternatives actually lead to better results?
Not necessarily.
Some alternative investments have delivered exceptional returns. Others have struggled to outperform simple, low-cost index funds, particularly after accounting for fees.
>> Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video. <<
What Are Alternative Investments?
Alternative investments include assets and strategies outside traditional publicly traded stocks, bonds, and cash.
Despite their sophisticated reputation, most alternatives serve familiar purposes. They allow you to own an asset, lend money, or pursue a strategy that differs from conventional investing.
Common examples include:
Private equity: Ownership in companies that don’t trade on public stock exchanges.
Venture capital: Investments in startups and early-stage businesses with significant growth potential.
Private credit: Loans made directly to businesses outside traditional public bond markets.
Private real estate: Ownership in properties through private investment partnerships or funds.
Hedge funds: Investment vehicles that may use strategies such as short selling, leverage, or derivatives.
These investments aren’t inherently better or worse than traditional options.
The difference often comes down to how managers structure the investment, calculate its value, charge fees, and restrict withdrawals.
Those details matter more than the label.
Why Do Wealthy Investors Choose Alternatives?
Exclusivity plays a powerful role in investing.
Many private investment opportunities require investors to meet specific income, net worth, or professional qualifications. Once you qualify, you may receive invitations to opportunities that previously seemed out of reach.
That access can feel like a reward for building wealth.
But qualifying for an investment doesn’t automatically make it a good investment.
Consider a conversation at a barbecue or golf course. Someone casually mentions earning 20% on a private investment.
Impressive, right?
Maybe. But several important details often go unmentioned.
Was that return earned over one year or several? Did the investor account for management fees? How did the investment perform compared with the S&P 500? Most importantly, could the investor actually withdraw the money?
Stories about impressive returns travel quickly. Conversations about disappointing performance, expensive fees, and restricted access to cash rarely receive the same attention.
That imbalance can make alternative investments appear more attractive than they really are.
The Yale Endowment: Why Investing Like the Wealthy Doesn’t Always Work
Much of the fascination with alternative investments traces back to Yale University.
In 1985, David Swensen began managing Yale’s endowment. He eventually shifted substantial portions of its portfolio toward private equity, venture capital, real estate, and other nontraditional investments.
For years, the approach produced remarkable results.
Institutional investors took notice. Investment firms followed, and wealthy individuals eventually began seeking similar strategies.
The reasoning seemed simple. If Yale could generate exceptional returns with alternatives, why couldn’t individual investors do the same?
There’s one significant problem with that assumption.
Yale’s investment needs look nothing like yours.
The university manages an endowment intended to last indefinitely. It can commit capital for decades and has access to investment managers that many individuals cannot reach.
Your financial life operates on a different timeline.
You may need money for retirement, a home purchase, family expenses, or unexpected events. Even if you have substantial wealth, access to that money still matters.
An investment strategy that works for a perpetual endowment may not serve someone funding the next 20 or 30 years of retirement.
Copying Yale’s investment categories doesn’t guarantee access to the same managers, opportunities, or returns.
Alternative Investments vs. Index Funds: Which Performs Better?
Alternative investments often attract attention because of their potential to outperform public markets.
But how have they actually performed?
Private Equity
Private equity has historically delivered strong returns during certain periods. Some funds have significantly outperformed publicly traded investments.
However, performance varies substantially across managers and investment periods.
In the periods examined for this discussion, broad private equity returns were roughly comparable to public markets over a longer horizon. More recently, public stocks held a meaningful advantage.
Investors also face an important challenge: Access to private equity doesn’t guarantee access to the best-performing funds.
Venture Capital
Venture capital offers the possibility of investing in the next transformative company before it becomes publicly traded.
The potential upside can be enormous.
Unfortunately, a relatively small number of successful investments often account for a disproportionate share of overall venture capital returns.
Many startups never become profitable, and unsuccessful investments can result in substantial losses.
Manager selection plays a critical role, while access to top-performing venture funds may remain limited.
Hedge Funds
Hedge funds provide another useful comparison.
In 2008, Warren Buffett entered a famous 10-year wager that a low-cost S&P 500 index fund would outperform a group of hedge funds.
During the financial crisis, the hedge funds initially held up better.
Over the full decade, however, the index fund won by a substantial margin.
One major reason was fees.
Hedge fund investors often pay several layers of investment management costs. Those expenses create a significant hurdle before investors receive their returns.
The lesson isn’t that every hedge fund or private investment performs poorly.
It’s that complexity and higher fees don’t guarantee superior performance.
A low-cost index fund can remain a formidable competitor, even against highly sophisticated investment strategies.
The Hidden Risks of Alternative Investments
Performance only tells part of the story.
Alternative investments often introduce risks that investors may not immediately recognize.
1. Lower Volatility Doesn’t Always Mean Lower Risk
Traditional stocks and index funds receive updated market prices throughout the trading day.
Private investments operate differently.
A private equity fund might estimate the value of its holdings quarterly rather than continuously.
As a result, the investment may appear relatively stable on your financial statement, even when broader markets experience significant volatility.
Cliff Asness, co-founder of AQR Capital Management, has described this phenomenon as volatility laundering.
The concept is straightforward: Infrequent valuations can make investment performance appear smoother than the underlying economic risk suggests.
A less volatile statement doesn’t necessarily indicate a safer investment.
Sometimes, it simply reflects a different method of measuring value.
2. Your Money May Be Locked Up for Years
Liquidity refers to how quickly you can convert an investment into cash.
With a traditional index fund, you can generally sell shares during market trading hours.
Private investments may impose considerably more restrictions.
Some require multiyear commitments. Others allow withdrawals only during specified periods or limit how much investors can redeem.
These restrictions can serve legitimate purposes.
A real estate fund, for example, may need to prevent investors from forcing rapid property sales during unfavorable market conditions.
Still, what protects the fund can create problems for the individual investor.
If you need money during retirement, an investment you cannot easily sell may offer little practical value.
3. Higher Fees Can Reduce Your Returns
Alternative investments frequently charge multiple layers of fees.
Depending on the structure, investors may pay management fees, performance-based compensation, administrative expenses, and additional costs.
Each expense reduces the money available to compound over time.
Consider a hypothetical $1 million investment with annual expenses of 2.5%.
That’s $25,000 in fees every year, assuming the same investment value.
A low-cost index fund might charge only a few hundred dollars on an equivalent balance.
The alternative investment must generate enough additional value to justify that difference.
And remember, fees don’t disappear when performance disappoints.
Investment returns fluctuate. Many ongoing expenses remain.
When Do Alternative Investments Make Sense?
Despite these concerns, alternative investments can serve a legitimate purpose.
Certain strategies offer access to different sources of return, specialized income opportunities, or investments unavailable through public markets.
The important question isn’t whether an investment sounds sophisticated.
It’s whether it improves your overall financial strategy.
Before investing in alternatives, consider four questions.
1. What does this investment provide that I can’t get elsewhere?
An alternative should offer a meaningful benefit compared with cheaper, simpler, and more liquid investments.
2. What specific purpose will it serve?
Does the investment create income, provide diversification, or offer a different source of potential growth?
3. Are the expected benefits worth the fees?
Evaluate all expenses, including management fees, performance compensation, and other fund costs.
4. Do I understand the investment and its risks?
Know what you own, how the manager determines its value, what could cause losses, and when you can access your money.
If an investment cannot pass these tests, exclusivity alone isn’t a reason to purchase it.
Where Do Alternatives Fit in a Retirement Portfolio?
Retirement planning adds another consideration to investing in alternatives.
The purpose and timing of your money matter just as much as potential returns.
At Bonfire Financial, we think about investment needs through three broad time horizons.
Money Needed Within Two Years
This money should prioritize stability and accessibility.
Near-term living expenses, planned purchases, and emergency reserves shouldn’t depend on investments that restrict withdrawals.
Money Needed in Three to Seven Years
These assets have more time to grow, but they still require an appropriate balance between risk and accessibility.
Investments with extended lockups may not align with these needs.
Money Needed in Eight Years or Longer
Longer-term investments have greater flexibility.
For investors with adequate liquidity and a specific investment objective, this portion of the portfolio may provide room for carefully selected alternatives.
Even then, alternatives should generally support the overall strategy rather than become its foundation.
For many investors, a diversified portfolio of traditional, low-cost investments may already provide everything they need.
Are Alternative Investments Worth It?
The appeal of alternative investments is understandable.
They offer access to exclusive opportunities, sophisticated strategies, and the possibility of attractive returns.
But investing isn’t about proving how sophisticated your portfolio can become.
It’s about making your money work toward your goals.
For many investors, the right allocation to alternatives may be zero.
Others may benefit from a modest allocation when they have sufficient liquidity, a long investment horizon, and a clear reason to accept additional complexity.
Neither approach should depend on exclusivity or status.
As your wealth grows, you’ll likely encounter more investment opportunities. That doesn’t mean every new opportunity deserves a place in your portfolio.
Sometimes, the simplest investments remain the most effective.
And if added complexity can’t demonstrate its value, boring wins.
Make Your Investments Work for Your Retirement
A more complicated portfolio doesn’t always mean a better retirement. What matters is having an investment strategy that supports the life you want to live.
The Bonfire Method brings your investments, taxes, income, and retirement goals together into one coordinated strategy.
4 meetings. 30 days. One complete retirement strategy.
What a Fiduciary Really Means for Your Financial Advice
Today, you can buy a stock from your phone in seconds.
No broker. No phone call. No paper certificate. In many cases, no trading commission.
That sounds normal now. For most of Wall Street’s history, it would have been unthinkable.
There was a time when buying a stock required calling a stockbroker, who contacted someone on a trading floor to execute the transaction. The broker controlled access to the market. That access was valuable, and Wall Street built an enormous industry around selling it.
Then technology made access nearly free.
The stockbroker should have disappeared with it.
Instead, something more interesting happened.
The title changed.
Stockbrokers became financial consultants. Financial consultants became financial advisors. Today, millions of investors assume the person sitting across from them is there primarily to provide advice.
But the history of the financial industry created an important distinction that still exists today: financial advisor vs. fiduciary.
Understanding that difference may tell you more about your advisor than the title printed on a business card ever will.
>> Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video. <<
It Started Under a Tree
The story goes back to May 17, 1792. Twenty-four stockbrokers gathered under a buttonwood tree near Wall Street and signed what became known as the Buttonwood Agreement.
It contained two basic promises. The brokers agreed to charge a minimum commission, and they agreed to give preference to one another when conducting business.
That agreement helped lay the foundation for what eventually became the New York Stock Exchange.
More importantly, it established the basic economics of the brokerage business.
Brokers got paid when transactions happened. No transaction meant no commission.
For generations, that model made sense because investors couldn’t easily access financial markets without a broker.
Then everything started to change.
When Advice Became a Different Business
The stock market crash of 1929 ushered in a new era of financial regulation.
Congress passed the Securities Act of 1933 and the Securities Exchange Act of 1934. Then, in 1940, lawmakers passed the Investment Advisers Act.
That law helped establish a distinction that still matters today.
A broker facilitates transactions.
An investment adviser provides advice.
Those roles can come with different responsibilities to the client.
The concept of a fiduciary sits at the center of that distinction.
A fiduciary has a duty to put the client’s interests ahead of their own. That sounds like an obvious requirement for anyone giving financial advice, but the financial industry did not develop around a single standard.
Instead, two models grew alongside each other.
One focused on selling financial products and completing transactions.
The other focused on providing ongoing advice under a fiduciary standard.
From the outside, those professionals could look remarkably similar.
Same office.
Same suit.
Same industry.
Very different obligations.
Wall Street Saw the Conflict Early
Even some of Wall Street’s biggest names recognized the tension between advice and commissions.
Charles Merrill, one of the founders of Merrill Lynch, famously put brokers on salary rather than paying them based entirely on transactions.
The idea was simple.
If someone’s compensation increases every time a client trades, compensation can influence the advice that person gives.
Removing the transaction incentive could reduce that conflict. The model didn’t become the industry’s permanent standard.
Commission-based brokerage remained a powerful part of Wall Street for decades.
Then the economics underneath it began to collapse.
The Product Wall Street Sold Became Cheaper
For much of Wall Street’s history, brokers weren’t simply giving investors ideas.
They provided access.
By the late 20th century, technology started tearing down that barrier.
Stock quotes went electronic.
Index funds made broad market investing accessible.
Personal computers brought trading into homes.
Online brokerage accounts followed.
Then came one of the biggest blows to the traditional brokerage model.
In October 2019, Charles Schwab eliminated commissions on online stock and ETF trades. Major competitors quickly followed.
An activity that once supported an entire industry suddenly cost investors essentially nothing.
Think about what that meant.
For generations, Wall Street charged investors to execute trades.
Now investors could do it themselves from their phones.
When your core product becomes free, you need a new reason for clients to pay you.
That reason became advice.
The Stockbroker Didn’t Disappear. The Title Changed.
The language gradually shifted.
Stockbroker became financial consultant.
Financial consultant became financial advisor.
The new title sounded different because the service had changed. Investors increasingly wanted planning, guidance, tax strategy, retirement income advice, and help making decisions.
But the old brokerage model didn’t simply vanish.
Instead, the lines between brokerage and advice became harder for consumers to see.
That’s where the financial advisor vs. fiduciary conversation gets complicated.
Many financial professionals today hold more than one type of registration.
They may operate as an investment adviser in one situation and as a broker in another.
That means someone can provide fiduciary advice in certain parts of a relationship while also holding a brokerage registration that operates under a different regulatory framework, and get paid differently too.
The person sitting across from you may still carry the title “financial advisor” in both situations. That’s why the title alone tells you very little.
What Does Fiduciary Actually Mean?
A fiduciary financial advisor has a responsibility to put your interests ahead of their own when acting in a fiduciary capacity.
That distinction matters because financial recommendations can affect more than investment performance.
Consider the decisions investors make as they approach retirement:
Which accounts should you withdraw from first?
When should you claim Social Security?
Should you convert traditional retirement assets to Roth?
How should investment decisions coordinate with taxes?
Does an insurance product solve an actual planning need?
How should your estate plan fit with everything else?
These decisions rarely exist in isolation.
A true fiduciary relationship should begin with your financial life, not with a product someone wants to sell.
Why “Are You a Fiduciary?” May Not Be Enough
Here’s where things get tricky.
Ask a financial professional, “Are you a fiduciary?” and many can truthfully answer yes.
That doesn’t necessarily tell you whether they act as a fiduciary 100% of the time.
A dually registered professional may operate under a fiduciary standard in some circumstances while also maintaining a brokerage registration.
So the better question is more specific:
“Are you a fiduciary to me 100% of the time, in writing, without another registration that allows you to operate under a different standard?”
The answer should be easy to understand.
You shouldn’t need a law degree to figure out the relationship you’re entering.
Financial Advisor vs. Fiduciary: How to Check for Yourself
You don’t have to rely entirely on what an advisor tells you.
Financial professionals and advisory firms make regulatory disclosures available to the public.
Two documents can be particularly helpful.
Form ADV
Registered investment advisers file Form ADV.
It includes information about the firm’s business, services, fees, conflicts of interest, disciplinary history, and other important details.
Form CRS
Financial advisors and brokers may also provide Form CRS, short for Client Relationship Summary.
This document helps explain how the firm operates, what services it provides, how it gets paid, and potential conflicts.
Before hiring someone, read these documents. Look at how they receive compensation.
Check whether the person maintains a brokerage registration.
Then ask questions about anything you don’t understand.
Transparency shouldn’t require detective work.
Do You Even Need a Financial Advisor?
Not everyone does.
If you can build a diversified portfolio, stay invested through difficult markets, avoid chasing performance, coordinate your tax strategy, manage retirement withdrawals, and make major financial decisions without emotional interference, managing your money yourself may make sense.
You may also save a meaningful amount in advisory fees.
For everyone else, the question becomes whether professional advice delivers enough value to justify its cost.
A typical advisory fee around 1% can add up over time.
That means an advisor needs to provide value beyond simply choosing investments.
Good financial advice may include:
Tax planning
Retirement income strategy
Investment management
Behavioral coaching
Social Security planning
Risk management
Estate planning coordination
Withdrawal strategy
Helping you make decisions when markets get difficult
An advisor shouldn’t exist simply because investing feels complicated. The relationship should make your overall financial life better.
Why Fiduciary Advice Matters More Today
Ironically, investing has never been easier.
You can build a diversified portfolio for very little money, and use AI to help run numbers. Financial information is everywhere. Trading costs have fallen dramatically.
The harder part now is making all the pieces work together.
Investments affect taxes.
Taxes affect retirement income.
Retirement income affects Medicare premiums.
Estate decisions affect heirs.
Emotions affect nearly everything.
Modern financial advice should help coordinate those decisions. That’s also why understanding whether your advisor acts as a fiduciary matters.
You’re no longer paying someone simply to get you into the market.
You’re paying for judgment.
And when you’re paying someone for judgment, you should know whose interests come first.
The Stockbroker Evolved. Your Questions Should Too.
The financial industry has changed dramatically since 24 brokers met under a tree in 1792.
Paper certificates disappeared.
Trading floors became less important.
Commissions fell.
Technology gave individual investors access Wall Street once controlled.
Yet one question has survived every version of the industry:
Who does the person giving you financial advice ultimately work for?
The title on the business card won’t answer it.
“Financial advisor” can describe professionals working under very different business models.
Understanding the difference between a financial advisor and a fiduciary helps you look beyond the title and understand the relationship you’re actually entering.
Before you hand someone responsibility for decades of savings, ask how they’re registered, how they’re compensated, where conflicts could exist, and whether they will act as your fiduciary at all times.
You spent a lifetime building your wealth.
The advice you receive about it should put you first.
A Different Approach to Financial Advice
At Bonfire Financial, we believe financial advice should start with your complete financial life, not a product.
We operate as a fiduciary because we believe your interests should come first throughout the relationship.
Through the Bonfire Method, we bring investments, taxes, retirement income, insurance, and estate planning together into one coordinated strategy so you can see how each decision affects the rest. If you’re approaching retirement and want to understand whether all the pieces of your financial life are working together, learn more about the Bonfire Method.
New Financial Advisor? What to Ask Before You Stay
If your financial advisor is retiring, you may assume the person taking over your accounts is the natural choice to continue managing your money. That may be true, but it is worth taking the time to find out.
A new financial advisor can have a very different investment philosophy, fee structure, planning process, or approach to retirement than the advisor you have worked with for years.
That matters even more when you are approaching or already in retirement.
Before agreeing to continue the relationship, ask these eight questions to understand exactly who will be managing your money and whether they are the right fit for the years ahead.
Even if your advisor isn’t retiring now this may still be worth a read as according to J.D. Power’s 2025 Financial Advisor Satisfaction Study, 46% of financial advisors surveyed plan to retire within the next 10 years, highlighting how many investors could soon find themselves working with a new financial advisor.
Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.
Why You Should Evaluate a New Financial Advisor
Advisor succession is becoming an increasingly important issue for investors. When an established advisor retires, clients may be transitioned to someone younger or to another advisor within the firm.
That transition does not necessarily mean the new advisor was selected specifically because they are the best match for you.
Financial advisory practices also have economic value. In some situations, another advisor may purchase all or part of a retiring advisor’s business. As a result, the person who takes over your accounts could have different investment strategies, services, fees, or planning philosophies.
Your retirement savings are too important to simply assume everything will remain the same.
Treat the transition as an opportunity to interview your new financial advisor and decide whether you would choose that person yourself.
1. Are You a Fiduciary at All Times?
Start with one of the most important questions you can ask a financial advisor:
Are you a fiduciary at all times?
A fiduciary is required to provide advice that is in your best interest. Understanding when and how that obligation applies can help you identify potential conflicts of interest. Some financial professionals operate under different standards depending on the account or service they are providing. That distinction may not be obvious to the client.
Ask your new financial advisor to explain their fiduciary responsibility clearly, including whether it applies to every account they manage for you.
You should understand how they are compensated as well.
Commissions, product incentives, and other forms of compensation can affect the economics of certain recommendations. Knowing how your advisor gets paid gives you additional context when evaluating their advice.
2. What Is My Total Cost in Year One?
An advisory fee is only one piece of the cost of managing an investment portfolio.
For example, an advisor may charge a percentage of the assets they manage. Additional expenses could potentially include investment costs, transaction expenses, product fees, or other charges.
Ask your new financial advisor for the total estimated cost of the relationship, not simply the headline advisory fee.
Questions may include:
What percentage am I paying for investment management?
Are there additional account or trading costs?
Do any of my investments carry separate fees?
Are commissions involved?
Have any fees changed since my previous advisor managed the account?
No advisor should be expected to work for free. The goal is simply to understand what you are paying and what you are receiving in return.
Fees that appear small on an annual basis can become meaningful over a long retirement.
3. Can I See an Example Financial Plan?
Investment management and financial planning are not the same thing.
A portfolio of stocks and bonds may be an important part of retirement planning, but retirees often face decisions that extend well beyond asset allocation.
Ask your new financial advisor if you can see a redacted example of a financial plan. The example can help you determine how deeply the advisor approaches retirement planning.
A comprehensive process may consider areas such as:
Social Security
Healthcare expenses
Tax planning
Roth conversions
Required minimum distributions
Withdrawal strategies
HSA planning
Estate planning
Investment management
Seeing the actual planning process can tell you much more than hearing someone say they provide “holistic financial planning.”
You want to know whether your advisor is building a retirement strategy or primarily managing investments.
4. How Do You Plan for the Years Between Retirement and RMDs?
The years immediately after retirement can present valuable planning opportunities.
For many retirees, there is a period between leaving the workforce and beginning required minimum distributions. Income may temporarily be lower during those years.
That window can create opportunities to evaluate strategies such as Roth conversions and other tax-planning decisions.
Ask your new financial advisor how they specifically approach those years. More importantly, find out what causes them to recommend action.
Do they have specific triggers they monitor? Will they review the opportunity every year? How do taxes factor into the decision?
A strong retirement planning process should not rely on making these decisions at the last minute.
Your advisor should have a system for evaluating opportunities as your retirement evolves.
5. How Often Will We Meet?
Communication expectations should be established before you commit to a new advisory relationship. Ask how often the advisor typically meets with retirement clients.
Some advisors schedule annual meetings. Others may meet semiannually or quarterly depending on the client’s needs and the services being provided.
The frequency itself is not necessarily the most important issue.
What matters is knowing what to expect.
Find out whether meetings are proactively scheduled by the advisor or whether clients are expected to initiate them. Ask how the advisor communicates when an issue comes up between scheduled reviews.
Retirement can involve decisions about taxes, investments, Social Security, healthcare, estate planning, and withdrawals.
You want a new financial advisor who will be available when those decisions need to be made.
6. How Did You Handle the Last Major Market Downturn?
Markets are relatively easy to discuss when they are rising.
A downturn can tell you much more about an advisor’s philosophy. Ask your prospective advisor what they told clients during the last major market decline.
Were they making significant portfolio changes? Did they encourage clients to stay disciplined? Were they attempting to predict short-term market movements?
Listen closely to the reasoning behind their decisions.
Their answer can help you determine whether their investment philosophy aligns with yours.
It may also reveal how they communicate when markets become stressful.
You are not simply evaluating performance. You are trying to understand the process behind the decisions.
7. Will You Coordinate With My Other Professionals?
Retirement planning rarely happens in isolation.
Your financial decisions may involve your CPA, estate planning attorney, insurance professionals, and other specialists.
Ask whether your new financial advisor helps coordinate those relationships.
An advisor does not need to be an expert in every area. However, someone overseeing your financial plan should understand how the different pieces work together.
For example, an estate plan may establish certain intentions for your assets. Beneficiary designations on retirement or investment accounts also need to align with those intentions.
Tax strategies can involve similar coordination.
A financial advisor who communicates with your CPA can help ensure investment and retirement decisions are considered alongside their potential tax consequences.
Think of your advisor as the quarterback of your financial life rather than simply another player on the field.
8. What Is My Exit Strategy?
It may seem strange to discuss leaving a financial advisor before you have even decided to work with them.
That is exactly why you should ask.
Find out what happens if you decide six months, two years, or even ten years from now that the relationship is no longer right for you.
Can your investments transfer easily?
Are there surrender charges?
Do any products have holding periods or penalties?
Certain financial products, including some annuities, can include surrender schedules that make exiting expensive for a period of time.
Understanding those restrictions before investing is considerably easier than discovering them after you decide you want to leave.
A good relationship should begin with a clear understanding of how it can end.
Don’t Automatically Stay With a New Financial Advisor
A longtime advisor retiring can feel disruptive, especially when that person has guided your finances for years. Still, the transition gives you an opportunity.
Instead of automatically remaining with whoever takes over the practice, evaluate the new financial advisor the same way you would evaluate someone you were hiring from scratch.
Ask about fiduciary responsibility, fees, retirement planning, tax strategy, communication, investment philosophy, professional coordination, and your ability to leave.
These conversations do not need to take hours. In roughly 30 minutes, you can learn a great deal about how an advisor operates and whether their approach fits what you want for your retirement.
The decision matters because small differences in fees, taxes, investment decisions, and retirement planning can compound over many years.
Your financial advisor may have retired, your responsibility for choosing who manages the next stage of your financial life has not.
Considering a New Financial Advisor?
If your financial advisor has retired, your accounts have been transferred to someone new, or you are questioning whether your current advisor is still the right fit, a second opinion can help.
At Bonfire Financial, we look beyond investment allocation to understand how your investments, retirement income, taxes, Social Security, estate planning, and long-term goals work together.
Before signing anything with a new financial advisor, take the time to understand your options.
Schedule a conversation with us to get a second set of eyes on your retirement plan.
If you have been asking yourself, “Should I buy Bitcoin?” you are not alone. Bitcoin has become one of the most talked-about financial topics of the last two decades, but for many cautious investors, it still feels confusing, volatile, and difficult to evaluate. It started as an obscure digital experiment, traded for less than a penny, and has since grown into one of the largest monetary assets in the world. Some people see it as the future of money. Others see it as speculation. Many smart investors are somewhere in the middle.
They are curious, but cautious.
They have heard about Bitcoin for years, they have watched it move through extreme highs and painful drawdowns. Many have seen friends, coworkers, institutions, companies, and even governments begin to pay attention. But they still have the same honest questions:
What actually is Bitcoin?
Why does it matter?
Is it too risky?
How do people store it safely?
Is it something that belongs in a serious financial plan?
And maybe the biggest question of all: should I buy Bitcoin?
This article is based on Part 1 of a two-part conversation between Brian from Bonfire Financial and Bitcoin educator Pasco. The purpose of the conversation was not to hype Bitcoin, pressure anyone to buy, or make price predictions. It was to have a simple conversation about what Bitcoin is, how it works, why serious investors are paying attention, and what cautious investors should understand before taking action.
Whether you decide to own Bitcoin or not, understanding it matters. Any asset this volatile, this misunderstood, and this widely discussed should not be approached casually. It needs to fit inside a real financial plan, not a guess, a hunch, or a fear-of-missing-out decision.
Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.
Why Bitcoin Matters Now
For years, Bitcoin felt like something happening on the fringes of finance. It was associated with tech enthusiasts, early adopters, online forums, and people willing to take unusual risks. But that perception has changed.
Bitcoin has been around since 2009. In that time, it has gone from being ignored by traditional finance to being discussed by financial advisors, institutions, corporations, governments, and retirement-minded investors. The question is no longer simply, “Is Bitcoin real?” Increasingly, the question is, “What role, if any, should Bitcoin play in a modern financial plan?”
Several things have helped bring Bitcoin into the mainstream conversation. The approval of spot Bitcoin ETFs made it easier for traditional investors to gain exposure through familiar investment channels. Institutional adoption brought more legitimacy to the asset class. Corporate balance sheets, sovereign discussions, and regulatory developments have also contributed to the sense that Bitcoin is no longer just an internet novelty.
But mainstream attention does not automatically make something appropriate for every investor.
That distinction matters.
A cautious investor should not buy Bitcoin simply because it is popular. They also should not dismiss it simply because it is unfamiliar. The better approach is to slow down, understand what it is, examine the risks, and then decide whether it fits their goals, timeline, portfolio, and risk tolerance.
What Is Bitcoin?
At its simplest, Bitcoin is decentralized digital money. That phrase sounds simple, but each word matters.
It is digital, meaning it exists electronically rather than as paper bills or physical coins. It is money because people use it to store, send, and transfer value. And it is decentralized because no central bank, government, company, or single authority controls the network.
Most people are used to money being controlled by institutions. Dollars are issued by the government. Bank accounts are managed by banks. Credit card transactions are approved by payment networks. Wires and transfers often require permission, business hours, processing systems, and third parties.
Bitcoin works differently.
The Bitcoin network allows value to be transferred peer-to-peer without relying on a traditional financial intermediary. That does not mean it is simple in every technical detail, but the basic concept is straightforward: Bitcoin is a system for storing and moving value without needing a central authority to approve or control every transaction.
This is one of the reasons Bitcoin is so different from the money most people use every day.
Bitcoin and the Problem of Trust
In the traditional financial system, trust is everywhere.
You trust your bank to hold your money, you trust payment processors to approve transactions and you trust custodians to manage assets. Governments and central banks to maintain the value of currency over time and you trust institutions to keep systems running, maintain access, and follow the rules.
Bitcoin was designed to reduce the need for that kind of trust.
Instead of relying on one central authority, Bitcoin relies on a distributed network. Transactions are verified by participants across the network. The history of transactions is recorded on a public ledger. The rules of the system are transparent, and the supply schedule is known in advance.
That is a very different model than the one most investors grew up with.
For cautious investors, this can feel both empowering and intimidating. On one hand, Bitcoin offers a form of ownership and transfer that does not depend on a bank or central authority. On the other hand, that also means the investor must understand new responsibilities, especially when it comes to security and custody.
Why the Fixed Supply Matters
One of Bitcoin’s most important features is its fixed supply.
There will only ever be 21 million Bitcoin.
That supply cap is central to how many Bitcoin supporters think about the asset. Unlike government-issued currencies, which can be created in larger quantities over time, Bitcoin has a predetermined issuance schedule. New Bitcoin enters circulation through mining, but the amount released over time decreases through a process known as the halving.
Roughly every four years, the block reward paid to miners is cut in half. In Bitcoin’s early years, miners received 50 Bitcoin per block. That reward has declined over time and is now much lower. The next halving is expected in 2028, which will continue reducing the rate at which new Bitcoin is created.
Why does that matter?
Because supply and demand matter in every market.
If an asset has a fixed supply and more people want to own or use it over time, that can create upward pressure on price. That does not mean Bitcoin moves in a straight line. It definitely does not mean there is no risk. But the fixed supply is one of the reasons Bitcoin is often discussed as a potential hedge against currency debasement and long-term inflation.
This is also where Bitcoin becomes interesting to investors who are concerned about the purchasing power of the dollar. If the supply of dollars expands significantly over time, each dollar may buy less in the future. Bitcoin’s supporters argue that a fixed-supply asset offers a different kind of monetary structure.
Again, that does not make Bitcoin risk-free. It simply explains why some investors believe it deserves a place in the conversation.
What Is the Blockchain?
The word “blockchain” gets thrown around constantly, often in ways that make it sound more complicated or more magical than it really is.
In the context of Bitcoin, the blockchain is essentially a ledger.
It is a record of transactions. Transactions are grouped into blocks, and those blocks are linked together in chronological order. Each block contains a batch of transactions, and the chain of blocks creates a historical record of activity on the Bitcoin network.
One helpful way to think about it is as a story that has been written over time. Each new block adds another page to the story. Because the blocks are linked cryptographically, changing the past becomes extremely difficult. The network is designed so that the history of transactions can be verified by participants rather than trusted blindly.
That is part of what makes Bitcoin powerful. It is not just that transactions happen digitally. It is that the system creates a transparent, verifiable history of those transactions without depending on one central recordkeeper.
For the average investor, you do not need to understand every technical detail of cryptography to understand the basic idea. The blockchain is the public ledger that records Bitcoin transactions and helps the network maintain integrity.
What Is Bitcoin Mining?
Bitcoin mining is another term that can confuse people.
Mining does not mean people are digging digital coins out of the ground. It refers to the process by which transactions are processed, blocks are added to the blockchain, and new Bitcoin enters circulation.
Miners use specialized computers to perform work for the network. Their job is to process transactions and compete to add the next block. This process is called proof of work.
Miners are rewarded for successfully adding blocks to the chain. They may receive newly issued Bitcoin, along with transaction fees. Over time, as the block reward continues to decline through halvings, transaction fees are expected to become a more important part of miner compensation.
Mining is important because it helps secure the network. It makes it costly to attack the system and helps ensure that the transaction history remains reliable.
For cautious investors, the key takeaway is this: mining is part of the infrastructure that allows Bitcoin to function without a central authority. It is one of the mechanisms that keeps the network operating and secure.
On-Chain Transactions and the Lightning Network
Bitcoin can be used in different ways.
An on-chain transaction is a transaction recorded directly on the Bitcoin blockchain. This is often compared to a wire transfer, although the comparison is imperfect. On-chain transactions can be highly secure, verifiable, and final, but they may not be ideal for every small everyday purchase.
The Lightning Network is a separate layer built on top of Bitcoin that allows for faster and cheaper transactions. It is often discussed as a way to make small Bitcoin payments more practical. For example, buying coffee with Bitcoin would be more realistic over Lightning than through an on-chain transaction.
The distinction matters because many people misunderstand Bitcoin’s usability. They may assume that Bitcoin is only a slow, clunky settlement system. Others may assume it is already perfect for every payment use case. The reality is more nuanced.
Bitcoin’s base layer is designed for security and final settlement. Layers like Lightning can improve speed and lower costs for smaller transactions.
For investors, this matters because Bitcoin is not only discussed as a price speculation. It is also a monetary network with different layers and use cases.
Self-Custody: What It Means and Why It Matters
One of the biggest ideas in Bitcoin is self-custody.
Self-custody means you hold your own Bitcoin rather than relying on an exchange, bank, or third-party custodian to hold it for you.
In the traditional financial system, most people are used to custodians. A bank holds your cash. A brokerage custodian holds your investments. A retirement plan provider administers your account. If something goes wrong, there is usually a customer service number, a password reset process, or some institutional backstop.
Bitcoin changes that.
If you self-custody Bitcoin properly, you have direct control. No bank has to approve your transaction, no exchange has to grant access, and no institution is holding the asset on your behalf.
That is powerful, but it also comes with responsibility.
If you lose access to your private keys or seed phrase, you may permanently lose access to your Bitcoin. If someone steals that information, they may be able to take your Bitcoin. Unlike a fraudulent credit card charge, there may be no simple reversal process.
This is one of the most important things cautious investors need to understand. Bitcoin gives people more control, but it also requires better education and security.
“Not Your Keys, Not Your Coins”
The phrase “not your keys, not your coins” is common in the Bitcoin world.
It means that if you do not control the private keys to your Bitcoin, you are relying on someone else to give you access. If your Bitcoin sits on an exchange, you may have price exposure, but you do not have the same level of direct ownership as someone who controls their own keys.
This became especially important after major failures in the crypto industry, including exchange collapses that left customers unable to access funds. The lesson for many investors was clear: leaving assets on an exchange can create third-party risk.
That does not mean every investor must immediately self-custody everything. It does mean investors should understand the trade-offs.
Using an exchange may feel easier, especially for beginners. Self-custody can provide greater control, but it requires education, planning, and good security practices. Some investors may use a combination of approaches. Others may work with professionals to build a custody process that reduces single points of failure.
The main point is not to rush. The main point is to understand what kind of ownership you actually have.
The Real Risks of Bitcoin
Bitcoin is not risk-free.
Any honest conversation about Bitcoin must include the risks. For cautious investors, this is where the conversation becomes especially important.
The first major risk is volatility. Bitcoin can move dramatically in short periods of time. It has experienced large drawdowns in the past, and there is no reason to assume volatility will disappear completely. An asset that can move significantly in a week, month, or year must be sized appropriately.
The second risk is custody. If you self-custody Bitcoin and make a serious mistake, the consequences can be permanent. Lost keys, poor storage, scams, and security errors can result in irreversible loss
The third risk is emotional decision-making. Bitcoin attracts hype. Investors may be tempted to buy aggressively after a big price increase, then panic during a decline. That kind of behavior can turn a potentially strategic allocation into a gambling experience.
The fourth risk is regulatory uncertainty. Bitcoin has become more mainstream, but regulation can still evolve. Investors should pay attention to how rules, reporting requirements, custody standards, taxation, and investment product access may change over time. Bitcoin has become more accepted, but that does not mean the regulatory environment is finished evolving.
The fifth risk is scams and misinformation. Because Bitcoin is technical and still unfamiliar to many people, bad actors often take advantage of beginners. Fake investment platforms, phishing links, fraudulent wallet support, impersonators, and “guaranteed return” offers are all real dangers. If someone is promising a risk-free way to make money with Bitcoin, that should be a major red flag.
The sixth risk is overconfidence. Some investors hear the Bitcoin story, understand the fixed supply, see the historical performance, and immediately want to go all in. That can be dangerous. Even if someone believes Bitcoin has long-term potential, that does not mean it should dominate their portfolio. A good investment can still become a bad decision if it is oversized, misunderstood, or purchased for the wrong reasons.
This is why Bitcoin should be approached with humility. It may have a place in a portfolio, but it should not replace a real financial plan.
Volatility Is Not a Side Note
One of the most important things cautious investors need to understand before buying Bitcoin is volatility.
Bitcoin can move dramatically. It has had periods of extraordinary growth, but it has also experienced sharp drawdowns. For investors used to traditional portfolios, those swings can feel intense.
Volatility does not automatically mean Bitcoin is bad. Many long-term assets experience volatility. Stocks, real estate, oil, and other assets can all move up and down. But Bitcoin’s volatility can be especially difficult because the asset trades around the clock, is heavily discussed online, and often attracts emotional behavior.
That creates a real behavioral challenge.
It is one thing to say, “I am a long-term investor,” when the price is rising. It is another thing to remain disciplined when the price is down significantly and every headline feels negative.
This is where planning matters.
Before buying Bitcoin, investors should ask themselves:
How would I feel if this dropped 30 percent?
How would I feel if it dropped 50 percent?
Would I panic sell?
Would this affect my retirement plan?
Would I still be able to meet my income needs?
Would I be tempted to buy more at exactly the wrong time because of fear of missing out?
These questions are not meant to scare people away. They are meant to help investors be honest.
If a Bitcoin position is sized correctly, volatility may be tolerable. If it is too large, volatility can take over the entire financial plan.
Bitcoin as Part of a Portfolio
When people ask, “Should I buy Bitcoin?” they often want a simple answer.
Yes or no.
But for serious investors, the better answer is usually more nuanced.
Bitcoin should not be evaluated in isolation. It should be evaluated in the context of a full financial plan.
That means looking at your income, expenses, retirement timeline, cash reserves, tax situation, existing investments, real estate, business interests, estate plan, and risk tolerance. Bitcoin may be interesting, but it is still only one piece of the bigger picture.
For some investors, Bitcoin may serve as a small alternative asset allocation. And for others, it may not be appropriate at all. For some, the best first step may be education before any purchase is made.
The key is position sizing.
A small allocation may allow an investor to participate in Bitcoin’s potential upside without putting the entire plan at risk. A large allocation can create stress, concentration risk, and emotional decision-making.
This is especially important for people nearing or already in retirement. When you are still working and accumulating assets, you may have more time to recover from volatility. When you are depending on your portfolio for income, large swings can have a bigger impact.
That does not mean retirees can never own Bitcoin. It means the decision requires more care.
Bitcoin should fit the plan. The plan should not bend around Bitcoin.
The Problem With FOMO Buying
One of the most dangerous ways to buy Bitcoin is through FOMO. The fear of missing out is powerful. Bitcoin has had massive price moves in the past, and many people know someone who bought early and did well. That creates a feeling of urgency.
But urgency is not the same as wisdom.
When investors buy because they feel late, rushed, or embarrassed that they missed earlier opportunities, they often make poor decisions. They may buy too much, buy at emotionally heated moments, or fail to understand custody. A cautious investor should resist the pressure to act before understanding.
There will always be another headline or another price prediction. Just as there will always be someone online saying Bitcoin is going much higher or going to zero.
None of that replaces a plan.
The better approach is to slow down and ask:
What do I actually understand?
What am I still confused about?
What would I be buying?
Why would I be buying it?
How much would be appropriate?
How would I hold it safely?
What would cause me to sell?
How does this fit with the rest of my financial life?
If you cannot answer those questions, the next step may not be buying Bitcoin. The next step may be learning more.
How to Start With Bitcoin the Right Way
For cautious investors who decide they want to take the next step, the best approach is usually not to go all in.
A better approach is to start with education.
Learn what Bitcoin is, how it is different from other cryptocurrencies. Take the time to understand how the network works at a basic level. Learn what self-custody means, what private keys are and what exchanges do. Be aware of how scams work. Learn how taxes may apply and how volatility can affect your behavior.
Then, if Bitcoin still makes sense, start small.
Starting small allows investors to get familiar with the process without putting meaningful wealth at risk. It also gives them time to learn the practical side of Bitcoin ownership.
Some investors may choose to buy through a reputable, regulated exchange. Others may use Bitcoin ETFs for exposure inside traditional accounts. Others may eventually explore self-custody with a hardware wallet. Each approach has trade-offs.
Buying through an exchange may be easy, but it introduces third-party custody risk if the Bitcoin is left there.
Using an ETF may be convenient inside a brokerage or retirement account, but it is not the same as holding Bitcoin directly.
Self-custody may offer more control, but it requires more education and responsibility.
The right path depends on the investor.
The important thing is to understand what you are doing before moving large amounts of money.
What Is Self-Custody?
Self-custody means holding your own Bitcoin rather than relying on a third party to hold it for you.
In traditional finance, people are used to custodians. Banks hold cash. Brokerage firms hold investments. Retirement account providers hold assets. If you lose a password, you can usually reset it. If there is fraud, there may be processes to dispute or reverse transactions.
Bitcoin works differently.
If you hold your own Bitcoin, you control the keys that allow the Bitcoin to move. That control is powerful because it means no bank, exchange, or institution has to give you permission. But it also means you are responsible for protecting access.
That is why self-custody is both one of Bitcoin’s greatest strengths and one of its biggest learning curves.
A hardware wallet is one common tool for self-custody. It helps keep private keys offline and away from many online threats. But even with a hardware wallet, the investor must properly secure the recovery phrase. If that phrase is lost or stolen, the Bitcoin may be gone permanently.
This is where cautious investors need to be especially careful.
Investors should not rush into self-custody. Start by learning how it works, practicing with small amounts, and documenting the process carefully. Families should also coordinate self-custody with their estate plan.
When one spouse understands Bitcoin but the other does not, access and continuity can become a planning problem. Heirs also need clear instructions, because confusion after death or incapacity could leave the Bitcoin unreachable. Careless storage of recovery information creates a separate security risk and can put the asset in danger.
Bitcoin custody is not just a technical issue. It is a financial planning issue.
Not Your Keys, Not Your Coins
One of the most common phrases in Bitcoin is “not your keys, not your coins.”
The idea is simple. If someone else controls the keys, you are depending on them. You may have a claim on Bitcoin, but you do not have the same kind of direct control as someone who holds their own keys.
This became especially clear after the collapse of major crypto platforms. Many people believed they owned assets safely because they could see balances on a screen. But when the platform failed, they learned that access and ownership were more complicated than they realized.
That does not mean every investor must immediately self-custody everything. It does mean investors should understand the difference between exposure and control.
A Bitcoin ETF can provide price exposure.
An exchange account can provide convenient access.
Self-custody can provide direct control.
Each option has benefits and risks.
The right answer depends on the investor’s goals, technical comfort, account structure, estate plan, and risk tolerance. But no investor should confuse convenience with safety or assume that all forms of Bitcoin ownership are the same.
Dollar Cost Averaging and Taking Baby Steps
For cautious investors, dollar cost averaging may be worth considering.
Dollar cost averaging means buying a fixed dollar amount at regular intervals rather than investing one large lump sum all at once. This approach can help reduce the emotional pressure of trying to perfectly time the market.
With Bitcoin, this can be helpful because price swings can be dramatic. Someone who invests a large amount all at once may feel immediate regret if the price drops. Someone who builds a position gradually may have more time to learn, adjust, and remain disciplined.
Dollar cost averaging does not remove risk. It does not guarantee profit. It does not prevent losses.
But it can help investors avoid making one emotional, all-or-nothing decision. It also lines up with one of the most important themes from the conversation: baby steps.
You do not need to understand every technical detail on day one. Nor do you need to buy a large amount, and you do not need to become a Bitcoin expert overnight.
You can start by learning.
You can ask questions.
You can understand the risks.
You can get familiar with the tools.
You can decide whether a small allocation makes sense.
That is a much healthier path than rushing in because a price chart looks exciting.
The Biggest Mistakes Beginners Make
Many Bitcoin mistakes happen early.
The first mistake is buying without understanding. This is common. Someone hears about Bitcoin, sees the price moving, and buys before they know what it is. That creates emotional ownership instead of informed ownership.
The second mistake is buying too much. Even if Bitcoin has long-term potential, an oversized position can create stress and lead to bad decisions.
The third mistake is leaving Bitcoin on an exchange without understanding the risk. Exchanges can be useful, especially for beginners, but leaving assets there indefinitely can introduce third-party risk.
The fourth mistake is mishandling self-custody. Some people move too quickly into wallets and keys without understanding how recovery works. That can be dangerous.
The fifth mistake is falling for scams. Bitcoin transactions are irreversible. If someone tricks you into sending Bitcoin, there may be no way to get it back. This makes skepticism essential.
The sixth mistake is confusing Bitcoin with every other crypto asset. Bitcoin is often grouped into the broader crypto category, but it has unique characteristics, history, network effects, and monetary properties. Investors should understand exactly what they are buying.
The seventh mistake is failing to connect Bitcoin to a financial plan. Bitcoin should not be a side bet that lives outside the rest of your financial life. It should be evaluated alongside everything else you own.
Should I Buy Bitcoin?
So, should you buy Bitcoin?
The honest answer is: maybe.
That may not be the exciting answer, but it is the responsible one.
Bitcoin may make sense for some investors. It may not make sense for others. For many people, the right answer may be to learn first and decide later.
Before buying Bitcoin, a cautious investor should be able to answer a few basic questions:
Do I understand what Bitcoin is?
Do I understand why it has value to some people?
Do I understand the fixed supply?
Do I understand the volatility?
Do I understand custody risk?
Do I know how I would buy it?
Do I know how I would hold it?
Do I know how much I would buy?
Do I know why that amount fits my plan?
Do I know what would make me sell?
Do I know how this affects my taxes and estate planning?
If the answer to most of those questions is no, then buying Bitcoin may not be the right first step.
Learning may be the right first step.
The goal is not to avoid Bitcoin out of fear. The goal is to avoid making an uninformed decision.
Why a Fiduciary Perspective Matters
Bitcoin is one of those topics where incentives matter.
There are many people online who want you to buy something, trade something, click something, or believe something. Some may be sincere. Others may be compensated in ways that are not obvious.
For cautious investors, that matters.
A fiduciary financial advisor is required to put your interests first. That does not mean every advisor understands Bitcoin deeply. But it does mean the conversation should begin with your financial life, not with someone else’s sales pitch.
A fiduciary conversation about Bitcoin should include risk, position sizing, taxes, custody, estate planning, retirement income, liquidity, and your broader goals.
It should not be based on hype.
It should not be based on fear.
It should not be based on what someone on the internet says will happen next.
It should be based on your plan.
That is especially important for investors near retirement or already retired. A bad Bitcoin decision may not just affect a brokerage account. It could affect income planning, withdrawal strategies, family wealth, charitable goals, and peace of mind.
This is why Bitcoin should be discussed with seriousness. Not as a trend, a lottery ticket, or as a guaranteed answer, but as a volatile, important, misunderstood asset that may or may not belong in a thoughtful financial plan.
Final Thoughts: Learn First, Then Decide
If you have been asking, “Should I buy Bitcoin?” the best first step is not to rush into a yes or no answer. The best first step is to understand what Bitcoin is, how it works, what risks come with it, and whether it has a place in your broader financial plan.
Bitcoin is decentralized digital money with a fixed supply, a global network, and a very different structure than the traditional banking system. That is exactly why it has become such an important financial conversation. But Bitcoin is also volatile, custody matters, scams exist, regulation can evolve, and emotional decision-making can lead to real mistakes.
For cautious investors, the right approach is not hype. It is education.
That is why Pasco created Bitcoin Minded, a self-paced course designed to help people learn Bitcoin in a structured, plain-English way before making decisions.
And this conversation is not over. Be sure to stay tuned for Part 2 next week, where Brian and Pasco continue the discussion and dive deeper into how Bitcoin may fit inside a real financial plan, including risk, custody, position sizing, and the practical steps investors should understand before taking action.
Whether you decide to own Bitcoin or not, understanding it matters. And if you do decide to buy, make sure it is part of a plan. Not a guess.
How a Smart Retirement Investing Strategy Can Help $100K Grow Into $2 Million
Can $100,000 really grow into $2 million by retirement?
For many people, that number feels unrealistic. It sounds like something that only happens if you pick the right stock, get lucky with the market, inherit money, or earn an extremely high income.
But that is not usually how retirement wealth is built.
In reality, growing $100K into $2 million often comes down to a handful of simple but powerful retirement investing strategies. They are not flashy. They do not require perfect market timing. And they definitely do not require chasing the next hot investment.
They require consistency, patience, discipline, and the right structure.
Today we will break down five reasons some retirees are able to turn $100,000 into $2 million or more, and how you can apply those same principles to your own retirement plan.
Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.
1. Let Compounding Do the Heavy Lifting
The first major reason $100K can grow into $2 million is the power of compounding. Compounding is when your money earns returns, and then those returns begin earning returns of their own. Over time, that snowball effect can become incredibly powerful.
For example, if $100,000 grows at an average annual return of around 10%, it can grow to more than $1.7 million over roughly 30 years. That does not happen because of one lucky investment. It happens because time and growth are working together.
The problem is that compounding is hard to see in the beginning. In the early years, the growth can feel slow. You may not feel like much is happening. But later, the growth can accelerate because your gains are building on prior gains.
That is why one of the biggest mistakes investors make is interrupting compounding too early. They get impatient. They move in and out of the market. They stop investing during scary periods. Or they keep too much money sitting in cash because they are waiting for the “perfect” time to invest.
But compounding rewards time in the market, not perfect timing. The sooner you start and the longer you stay invested, the more opportunity your money has to grow.
2. Contribute Consistently
Compounding is powerful, but it needs fuel.
That fuel is consistent contributions.
Most people who build serious retirement wealth do not do it by investing one time and walking away forever. They build wealth by putting money away consistently over many years.
That may mean contributing to a 401(k), Roth IRA, brokerage account, SEP IRA, SIMPLE IRA, or another investment account. The exact account depends on your situation, but the habit is the same: money goes in regularly.
One of the best ways to make this happen is to automate it.
Willpower is not a great retirement strategy. Life gets busy. Expenses pop up. Markets get scary. It is easy to talk yourself out of investing when you have to manually make the decision every month.
Automation removes that friction. When contributions happen automatically, you are no longer relying on motivation. You are building the habit into your financial system.
That is how retirement wealth is usually created. Not through one dramatic decision, but through repeated decisions made easier over time.
A strong retirement investing strategy should answer questions like:
How much are you saving each month?
Which accounts are you contributing to?
Are your contributions automatic?
Are you increasing contributions as your income grows?
Are you taking advantage of employer matching when available?
If you want $100K to become $2 million, consistency matters. A lot.
3. Stay Invested When the Market Drops
This is where many investors lose momentum. It is easy to say you are a long-term investor when the market is going up. It is much harder when your account is down 20%, 30%, 40%, or more.
When the market drops, people do not usually think in percentages. They think in dollars.
A 20% decline on a $1 million portfolio is not just “20%.” It feels like $200,000 is gone. That can be emotionally brutal, especially for people approaching retirement.
This is when investors often panic. They sell. They move to cash. They abandon the strategy they built during calmer times.
The problem is that selling after a major decline can lock in losses and make it harder to recover.
For example, if you have $100,000 and the market drops 50%, you now have $50,000. To get back to $100,000, you do not need a 50% gain. You need a 100% gain.
That is why your investment strategy needs to match your actual risk tolerance before the downturn happens. If your portfolio is too aggressive, you may not be able to emotionally stick with it when things get rough. But if your portfolio is too conservative, your money may not grow enough to support the retirement you want.
The goal is not to build the most aggressive portfolio possible. The goal is to build a portfolio you can stay invested in through different market cycles.
Because the investors who benefit from long-term growth are usually the ones who remain invested long enough to experience it.
4. Keep Investment Fees Low
High fees can quietly eat away at your retirement savings.
That is why fees are often called the silent killer of investment returns. Many investors do not realize how much they are paying inside mutual funds, ETFs, annuities, insurance products, alternative investments, or retirement plans. The fees may be disclosed, but they are often buried in long documents most people never read.
Even a small difference in fees can have a major impact over time.
For example, there is a big difference between an investment charging 0.03% and one charging 1.5%. That difference may not feel huge in one year, but over decades it can add up to a substantial amount of money.
Sometimes paying for advice, planning, or professional management can make sense. The real question is whether you understand what you are paying and whether you are receiving value for that cost.
A good retirement investing strategy should help you identify:
Fund expense ratios
401(k) administrative fees
Advisory fees
Annuity or insurance product fees
Trading costs
Hidden or layered investment expenses
If you have a 401(k), you can often find fee information on your quarterly statement, summary plan description, or by asking your plan administrator. You can also look up fund tickers through financial research sites to review expense ratios.
The bottom line is simple: the less you lose unnecessarily to fees, the more of your return you keep. And the more you keep, the more you can compound.
5. Use the Right Mix of Retirement Accounts
Building $2 million is one thing. Keeping more of it is another.
This is where account structure becomes incredibly important.
Many people save heavily into a 401(k), which can be a great tool. But if all of your retirement savings are in pre-tax accounts, you may create a tax problem later.
Money taken out of a traditional 401(k), traditional IRA, SEP IRA, SIMPLE IRA, or profit-sharing plan is generally taxed as ordinary income. That means every dollar you withdraw can increase your taxable income in retirement.
If all of your retirement income comes from pre-tax accounts, you may have less flexibility to manage your tax bill.
That is why it can help to build wealth across different types of accounts.
Pre-tax accounts
These include accounts like traditional 401(k)s, traditional IRAs, SEP IRAs, SIMPLE IRAs, and profit-sharing plans.
You may receive a tax benefit when you contribute, but withdrawals are generally taxable later.
Roth accounts
Roth IRAs and Roth 401(k)s are funded with after-tax dollars. The potential benefit is that qualified withdrawals can be tax-free in retirement.
This can give you more flexibility later, especially if tax rates rise or your taxable income is higher than expected.
Taxable brokerage accounts
Brokerage accounts are funded with after-tax dollars. You do not receive the same upfront tax break as a pre-tax retirement account, but you may have more flexibility with withdrawals, capital gains treatment, and access before retirement age.
Having a mix of account types can give you more options.
For example, in retirement, you may choose to take some income from a pre-tax account, some from a Roth account, and some from a brokerage account. That can help you manage your taxable income, coordinate with Social Security, and potentially reduce unnecessary taxes.
This is one of the biggest differences between simply accumulating money and building a real retirement income strategy.
The goal is not just to grow the account balance, it is to create flexibility, control, and income that supports the life you want.
The Real Retirement Investing Strategy
The retirees who grow $100K into $2 million usually do not get there because they made one genius investment.
They usually get there because they followed a few core principles for a long period of time.
They understood compounding.
They contributed consistently.
They stayed invested through difficult markets.
They paid attention to fees.
They built wealth across the right types of accounts.
None of these strategies require you to predict the future. None require you to time the market perfectly. And none require you to chase whatever investment is popular this year.
But they do require a plan.
Without a plan, it is easy to make emotional decisions. It is easy to overpay in fees. It is easy to end up with all of your money in one tax bucket. And it is easy to build wealth without knowing how to turn that wealth into retirement income.
That is where many people get stuck. They save. They invest. They accumulate.
But when retirement gets closer, they realize they do not have a coordinated strategy for taxes, income, risk, withdrawals, and long-term flexibility.
Bringing It All Together
A smart retirement investing strategy is not just about picking investments. It is about building a system that helps your money grow, protects you from emotional decisions, reduces unnecessary costs, and gives you flexibility when you need income later.
Turning $100K into $2 million does not happen overnight. It happens through time, discipline, and structure.
The earlier you start, the more powerful compounding can become.
The more consistently you contribute, the more fuel you give your plan.
The better your portfolio fits your risk tolerance, the more likely you are to stay invested.
The more you understand your fees, the more of your return you can keep.
And the better your account structure, the more control you may have in retirement.
That is the difference between simply having investments and having a retirement strategy.
Next Steps
If you are serious about retirement, do not stop at asking, “Am I invested?”
Ask better questions:
Do I have the right retirement investing strategy?
Could taxes take more of my retirement income than they need to?
Do I know how I will turn my portfolio into income?
At Bonfire Financial, we help people answer those questions through a more complete planning process.
The Bonfire Method is designed to help you look at your full financial picture, including investments, taxes, income, risk, and retirement goals, so you can make smarter decisions with more confidence.
If you want to know whether your current strategy is built to support the retirement you actually want, schedule a call with Bonfire Financial.
A better retirement does not happen by accident. It starts with a better strategy.
When most people think about building wealth in retirement, they focus on buying more assets. More real estate, more investments, more financial products. More “opportunities.” But wealthy retirees often think very differently. Instead of chasing every investment idea that gets pitched to them, they focus heavily on simplicity, cash flow, flexibility, and avoiding unnecessary financial drag.
That distinction matters.
Some retirement assets look impressive on paper but quietly create stress, reduce liquidity, increase fees, or slowly eat away at retirement income over time. Others are sold aggressively because they generate commissions for someone else, not because they are necessarily the best fit for your situation.
We regularly meet retirees who own assets they barely understand, properties that lose money every month, or financial products that sounded great in the sales presentation but became frustrating later. The goal is not to say every one of these retirement assets is automatically bad. In some cases, they can absolutely make sense. The key is understanding whether the asset truly supports your retirement lifestyle and long-term financial goals.
Here are eight retirement assets wealthy retirees often avoid, or at the very least approach with much more caution.
Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.
1. Investment Real Estate That Does Not Cash Flow
Real estate can absolutely be a fantastic investment. Many wealthy individuals have built substantial wealth through real estate ownership.
But there is a major difference between owning productive real estate and owning a property that consistently drains your cash flow.
One of the most common retirement asset mistakes people make is buying investment properties that lose money every month while convincing themselves the appreciation will eventually make it worthwhile. Often the justification becomes:
“It’ll be paid off someday.”
The problem is that retirement is about cash flow now, not just theoretical future equity decades later.
If a property requires constant subsidizing, expensive maintenance, ongoing repairs, rising insurance premiums, and unpredictable tenant issues, it may not actually be serving your retirement lifestyle the way you think it is.
That does not mean every property must generate massive profits immediately. Some investors intentionally pursue appreciation-focused strategies. But wealthy retirees usually understand exactly why they own a property, what role it serves, and whether it is helping or hurting their financial picture.
The key question is simple:
Is this retirement asset improving your life and strengthening your finances, or is it becoming a burden?
2. Complex Financial Products You Do Not Understand
One thing wealthy retirees often avoid is unnecessary complexity.
Many financial products sound incredibly appealing because they promise downside protection, enhanced income, or sophisticated strategies unavailable to average investors. Structured notes and highly engineered financial products are often marketed this way.
The issue is not necessarily that these products are always bad. Some can absolutely serve a purpose in certain situations.
The problem is when people buy retirement assets they do not truly understand.
If you cannot clearly explain:
How the investment works
What risks exist
When you can access your money
How returns are generated
What the fees are
then you probably should not own it.
Wealthy retirees who sleep well at night often prioritize clarity over complexity. They know where their money is, what it is doing, and why they own it. That level of simplicity becomes incredibly valuable in retirement.
3. Timeshares
Timeshares are one of the most heavily sold retirement assets on the market.
The sales presentations are designed to feel emotional and exciting. Beautiful resorts, family memories, beachfront views, luxury vacations, and the promise of saving money long-term can make timeshares sound extremely appealing in the moment.
But the reality often looks very different later.
Many retirees eventually realize they committed themselves to:
Long-term contracts
Ongoing maintenance fees
Limited flexibility
Rising costs
Difficult resale markets
Life changes over time. Health changes. Travel preferences change. Family dynamics change.
A vacation property that seemed perfect ten years ago may no longer fit your lifestyle today.
Wealthy retirees often value flexibility more than people realize. Instead of locking themselves into long-term vacation commitments, many prefer the freedom to travel wherever they want, when they want, without ongoing contractual obligations.
The issue is not necessarily the vacation itself. The issue is becoming financially trapped by an asset that no longer serves your lifestyle.
4. Whole Life Insurance as an Investment
Insurance is incredibly important.
But insurance and investing are not always the same thing.
One of the more controversial retirement assets is whole life insurance used primarily as an investment vehicle. These policies are often marketed as:
Forced savings
Tax advantages
Borrowing opportunities
Stable growth
Wealth-building tools
And while there are situations where whole life insurance absolutely makes sense, many retirees end up purchasing expensive policies that may not align with their actual needs.
One major issue is cost.
Whole life insurance policies can involve:
High premiums
Significant commissions
Slow early growth
Complex structures
Lower long-term returns compared to other investments
That does not automatically make them bad. But wealthy retirees typically understand exactly why they are purchasing a policy before committing to one.
If the primary need is protecting a spouse or family financially, there may be simpler and more efficient ways to accomplish that goal.
This is why many retirees should approach whole life insurance carefully rather than assuming it is automatically a strong investment.
5. High-Fee Annuities
Annuities are another retirement asset that can create strong opinions.
The truth is, annuities are not inherently bad. In fact, some retirees benefit tremendously from them.
At their core, annuities function somewhat like personal pensions by providing guaranteed income streams.
That can be extremely valuable in retirement.
However, many retirees buy annuities without fully understanding:
The fees
Liquidity restrictions
Tax implications
Surrender periods
Income limitations
Some annuities contain fees that quietly reduce returns year after year. Others lock up money for extended periods, making access difficult without penalties. This becomes especially problematic when retirees need flexibility later.
Wealthy retirees often avoid retirement assets that unnecessarily trap capital or create confusion. If they use annuities, it is usually because the product fits a very specific need within an overall retirement strategy.
Not because it was aggressively sold as a one-size-fits-all solution.
6. Vacation Homes That Become Financial Burdens
Vacation homes sound amazing in theory.
And for some wealthy retirees, they absolutely can be.
But there is an important difference between enjoying a second home and becoming financially overextended because of one.
Many retirees underestimate the true cost of owning multiple properties. Beyond the mortgage itself, there are:
Taxes
Insurance
Maintenance
Utilities
Repairs
Furnishing costs
HOA fees
Travel expenses
In some cases, retirees discover they spend more time maintaining the property than actually enjoying it.
Instead of feeling like a relaxing escape, the property slowly becomes another responsibility.
Wealthy retirees tend to evaluate retirement assets based on lifestyle value, not just emotional appeal. If a second home genuinely improves quality of life and fits comfortably within the financial plan, that is one thing.
But if it is creating stress, adding too many expenses, reducing flexibility, or draining cash flow, it may no longer be serving its intended purpose.
Sometimes renting luxury vacations when desired creates far more freedom than owning another home full-time.
7. High-Fee Actively Managed Mutual Funds
Many retirees assume actively managed mutual funds must be superior because professional managers are selecting investments on their behalf.
But statistics consistently show that many actively managed funds underperform their benchmarks over long periods of time, especially after fees.
This becomes one of the biggest hidden problems with certain retirement assets.
Fees matter enormously over time.
Even small percentage differences can compound into substantial reductions in long-term wealth over decades.
Wealthy retirees often focus heavily on:
Low costs
Tax efficiency
Diversification
Simplicity
Long-term consistency
That is one reason index investing has become increasingly popular.
The issue is not that every actively managed fund is bad. Some managers absolutely outperform. The challenge is identifying them consistently in advance.
Many retirees end up paying high fees for performance that ultimately fails to justify the added cost.
8. Oversized Homes
A home is not automatically a bad retirement asset.
But oversized homes can quietly become major financial drains in retirement.
Many retirees remain in houses far larger than what they realistically use because of emotional attachment or habit. Meanwhile, the ongoing costs continue rising:
Property taxes
Insurance
Utilities
Repairs
Landscaping
Cleaning
Maintenance
A large home can also create physical stress as people age.
Wealthy retirees often prioritize functionality and lifestyle over simply owning the biggest house possible. They understand that reducing unnecessary overhead can significantly improve retirement flexibility and reduce financial pressure.
This does not mean everyone should downsize immediately. But retirees should honestly evaluate whether their current home still serves their life today or whether it is simply consuming resources unnecessarily.
Sometimes simplifying housing creates one of the biggest quality-of-life improvements in retirement.
The Common Theme Behind These Retirement Assets
Every retirement asset on this list shares something in common.
They often:
Look impressive initially
Are heavily sold
Sound financially sophisticated
Create hidden costs
Reduce flexibility
Add complexity
Slowly transfer value away from the owner
Wealthy retirees who feel financially secure often approach retirement differently.
They tend to value:
Cash flow
Simplicity
Liquidity
Flexibility
Low fees
Clear understanding
Lifestyle alignment
They know exactly what their money is doing and why they own each asset.
That level of clarity becomes incredibly important in retirement because complexity often creates stress, confusion, and hidden financial inefficiencies.
Simplicity Often Wins in Retirement
One of the biggest misconceptions about wealth is that wealthy retirees own the most complicated portfolios or sophisticated financial products.
In reality, many financially successful retirees keep things surprisingly simple.
Retirement should ideally create freedom, not additional stress.
The goal is not accumulating impressive-sounding retirement assets. The goal is building a financial life that supports your lifestyle, protects your long-term security, and gives you confidence moving forward.
Final Thoughts
Not every retirement asset is automatically good or bad.
The real question is whether the asset aligns with your goals, cash flow needs, risk tolerance, and retirement lifestyle.
Many retirement products are marketed aggressively because they generate commissions, fees, or long-term contracts. That does not mean they are wrong for everyone. But it does mean retirees should approach them carefully and fully understand what they are buying before committing.
At Bonfire Financial, we believe retirement planning works best when people clearly understand how every piece of their financial picture fits together. If you want help evaluating your retirement assets and building a coordinated retirement strategy, learn more about The Bonfire Method and schedule a conversation with our team.
It’s one of the most common financial questions out there:
Should you pay off your mortgage… or invest your money?
On the surface, it feels like there should be a clear, right answer. Pay off debt and be safe. Or invest and grow your wealth.
But that’s not how money actually works.
The truth is, this isn’t really a math problem. It’s a decision shaped by tradeoffs, behavior, timing, and your personal situation. And the reason this question feels so big is because people think they have to get it perfect.
They don’t.
In fact, trying to make the perfect decision is often what keeps people stuck.
Let’s break this down the right way.
Keep reading, or if you prefer to listen or watch…check out the Podcast or full YouTube video.
It’s not just a financial decision. It’s emotional. It’s tied to security, identity, and stability.
So when someone asks, “Should I pay this off?” what they’re really asking is:
Am I making a mistake if I don’t?
Am I missing out if I do?
What if I choose wrong and can’t recover?
That fear tends to get stronger over time.
When you’re younger, mistakes feel fixable. You’re working, you have income, and time is on your side. But as you get closer to retirement, the margin for error feels smaller.
There’s no paycheck coming in to fix things. That’s where the pressure comes from. And ironically, that pressure is what makes people worse with money.
The Problem With Trying to Make the “Perfect” Decision
Most people approach money like there’s a single correct move.
There isn’t.
Money is not a test with one right answer. It’s a series of decisions over time, each with tradeoffs.
When you start believing there’s a perfect choice, a few things happen:
You overthink everything
You hesitate to act
You beat yourself up over small mistakes
You lose perspective on what actually matters
You end up stuck in a loop of “what if.”
What if I invest and the market drops? What if I pay off my mortgage and miss out on gains? What if I choose wrong?
Here’s the reality: Most financial decisions are not catastrophic.
They only become catastrophic when:
You go all-in on a bad decision
You ignore risk
Or you let emotion drive the process
This is where a better framework matters.
Money Isn’t About Perfection. It’s About Tradeoffs.
Every financial decision is a tradeoff.
If you put extra money toward your mortgage, you’re:
Reducing debt
Lowering future expenses
Increasing security
But you’re also:
Giving up liquidity
Potentially missing investment growth
Locking money into an illiquid asset
If you invest instead, you’re:
Keeping your money working
Maintaining flexibility
Potentially growing wealth faster
But you’re also:
Taking on market risk
Keeping your debt longer
Living with more uncertainty
There is no version where you win everything.
So the real question isn’t:
“Which is better?”
It’s:
“Which tradeoff makes the most sense for me?”
The Math Behind It
Let’s simplify this. The biggest factor in this decision is your mortgage interest rate.
Scenario 1: Low Interest Rate Mortgage (2–4%)
If you have a mortgage in the 2–4% range, you’re in a unique position.
In this scenario, paying off your mortgage early is usually not the most efficient move from a pure financial standpoint.
Scenario 2: Higher Interest Rate Mortgage (5–7%+)
Now flip it. If your mortgage rate is 5%, 6%, or higher, the math starts to shift.
Why?
Because now:
Paying off your mortgage is like earning a guaranteed 5–7% return
That return is risk-free
And it directly reduces your expenses
To match that return through investing, you’d have to:
Take on more risk
Deal with volatility
Accept uncertainty
So in higher-rate environments, paying down your mortgage becomes much more attractive. Not because it’s always the best move, but because the tradeoff changes.
The One Thing Most People Miss
Here’s where people get this wrong.
They assume this decision is purely about returns.
It’s not. It’s about behavior.
Let’s say someone invests instead of paying off their mortgage.
On the flip side, paying off a mortgage forces discipline.
You’re:
Building equity
Reducing debt
Locking in a guaranteed outcome
So the better option depends on what you will actually do, not what looks best on paper.
The “Vegas Rule” for Investing
A simple way to think about risk is this: Only take risks you can afford to lose.
Think about going to Vegas.
The people who walk away happy are the ones who:
Set a limit
Stick to it
Treat it like entertainment
The ones who get into trouble:
Chase losses
Double down
Ignore the plan
Investing works the same way.
If you’re going to take risk:
Keep it within a reasonable portion of your net worth
Don’t bet everything on one outcome
Don’t let one decision derail your entire plan
This is especially important as you get older.
You don’t need to hit home runs. You just need to avoid strikeouts.
Why Paying Off Your Mortgage Feels So Good
There’s a reason people love the idea of being debt-free.
It’s not just financial. It’s psychological.
No monthly payment
Lower fixed expenses
Greater sense of control
Less stress
In retirement, this matters even more.
Without a mortgage:
Your lifestyle becomes easier to maintain
Your required income drops
Your financial plan becomes simpler
But there’s a catch.
The Hidden Limitation of Home Equity
Your home may be your biggest asset.
But it’s not very useful for cash flow.
You can’t:
Use it at the grocery store
Easily tap it without selling or borrowing
Rely on it for day-to-day expenses
So while paying off your mortgage increases your net worth…
…it doesn’t necessarily increase your ability to fund your lifestyle.
That’s why a balanced approach matters.
The Real Risk: Living Beyond Your Means
If there’s one thing that consistently causes problems, it’s not this decision. It’s lifestyle creep.
Spending beyond your means, over time, will break any plan.
It doesn’t matter if you invest
It doesn’t matter if you pay off your house
It doesn’t matter how much you earn
If your lifestyle keeps expanding faster than your resources, you’ll eventually run into trouble.
The goal isn’t to maximize every dollar.
It’s to build a lifestyle that:
You can sustain
You actually enjoy
And doesn’t depend on perfect outcomes
How to Think About This in Real Life
Let’s simplify this into something practical.
Step 1: Eliminate Bad Debt
Before anything else:
Pay off credit cards
Avoid high-interest consumer debt
If you’re paying 15–25% interest, that’s the priority.
No investment reliably beats that.
Step 2: Build an Emergency Fund
You need liquidity.
A solid emergency fund:
Covers 3–6 months of expenses
Protects you from unexpected events
Keeps you from making bad decisions under pressure
And most importantly, if you use it, you replenish it.
Step 3: Automate Your Future
If you’re working:
Max out retirement accounts where possible
Make investing automatic
Remove decision fatigue
Once your future is handled and automated, everything else becomes easier.
Step 4: Decide Based on Your Situation
Now you can ask the real question:
What’s my mortgage rate?
What’s my risk tolerance?
What would help me sleep better at night?
What will I actually follow through on?
For some people:
Investing will make more sense
For others:
Paying off the mortgage will be the better move
Both can be right.
The Lifestyle Factor No One Talks About
There’s another layer to this.
As your life evolves, your expectations change.
You don’t want to go backward.
Think about how your lifestyle has grown over time:
First apartment
Better apartment
First house
Bigger house
Family, travel, experiences
Each step up becomes your new normal. And once you reach a certain level, you don’t want to give it up.
That’s what people are really afraid of.
Not running out of money completely…
…but having to scale back their lifestyle.
That’s why this decision matters.
The Bottom Line
So, should you pay off your mortgage or invest?
It depends.
Not in a vague way, but in a real, practical way:
Your interest rate
Your behavior
Your goals
Your tolerance for risk
Your stage of life
There is no perfect answer.
And that’s the point.
The goal isn’t to get every decision right.
It’s to:
Make thoughtful choices
Avoid big mistakes
Stay consistent over time
Because wealth isn’t built on one decision.
It’s built on hundreds of small ones, made well.
If You Want to Do This Right
Most people don’t need more information.
They need a clear plan.
One that:
Connects investments, taxes, insurance, and estate planning
Aligns with their actual life
Helps them make decisions with confidence
That’s the difference between guessing…
…and having a strategy.
If you want help putting that together, that’s exactly what we do through theBonfire Method. A coordinated plan so every decision works together, not against each other.
Because at the end of the day, it’s not about choosing between paying off your mortgage or investing.
It’s about building a financial life that actually works.
Most people think investing is about picking the right stock or timing the market, but that’s not what actually builds lasting wealth.
In reality, some of the biggest investing mistakes aren’t made by beginners. They’re made by high earners who are doing a lot of things right, but still feel like something is off.
They’re saving, they’re investing. They have a 401(k). On paper, everything looks solid.
And yet, there’s still uncertainty. Still hesitation. Still the question: am I actually doing this the right way?
After years of working with clients on financial planning, retirement strategy, and long-term investing, the patterns become clear. The issue usually isn’t effort. It’s structure. It’s mindset. And it’s a handful of common investing mistakes that quietly compound over time.
If you want to build real wealth and actually feel confident in your financial life, these are the mistakes worth paying attention to.
Keep reading, or if you prefer to listen or watch…check out the Podcast or full YouTube video.
Mistake #1: Thinking Investing Is About Picking Winners
One of the most common investing mistakes is believing that success comes from finding the next big stock.
High earners are often smart, analytical, and used to solving problems. So naturally, they approach investing the same way. They try to outthink it. They look for the edge. The opportunity others are missing.
But investing doesn’t reward that behavior consistently.
Real wealth is not built on a few big wins. It’s built on consistency over time. It’s built on a system that works regardless of headlines, trends, or market noise.
The sooner you shift from trying to pick winners to focusing on a repeatable strategy, the sooner things start to click.
Mistake #2: Relying Too Heavily on a 401(k)
A 401(k) is a great tool, but it’s not a complete strategy.
This is one of the most common investing mistakes high earners make. They do exactly what they were told, contribute consistently, and they take the match. And over time, they build a meaningful balance.
But then they realize most of their wealth is locked away.
That creates a lack of flexibility. If you want to retire early, invest in something outside the market, or simply have access to capital before traditional retirement age, your options become limited.
The solution isn’t to avoid a 401(k). It’s to avoid relying on it exclusively. Building wealth the right way means having multiple buckets, each serving a different purpose.
Mistake #3: Letting Too Much Cash Sit Idle
Another common investing mistake is holding excessive cash.
This often comes from a good place. It feels safe. It feels responsible. Especially for high earners who have worked hard to build what they have.
But over time, idle cash quietly loses value mostly due to inflation. It doesn’t grow. It doesn’t compound. And it doesn’t contribute to long-term wealth in any meaningful way.
The goal isn’t to eliminate cash completely. It’s to be intentional about how much you keep liquid and how much you put to work.
Mistake #4: Waiting Until Everything Feels “Perfect”
A lot of high earners delay making decisions because they want to get it right.
They want the right strategy, the right timing, the right plan.
The problem is that waiting is its own decision, and it usually costs more than getting started imperfectly.
Compounding only works if you give it time. The longer you wait, the more you give up.
You don’t need a perfect plan to start building wealth. You need a solid foundation and the willingness to move forward.
Mistake #5: Confusing Income With Financial Security
Making more money does not automatically lead to feeling secure.
This is one of the most overlooked investing mistakes. High earners often assume that as income increases, everything else will fall into place.
But without structure, higher income can actually create more complexity.
More accounts, more decisions, and more variables.
Financial confidence doesn’t come from income. It comes from clarity. It comes from knowing how everything fits together and why you’re doing what you’re doing.
Mistake #6: Ignoring the Role of Mindset
Many investing mistakes aren’t technical. They’re behavioral.
If someone grows up with a scarcity mindset, that doesn’t disappear when their income increases. It often carries forward into how they save, spend, and invest.
That can lead to hesitation, second-guessing, or an inability to enjoy what they’ve built.
On the flip side, overconfidence can lead to unnecessary risk and poor decisions.
Building wealth isn’t just about numbers. It’s about how you think about money and how that thinking shows up in your actions.
Mistake #7: Overcomplicating the Strategy
High earners are used to complexity in their professional lives, so they often assume investing needs to be complex as well.
It doesn’t.
In fact, complexity is often one of the biggest barriers to success.
The fundamentals are simple. Have a solid foundation. Invest consistently. Use the right mix of accounts. Stay disciplined over time.
It’s not flashy. But it works.
What Actually Builds Wealth Over Time
If these are the most common investing mistakes, what does the right approach look like?
It starts with a foundation.
An emergency fund that covers three to six months of expenses. No high-interest consumer debt. Stability before growth.
From there, it’s about using the tools available to you.
Taking advantage of employer matches. Building additional investment accounts that provide flexibility. Creating a structure that supports both long-term growth and short-term access.
And then, most importantly, staying consistent.
Investing month after month. Letting compounding do its job. Avoiding the temptation to constantly adjust based on what’s happening in the moment.
Why Consistency Beats Timing
Trying to time the market is one of the most common investing mistakes, even among experienced investors.
The problem is that it requires being right twice. When to get in and when to get out.
Consistency removes that pressure.
When you invest regularly over time, you smooth out the highs and lows. You participate in growth without needing to predict it.
And over the long run, that approach tends to outperform most attempts at timing.
The Difference Between Looking Wealthy and Being Wealthy
There’s a difference between looking successful and actually being financially secure.
Looking wealthy is often tied to visible things. Cars, homes, lifestyle.
Building wealth happens behind the scenes. It’s in the structure. The discipline. The decisions no one sees.
Many people who appear wealthy are financially fragile. And many people who are truly wealthy don’t feel the need to prove it.
Understanding that difference changes how you approach money.
What a Rich Life Actually Means
At some point, the definition of wealth shifts.
It moves away from accumulation and toward freedom.
The ability to make decisions without financial pressure. To spend time how you want. To create experiences with people you care about.
That’s what money is supposed to support.
Not just a number, but a life that you actually enjoy living.
Final Thoughts
Most investing mistakes don’t feel like mistakes in the moment.
They feel reasonable, they feel safe, and they feel like the right thing to do.
But over time, they add up.
The good news is that the solution isn’t complicated.
It’s about focusing on the fundamentals. Building the right structure. And staying consistent long enough for it to work.
If you can avoid the common investing mistakes high earners make and shift your approach toward clarity and simplicity, you put yourself in a completely different position.
Not just to build wealth, but to actually enjoy it.
Next Steps
Reading about investing mistakes is one thing. Fixing them in your own situation is another.
The Bonfire Method is designed to give you a clear plan across every part of your financial life, not just your investments. In 30 days, you’ll know exactly where you stand and what to do next.
If you’re ready to get out of the guesswork and into a real strategy, you can apply here.
One of the biggest mistakes people make in investing is believing success comes from constant attention. Checking accounts daily. Tweaking allocations weekly. Stressing over timing.
In reality, the most successful long-term investors tend to do the opposite. They build a solid structure, automate their savings, and let consistency do the heavy lifting.
As we enter a new year, 2026 contribution limits bring fresh opportunities to refine that structure. With higher limits across retirement and health savings accounts, now is the ideal time to reset your plan, automate contributions, and move forward without friction.
This guide walks through what changed for 2026, why automation matters, and how to set up your accounts so your wealth grows quietly in the background.
Why Automation Is the Foundation of Smart Investing
Before diving into numbers, it is worth addressing the philosophy behind them.
The most important part of investing is not picking funds or predicting markets. It is ensuring money goes into the system consistently.
When savings are automated, they function like a tax. The money moves before you have a chance to second-guess it. You adapt your lifestyle around what remains, not around what you hope to save later.
This matters even more during the accumulation phase, which includes anyone who has not yet retired. During this stage, the goal is simple: build wealth steadily without relying on motivation or memory.
Automation removes friction, decision fatigue, and emotional interference. Once set correctly, your plan requires attention only once a year.
Why the Start of the Year Matters
The beginning of the year is the best time to review and update contributions. New limits take effect. Payroll systems reset. Habits are easier to establish.
Instead of adjusting contributions throughout the year, a more effective approach is to:
For 2026, the IRA contribution limit has increased to $7,500. This is a $500 increase from the prior year.
Age 50 and Older
Those age 50 and over receive a catch-up contribution of $1,100, bringing the total allowable contribution to $8,600 for 2026.
These limits apply whether you contribute directly to Traditional IRA, a Roth IRA if eligible, or use a Backdoor Roth strategy due to income restrictions.
Important Timing Note
If you have not yet fully funded your 2025 IRA or Roth IRA, you still have time. Contributions for the prior year can be made up until April 15, 2026.
This creates a short window where you can:
Catch up on 2025 contributions
Adjust your automation for 2026
Ensure both years are fully optimized
2026 Contribution Limits for 401(k), 403(b), and Other Qualified Plans
Employer-sponsored retirement plans saw meaningful increases for 2026.
Under Age 50
The maximum salary deferral limit is now $24,500, up $1,000 from the previous year.
This applies whether contributions are made to a Traditional 401(k) or a Roth 401(k), if your plan offers both options.
Age 50 and Older
The standard catch-up contribution for those over age 50 is now $8,000, an increase of $500.
This brings the total allowable contribution to $32,500 for 2026.
High Income Catch-Up Rule
New rules require that certain high earners direct catch-up contributions into the Roth portion of their 401(k). While this does not reduce how much you can save, it does affect tax treatment.
For many high earners, this requirement actually enhances long-term flexibility by increasing tax-free growth in retirement.
The Special “Super Catch-Up” for Ages 60 to 63
One of the more nuanced updates within the 2026 contribution limits involves individuals aged 60 through 63.
During these specific years only, eligible participants can make a $11,250 catch-up contribution, instead of the standard $8,000.
This enhanced catch-up is available for three years only. Age 59 does not qualify. Age 64 does not qualify.
If you fall within this window, it is important to take advantage of it. These years offer a unique opportunity to accelerate retirement savings at a time when income is often at its peak.
SIMPLE IRA Contribution Limits for 2026
For individuals working at smaller companies that offer SIMPLE IRAs, contribution limits also increased.
Under Age 50
The salary deferral limit is now $17,000.
Age 50 and Older
Those age 50 and above can add a $4,000 catch-up, bringing the total to $21,000.
While SIMPLE IRAs have lower limits than 401(k) plans, they remain a valuable tool, especially when paired with employer contributions.
Do Not Leave Employer Match on the Table
Employer matching contributions are one of the most overlooked wealth-building tools.
If your employer offers a match, it is critical to contribute at least enough to receive the full amount. Failing to do so is effectively leaving compensation behind.
In many cases, employer contributions are immediately vested, meaning they belong to you right away. Always review your plan’s summary description to confirm vesting rules.
At a minimum, contributions should be set to capture the full match before allocating savings elsewhere.
2026 Contribution Limits for Health Savings Accounts (HSA)
Health Savings Accounts remain one of the most powerful planning tools available due to their unique tax treatment.
Money contributed to an HSA:
Goes in tax-free
Grows tax-free
Can be withdrawn tax-free for qualified medical expenses
2026 HSA Limits
Individual coverage: $4,400
Family coverage: $8,750
Age 55 and Older
Those age 55 and above can contribute an additional $1,000 catch-up.
Unlike retirement accounts, HSA funds are not use-it-or-lose-it. Balances roll forward indefinitely and can be invested for long-term growth.
For eligible individuals, an HSA can function as both a healthcare fund and a supplemental retirement account.
How to Set Up Automation the Right Way
Once you know the 2026 contribution limits, the next step is execution.
A simple approach looks like this:
Decide which accounts you are funding
Identify the maximum contribution for each
Divide the total by the number of paychecks or months
Set automatic contributions
Ensure investments are automatically allocated
For example, if you plan to max a $24,500 401(k) over 12 months, contributions should be set to approximately $2,041 per month.
This method uses dollar-cost averaging, which spreads investment timing across the year and reduces emotional decision-making.
Why This Approach Works Long Term
When automation is in place, investing becomes boring. That is a good thing.
You avoid trying to time markets, you avoid emotional reactions, and you avoid procrastination.
Years later, when you look back, the results often feel surprising. Not because of extraordinary decisions, but because of ordinary ones repeated consistently.
The goal is not perfection. It is reliability.
Final Checklist for 2026
As you move into the new year, consider the following:
Catch up on any remaining 2025 IRA or Roth contributions
Adjust 401(k), IRA, Roth, SIMPLE IRA, and HSA automation
Confirm employer match requirements
Ensure investments are allocated according to your plan
Schedule a reminder to revisit everything next January
When to Get Professional Guidance
Contribution limits are only one piece of the puzzle. Tax strategy, Roth eligibility, income thresholds, and long-term goals all influence how these tools should be used.
If you have questions about how the 2026 contribution limits apply to your specific situation, working with an advisor can help ensure your plan is aligned and efficient.
At Bonfire Financial, we help clients design systems that work quietly in the background so they can focus on life, not account maintenance.
Next Steps
Wealth is rarely built through constant effort. It is built through thoughtful setup. If you would like help aligning your accounts with the 2026 contribution limits and automating your strategy, we invite you to schedule a call with our team to review your plan.
The start of a new year is one of the best opportunities you get to reset, realign, and simplify your financial life. The goal is to spend a short, focused window of time putting the right systems in place so the rest of the year runs smoothly.
Whether you are still saving for retirement or already retired and managing distributions, this guide walks through the most important financial moves to make at the beginning of the year.
Most financial stress does not come from lack of knowledge. It comes from lack of structure.
When savings, investments, spending, and withdrawals are not clearly set up, everything feels harder than it needs to be. You end up reacting instead of planning.
The goal of these new year financial tips is simple:
Automate what can be automated
Review what actually matters
Make small adjustments that create long-term impact
Free up mental energy for the rest of your life
If done correctly, you should not feel the need to constantly check accounts, worry about missing deadlines, or scramble at the end of the year.
Tip 1: Reset Your Financial Mindset for the Year
Before touching any accounts, take a step back.
The new year is not about perfection. It is about alignment.
Ask yourself:
What do I want my money to do for me this year?
Do I want more simplicity, more flexibility, or more growth?
What caused financial stress last year?
Clarifying this first helps ensure your financial decisions actually support your real life.
Tip 2: Automate Your Savings First
If there is one principle that matters most, it is automation.
Automation removes emotion, procrastination, and decision fatigue.
If you are still working and saving for retirement:
Review your 401k or employer plan contribution percentage
Increase contributions if your income has increased
Confirm contributions restarted correctly for the new year
If you crossed a new age threshold:
Age 50: Confirm catch-up contributions are enabled
Ages 60–63: Review enhanced catch-up contribution rules if applicable
Once automated, savings happen without ongoing effort.
Planning early creates options. Waiting removes them.
Tip 14: Coordinate With Professionals Early
January is one of the best times to talk with advisors.
Consider:
Meeting with your financial advisor, also a good time to make sure they are a fiduciary fee-only advisor
Checking in with your CPA before tax season peaks
Reviewing any new tax rules or planning opportunities
Early conversations are calmer and more productive.
Final Thoughts
Strong financial planning is not built on constant action. It is built on a thoughtful structure.
When your savings, investments, spending, and distributions are set up correctly, your financial life runs quietly in the background. You are not reacting to markets, scrambling at year-end, or constantly second-guessing decisions. The work is done once, and the benefits show up all year long.
These new year financial tips are about building that kind of structure. Automating what can be automated. Reviewing what actually matters. Making thoughtful adjustments now so you are not forced into rushed decisions later.
The most successful financial plans are not built on constant activity. They are built on clarity, discipline, and systems that allow you to focus on the parts of life that matter more than money.
If you spend a short amount of time at the beginning of the year putting this framework in place, you give yourself something valuable in return: confidence, flexibility, and peace of mind for the months ahead.
That is what it means to truly jump start the year.
Next Steps
If the idea of a quieter, more intentional financial plan resonates, a conversation can help turn that framework into something personal and actionable.
Step back, review where things are today, and make sure your plan is built to support the life you want, not distract from it. No rushing. No pressure. Just clarity around what matters and how to structure your finances so they work in the background.
If this is the year you want confidence instead of constant decision-making, we’re here to help you get there.
We use cookies to improve and customize your browsing experience and analyze visitor behavior. By continuing to use this site, you consent to our use of cookies. ACCEPT
Privacy & Cookies Policy
Privacy Overview
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are as essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Thank You For Your Subscription
You’re in! Thanks for subscribing to our monthly newsletter. We will be sending you market updates, financial insights and inspiring travel ideas soon but in the meantime check out our blog, join us on Instagram or pop over to Pinterest.
Your Appointment Request has been Received
Thank you for reaching out! We are excited to learn more about you. Someone from our team will be in touch shortly.
Sign up now
Join us around the fire for monthly market updates, financial insights and inspiring travel ideas.
 Client Login