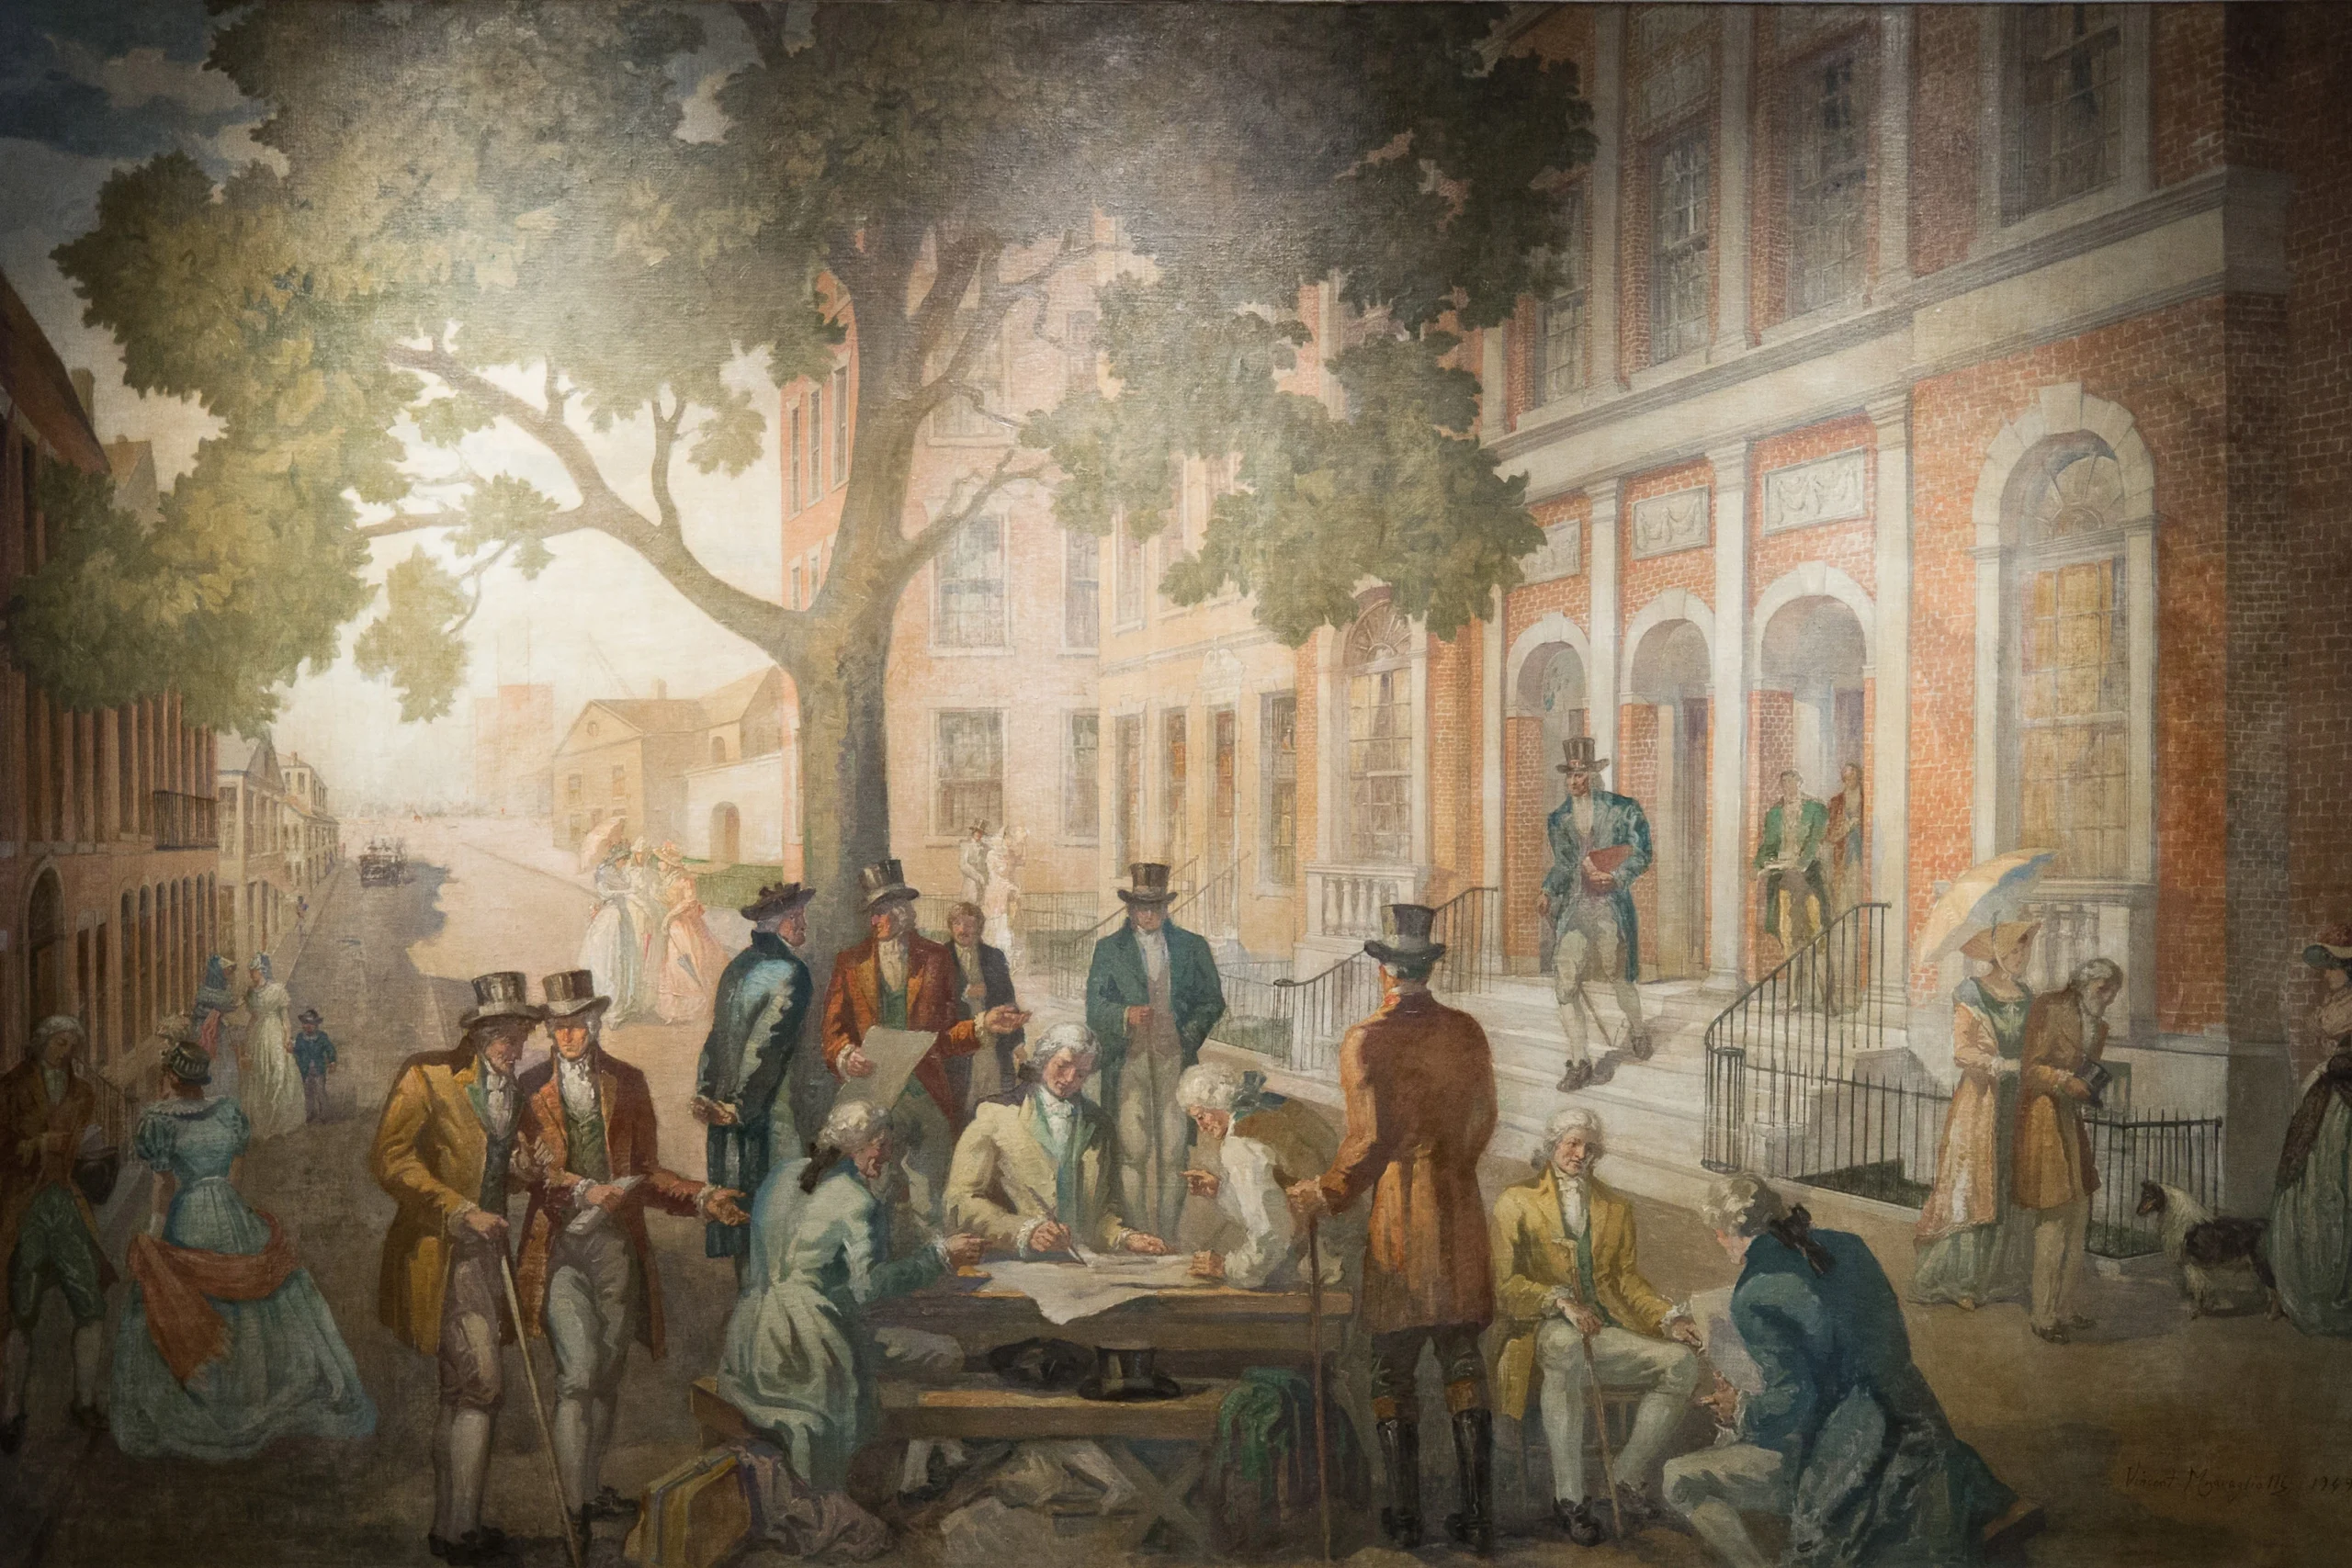
Investing in Alternatives: Are They Worth It?

Alternatives: Why Exclusive Doesn’t Always Mean Better

There’s a point when accumulating wealth changes the investment opportunities available to you.

Suddenly, financial firms begin offering private equity, hedge funds, private credit, and real estate deals. These exclusive investments promise access to opportunities beyond traditional stocks and bonds.

The pitch sounds compelling. Wealthy investors get access to sophisticated strategies, potentially higher returns, and opportunities unavailable to the average person.

But does investing in alternatives actually lead to better results?

Not necessarily.

Some alternative investments have delivered exceptional returns. Others have struggled to outperform simple, low-cost index funds, particularly after accounting for fees.

>> Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video. <<

What Are Alternative Investments?

Alternative investments include assets and strategies outside traditional publicly traded stocks, bonds, and cash.

Despite their sophisticated reputation, most alternatives serve familiar purposes. They allow you to own an asset, lend money, or pursue a strategy that differs from conventional investing.

Common examples include:

  • Private equity: Ownership in companies that don’t trade on public stock exchanges.
  • Venture capital: Investments in startups and early-stage businesses with significant growth potential.
  • Private credit: Loans made directly to businesses outside traditional public bond markets.
  • Private real estate: Ownership in properties through private investment partnerships or funds.
  • Hedge funds: Investment vehicles that may use strategies such as short selling, leverage, or derivatives.

These investments aren’t inherently better or worse than traditional options.

The difference often comes down to how managers structure the investment, calculate its value, charge fees, and restrict withdrawals.

Those details matter more than the label.

Why Do Wealthy Investors Choose Alternatives?

Exclusivity plays a powerful role in investing.

Many private investment opportunities require investors to meet specific income, net worth, or professional qualifications. Once you qualify, you may receive invitations to opportunities that previously seemed out of reach.

That access can feel like a reward for building wealth.

But qualifying for an investment doesn’t automatically make it a good investment.

Consider a conversation at a barbecue or golf course. Someone casually mentions earning 20% on a private investment.

Impressive, right?

Maybe. But several important details often go unmentioned.

Was that return earned over one year or several? Did the investor account for management fees? How did the investment perform compared with the S&P 500? Most importantly, could the investor actually withdraw the money?

Stories about impressive returns travel quickly. Conversations about disappointing performance, expensive fees, and restricted access to cash rarely receive the same attention.

That imbalance can make alternative investments appear more attractive than they really are.

The Yale Endowment: Why Investing Like the Wealthy Doesn’t Always Work

Much of the fascination with alternative investments traces back to Yale University.

In 1985, David Swensen began managing Yale’s endowment. He eventually shifted substantial portions of its portfolio toward private equity, venture capital, real estate, and other nontraditional investments.

For years, the approach produced remarkable results.

Institutional investors took notice. Investment firms followed, and wealthy individuals eventually began seeking similar strategies.

The reasoning seemed simple. If Yale could generate exceptional returns with alternatives, why couldn’t individual investors do the same?

There’s one significant problem with that assumption.

Yale’s investment needs look nothing like yours.

The university manages an endowment intended to last indefinitely. It can commit capital for decades and has access to investment managers that many individuals cannot reach.

Your financial life operates on a different timeline.

You may need money for retirement, a home purchase, family expenses, or unexpected events. Even if you have substantial wealth, access to that money still matters.

An investment strategy that works for a perpetual endowment may not serve someone funding the next 20 or 30 years of retirement.

Copying Yale’s investment categories doesn’t guarantee access to the same managers, opportunities, or returns.

Alternative Investments vs. Index Funds: Which Performs Better?

Alternative investments often attract attention because of their potential to outperform public markets.

But how have they actually performed?

Private Equity

Private equity has historically delivered strong returns during certain periods. Some funds have significantly outperformed publicly traded investments.

However, performance varies substantially across managers and investment periods.

In the periods examined for this discussion, broad private equity returns were roughly comparable to public markets over a longer horizon. More recently, public stocks held a meaningful advantage.

Investors also face an important challenge: Access to private equity doesn’t guarantee access to the best-performing funds.

Venture Capital

Venture capital offers the possibility of investing in the next transformative company before it becomes publicly traded.

The potential upside can be enormous.

Unfortunately, a relatively small number of successful investments often account for a disproportionate share of overall venture capital returns.

Many startups never become profitable, and unsuccessful investments can result in substantial losses.

Manager selection plays a critical role, while access to top-performing venture funds may remain limited.

Hedge Funds

Hedge funds provide another useful comparison.

In 2008, Warren Buffett entered a famous 10-year wager that a low-cost S&P 500 index fund would outperform a group of hedge funds.

During the financial crisis, the hedge funds initially held up better.

Over the full decade, however, the index fund won by a substantial margin.

One major reason was fees.

Hedge fund investors often pay several layers of investment management costs. Those expenses create a significant hurdle before investors receive their returns.

The lesson isn’t that every hedge fund or private investment performs poorly.

It’s that complexity and higher fees don’t guarantee superior performance.

A low-cost index fund can remain a formidable competitor, even against highly sophisticated investment strategies.

The Hidden Risks of Alternative Investments

Performance only tells part of the story.

Alternative investments often introduce risks that investors may not immediately recognize.

1. Lower Volatility Doesn’t Always Mean Lower Risk

Traditional stocks and index funds receive updated market prices throughout the trading day.

Private investments operate differently.

A private equity fund might estimate the value of its holdings quarterly rather than continuously.

As a result, the investment may appear relatively stable on your financial statement, even when broader markets experience significant volatility.

Cliff Asness, co-founder of AQR Capital Management, has described this phenomenon as volatility laundering.

The concept is straightforward: Infrequent valuations can make investment performance appear smoother than the underlying economic risk suggests.

A less volatile statement doesn’t necessarily indicate a safer investment.

Sometimes, it simply reflects a different method of measuring value.

2. Your Money May Be Locked Up for Years

Liquidity refers to how quickly you can convert an investment into cash.

With a traditional index fund, you can generally sell shares during market trading hours.

Private investments may impose considerably more restrictions.

Some require multiyear commitments. Others allow withdrawals only during specified periods or limit how much investors can redeem.

These restrictions can serve legitimate purposes.

A real estate fund, for example, may need to prevent investors from forcing rapid property sales during unfavorable market conditions.

Still, what protects the fund can create problems for the individual investor.

If you need money during retirement, an investment you cannot easily sell may offer little practical value.

3. Higher Fees Can Reduce Your Returns

Alternative investments frequently charge multiple layers of fees.

Depending on the structure, investors may pay management fees, performance-based compensation, administrative expenses, and additional costs.

Each expense reduces the money available to compound over time.

Consider a hypothetical $1 million investment with annual expenses of 2.5%.

That’s $25,000 in fees every year, assuming the same investment value.

A low-cost index fund might charge only a few hundred dollars on an equivalent balance.

The alternative investment must generate enough additional value to justify that difference.

And remember, fees don’t disappear when performance disappoints.

Investment returns fluctuate. Many ongoing expenses remain.

When Do Alternative Investments Make Sense?

Despite these concerns, alternative investments can serve a legitimate purpose.

Certain strategies offer access to different sources of return, specialized income opportunities, or investments unavailable through public markets.

The important question isn’t whether an investment sounds sophisticated.

It’s whether it improves your overall financial strategy.

Before investing in alternatives, consider four questions.

1. What does this investment provide that I can’t get elsewhere?

An alternative should offer a meaningful benefit compared with cheaper, simpler, and more liquid investments.

2. What specific purpose will it serve?

Does the investment create income, provide diversification, or offer a different source of potential growth?

3. Are the expected benefits worth the fees?

Evaluate all expenses, including management fees, performance compensation, and other fund costs.

4. Do I understand the investment and its risks?

Know what you own, how the manager determines its value, what could cause losses, and when you can access your money.

If an investment cannot pass these tests, exclusivity alone isn’t a reason to purchase it.

Where Do Alternatives Fit in a Retirement Portfolio?

Retirement planning adds another consideration to investing in alternatives.

The purpose and timing of your money matter just as much as potential returns.

At Bonfire Financial, we think about investment needs through three broad time horizons.

Money Needed Within Two Years

This money should prioritize stability and accessibility.

Near-term living expenses, planned purchases, and emergency reserves shouldn’t depend on investments that restrict withdrawals.

Money Needed in Three to Seven Years

These assets have more time to grow, but they still require an appropriate balance between risk and accessibility.

Investments with extended lockups may not align with these needs.

Money Needed in Eight Years or Longer

Longer-term investments have greater flexibility.

For investors with adequate liquidity and a specific investment objective, this portion of the portfolio may provide room for carefully selected alternatives.

Even then, alternatives should generally support the overall strategy rather than become its foundation.

For many investors, a diversified portfolio of traditional, low-cost investments may already provide everything they need.

Are Alternative Investments Worth It?

The appeal of alternative investments is understandable.

They offer access to exclusive opportunities, sophisticated strategies, and the possibility of attractive returns.

But investing isn’t about proving how sophisticated your portfolio can become.

It’s about making your money work toward your goals.

For many investors, the right allocation to alternatives may be zero.

Others may benefit from a modest allocation when they have sufficient liquidity, a long investment horizon, and a clear reason to accept additional complexity.

Neither approach should depend on exclusivity or status.

As your wealth grows, you’ll likely encounter more investment opportunities. That doesn’t mean every new opportunity deserves a place in your portfolio.

Sometimes, the simplest investments remain the most effective.

And if added complexity can’t demonstrate its value, boring wins.

Make Your Investments Work for Your Retirement

A more complicated portfolio doesn’t always mean a better retirement. What matters is having an investment strategy that supports the life you want to live.

The Bonfire Method brings your investments, taxes, income, and retirement goals together into one coordinated strategy.

4 meetings. 30 days. One complete retirement strategy.
Financial Advisor vs. Fiduciary: Why Wall Street Rebranded the Stockbroker

What a Fiduciary Really Means for Your Financial Advice

Today, you can buy a stock from your phone in seconds.

No broker. No phone call. No paper certificate. In many cases, no trading commission.

That sounds normal now. For most of Wall Street’s history, it would have been unthinkable.

There was a time when buying a stock required calling a stockbroker, who contacted someone on a trading floor to execute the transaction. The broker controlled access to the market. That access was valuable, and Wall Street built an enormous industry around selling it.

Then technology made access nearly free.

The stockbroker should have disappeared with it.

Instead, something more interesting happened.

The title changed.

Stockbrokers became financial consultants. Financial consultants became financial advisors. Today, millions of investors assume the person sitting across from them is there primarily to provide advice.

But the history of the financial industry created an important distinction that still exists today: financial advisor vs. fiduciary.

Understanding that difference may tell you more about your advisor than the title printed on a business card ever will.

>> Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video. <<

It Started Under a Tree

The story goes back to May 17, 1792. Twenty-four stockbrokers gathered under a buttonwood tree near Wall Street and signed what became known as the Buttonwood Agreement.

Buttonwood-Agreement-Financial-Advisor-Fiduciary-History

It contained two basic promises. The brokers agreed to charge a minimum commission, and they agreed to give preference to one another when conducting business.

That agreement helped lay the foundation for what eventually became the New York Stock Exchange.

More importantly, it established the basic economics of the brokerage business.

Brokers got paid when transactions happened. No transaction meant no commission.

For generations, that model made sense because investors couldn’t easily access financial markets without a broker.

Then everything started to change.

When Advice Became a Different Business

The stock market crash of 1929 ushered in a new era of financial regulation.

Congress passed the Securities Act of 1933 and the Securities Exchange Act of 1934. Then, in 1940, lawmakers passed the Investment Advisers Act.

That law helped establish a distinction that still matters today.

  • A broker facilitates transactions.
  • An investment adviser provides advice.

Those roles can come with different responsibilities to the client.

The concept of a fiduciary sits at the center of that distinction.

A fiduciary has a duty to put the client’s interests ahead of their own. That sounds like an obvious requirement for anyone giving financial advice, but the financial industry did not develop around a single standard.

Instead, two models grew alongside each other.

  • One focused on selling financial products and completing transactions.
  • The other focused on providing ongoing advice under a fiduciary standard.

From the outside, those professionals could look remarkably similar.

  • Same office.
  • Same suit.
  • Same industry.
  • Very different obligations.

Wall Street Saw the Conflict Early

Even some of Wall Street’s biggest names recognized the tension between advice and commissions.

Charles Merrill, one of the founders of Merrill Lynch, famously put brokers on salary rather than paying them based entirely on transactions.

The idea was simple.

If someone’s compensation increases every time a client trades, compensation can influence the advice that person gives.

Removing the transaction incentive could reduce that conflict. The model didn’t become the industry’s permanent standard.

Commission-based brokerage remained a powerful part of Wall Street for decades.

Then the economics underneath it began to collapse.

The Product Wall Street Sold Became Cheaper

For much of Wall Street’s history, brokers weren’t simply giving investors ideas.

They provided access.

By the late 20th century, technology started tearing down that barrier.

  • Stock quotes went electronic.
  • Index funds made broad market investing accessible.
  • Personal computers brought trading into homes.
  • Online brokerage accounts followed.

Then came one of the biggest blows to the traditional brokerage model.

In October 2019, Charles Schwab eliminated commissions on online stock and ETF trades. Major competitors quickly followed.

An activity that once supported an entire industry suddenly cost investors essentially nothing.

Think about what that meant.

For generations, Wall Street charged investors to execute trades.

Now investors could do it themselves from their phones.

When your core product becomes free, you need a new reason for clients to pay you.

That reason became advice.

The Stockbroker Didn’t Disappear. The Title Changed.

The language gradually shifted.

Stockbroker became financial consultant.

Financial consultant became financial advisor.

The new title sounded different because the service had changed. Investors increasingly wanted planning, guidance, tax strategy, retirement income advice, and help making decisions.

But the old brokerage model didn’t simply vanish.

Instead, the lines between brokerage and advice became harder for consumers to see.

That’s where the financial advisor vs. fiduciary conversation gets complicated.

Many financial professionals today hold more than one type of registration.

They may operate as an investment adviser in one situation and as a broker in another.

The industry calls this dual registration.

That means someone can provide fiduciary advice in certain parts of a relationship while also holding a brokerage registration that operates under a different regulatory framework, and get paid differently too.

The person sitting across from you may still carry the title “financial advisor” in both situations. That’s why the title alone tells you very little.

What Does Fiduciary Actually Mean?

A fiduciary financial advisor has a responsibility to put your interests ahead of their own when acting in a fiduciary capacity.

That distinction matters because financial recommendations can affect more than investment performance.

Consider the decisions investors make as they approach retirement:

  • Which accounts should you withdraw from first?
  • When should you claim Social Security?
  • Should you convert traditional retirement assets to Roth?
  • How should investment decisions coordinate with taxes?
  • Does an insurance product solve an actual planning need?
  • How should your estate plan fit with everything else?

These decisions rarely exist in isolation.

A true fiduciary relationship should begin with your financial life, not with a product someone wants to sell.

Why “Are You a Fiduciary?” May Not Be Enough

Here’s where things get tricky.

Ask a financial professional, “Are you a fiduciary?” and many can truthfully answer yes.

That doesn’t necessarily tell you whether they act as a fiduciary 100% of the time.

A dually registered professional may operate under a fiduciary standard in some circumstances while also maintaining a brokerage registration.

So the better question is more specific:

“Are you a fiduciary to me 100% of the time, in writing, without another registration that allows you to operate under a different standard?”

The answer should be easy to understand.

You shouldn’t need a law degree to figure out the relationship you’re entering.

Financial Advisor vs. Fiduciary: How to Check for Yourself

You don’t have to rely entirely on what an advisor tells you.

Financial professionals and advisory firms make regulatory disclosures available to the public.

Two documents can be particularly helpful.

Form ADV

Registered investment advisers file Form ADV.

It includes information about the firm’s business, services, fees, conflicts of interest, disciplinary history, and other important details.

Form CRS

Financial advisors and brokers may also provide Form CRS, short for Client Relationship Summary.

This document helps explain how the firm operates, what services it provides, how it gets paid, and potential conflicts.

Before hiring someone, read these documents. Look at how they receive compensation.

Check whether the person maintains a brokerage registration.

Then ask questions about anything you don’t understand.

Transparency shouldn’t require detective work.

Do You Even Need a Financial Advisor?

Not everyone does.

If you can build a diversified portfolio, stay invested through difficult markets, avoid chasing performance, coordinate your tax strategy, manage retirement withdrawals, and make major financial decisions without emotional interference, managing your money yourself may make sense.

You may also save a meaningful amount in advisory fees.

For everyone else, the question becomes whether professional advice delivers enough value to justify its cost.

A typical advisory fee around 1% can add up over time.

That means an advisor needs to provide value beyond simply choosing investments.

Good financial advice may include:

  • Tax planning
  • Retirement income strategy
  • Investment management
  • Behavioral coaching
  • Social Security planning
  • Risk management
  • Estate planning coordination
  • Withdrawal strategy
  • Helping you make decisions when markets get difficult

An advisor shouldn’t exist simply because investing feels complicated. The relationship should make your overall financial life better.

Why Fiduciary Advice Matters More Today

Ironically, investing has never been easier.

You can build a diversified portfolio for very little money, and use AI to help run numbers. Financial information is everywhere. Trading costs have fallen dramatically.

The harder part now is making all the pieces work together.

  • Investments affect taxes.
  • Taxes affect retirement income.
  • Retirement income affects Medicare premiums.
  • Estate decisions affect heirs.
  • Emotions affect nearly everything.

Modern financial advice should help coordinate those decisions. That’s also why understanding whether your advisor acts as a fiduciary matters.

You’re no longer paying someone simply to get you into the market.

You’re paying for judgment.

And when you’re paying someone for judgment, you should know whose interests come first.

The Stockbroker Evolved. Your Questions Should Too.

The financial industry has changed dramatically since 24 brokers met under a tree in 1792.

Paper certificates disappeared.

Trading floors became less important.

Commissions fell.

Technology gave individual investors access Wall Street once controlled.

Yet one question has survived every version of the industry:

Who does the person giving you financial advice ultimately work for?

The title on the business card won’t answer it.

“Financial advisor” can describe professionals working under very different business models.

Understanding the difference between a financial advisor and a fiduciary helps you look beyond the title and understand the relationship you’re actually entering.

Before you hand someone responsibility for decades of savings, ask how they’re registered, how they’re compensated, where conflicts could exist, and whether they will act as your fiduciary at all times.

You spent a lifetime building your wealth.

The advice you receive about it should put you first.

A Different Approach to Financial Advice

At Bonfire Financial, we believe financial advice should start with your complete financial life, not a product.

We operate as a fiduciary because we believe your interests should come first throughout the relationship.

Through the Bonfire Method, we bring investments, taxes, retirement income, insurance, and estate planning together into one coordinated strategy so you can see how each decision affects the rest. If you’re approaching retirement and want to understand whether all the pieces of your financial life are working together, learn more about the Bonfire Method.

Did I Make A Mistake Putting All My Money in a Traditional 401(k)?

401(k) Mistakes That Could Cost You More in Retirement

For years, I did exactly what many Americans do with their retirement savings. I put money into a Traditional 401(k), took the tax deduction, and assumed I would pay a lower tax rate once I retired.

The strategy sounded smart. In fact, it represented standard retirement advice for decades.

Then I started looking at the entire picture.

Instead of focusing only on the tax deduction today, I ran the numbers from the beginning of a career through retirement withdrawals and required minimum distributions. That exercise changed how I think about one of the most common 401(k) decisions.

The potential mistake isn’t saving in a 401(k). Saving consistently can create substantial wealth over time.

The question is when you want to pay the tax.

>> Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video. <<

Traditional 401(k) vs. Roth 401(k): What’s the Difference?

A Traditional 401(k) gives you a tax benefit today.

You contribute money before federal income tax, which can reduce your taxable income for the year. The money then grows tax-deferred until you withdraw it in retirement.

At that point, the IRS taxes your withdrawals as ordinary income.

A Roth 401(k) flips that arrangement.

You pay taxes on your income before contributing to the account. Once the money enters the Roth 401(k), qualified withdrawals can come out tax-free later.

Both accounts can hold the same investments. Both can experience the same investment growth. The major difference comes down to when you pay the tax.

That distinction may look small when you’re filling out a benefits enrollment form. Over several decades, it can become much more significant.

The 401(k) Tax Break Feels Pretty Good Today

Consider someone earning $200,000 a year and contributing $24,500 annually to a 401(k).

Using the assumptions from our example, choosing the Traditional 401(k) instead of the Roth reduces the person’s federal tax bill by about $5,880 for the year.

That’s roughly $490 every month.

Most people can find plenty of ways to use an extra $490.

Mortgage payments, vacations, groceries, braces, cars, kids, and everyday life can absorb that money quickly. Over a 35-year career, those annual tax savings total about $205,800 in additional take-home pay in our hypothetical example.

That benefit matters,  but it represents only one side of the equation.

The Bigger Question Comes When You Start Taking 401(k) Withdrawals

Here’s where one of the most overlooked 401(k) mistakes can occur.

People often focus heavily on the tax deduction they receive while working without thinking as carefully about how taxes may affect their withdrawals later.

Imagine contributing $24,500 every year from age 30 through age 65 while earning an average hypothetical return of 7%. Under those assumptions, you contribute $857,500 and reach retirement with approximately $3.39 million.

The Traditional and Roth accounts can reach the exact same balance if you contribute the same amount and invest the money identically.

However, those account balances don’t necessarily represent the same amount of spendable money.

  • The Roth saver has already paid income taxes on the money contributed.
  • The Traditional 401(k) owner still owes taxes when the money comes out.

A $3 Million 401(k) Isn’t Necessarily $3 Million You Can Spend

Suppose you retire and want to withdraw $10,000 per month.

With qualified Roth withdrawals, you can generally take out $10,000 and have $10,000 available to spend.

A Traditional 401(k) works differently.

Every taxable withdrawal adds to your ordinary income. In the hypothetical example from our analysis, withdrawing $120,000 per year produced roughly $16,400 in federal income taxes under the assumptions used.

That leaves approximately $8,600 per month after federal taxes.

Want the same $10,000 of monthly spending power as the Roth retiree?

You would need to withdraw closer to $11,800 per month in the example.

As a result, you may need to pull more money from the account to support the same lifestyle.

But Aren’t You Supposed to Be in a Lower Tax Bracket in Retirement?

Maybe. In fact, our hypothetical example assumes exactly that.

The person receives a deduction at a 24% marginal federal tax rate while working, then experiences an effective federal tax rate of roughly 14% on the modeled retirement withdrawal.

So the old advice wasn’t necessarily wrong.

It simply didn’t tell the entire story.

You receive the original tax deduction on the money you contribute.

Later, you pay taxes on the contributions plus decades of investment growth when you withdraw the money.

Think of it this way.

You avoided paying tax on the seed. Eventually, the IRS can tax the harvest.

That difference becomes increasingly important as the account grows.

Required Minimum Distributions Can Change the Equation Again

Traditional retirement accounts come with another consideration: required minimum distributions, commonly called RMDs.

Under current rules reflected in our example, someone born in 1960 or later generally starts RMDs at age 75. Those born from 1951 through 1959 generally begin at 73.

At that point, you don’t get to decide whether you want to withdraw money from the Traditional account.

The IRS requires a minimum amount each year.

Imagine someone reaching age 75 with an untouched Traditional 401(k) worth approximately $6.66 million.

In our hypothetical scenario, the first required distribution comes to roughly $270,800.

That creates approximately $57,300 in federal income tax under the assumptions we modeled.

A Roth 401(k), by contrast, does not require lifetime RMDs for the original owner under current rules.

That difference can create considerably more flexibility when you’re managing taxable income in retirement.

What If You’re Already in Your 50s?

This conversation becomes especially relevant for people who already have significant retirement savings.

You can’t go back and change how you contributed twenty years ago.

You can decide what you do with your next contribution.

Our second example looked at someone who reaches age 55 earning $200,000 with $1 million already accumulated inside a Traditional 401(k).

Instead of continuing to make Traditional contributions, that person directs the next ten years of contributions into the Roth side of the plan.

The additional taxes total about $58,800 over those ten working years in the example.

By age 65, the Roth portion grows to roughly $338,500.

At age 75, it reaches approximately $666,000.

Because less money remains subject to required distributions, the person’s first modeled RMD drops from roughly $184,000 to $157,000.

The first-year tax difference equals about $6,750 under the model. Over time, the gap continues to grow.

The bigger benefit may come from flexibility.

That retiree now controls a pool of Roth money that can potentially fund large expenses without increasing taxable income.

  • Maybe you want to buy a car.
  • Perhaps you’re helping a child purchase a home.
  • You could need money for travel, healthcare, home renovations, or another major expense.

Having both taxable and tax-free retirement accounts can give you more choices when deciding where that money comes from.

Why Do So Many People Ignore the Roth 401(k)?

Inertia plays a big role.

Vanguard’s How America Saves 2026 report found that 98% of the plans in its dataset offered a Roth feature at the end of 2025.

Only 18% of participants who had access to Roth directed any contributions toward it.

Other research cited in our analysis found a similar pattern.

Many employees simply continue using whatever retirement election they made when they first enrolled.

People change jobs, raise families, buy homes, and manage careers. Most don’t spend their free time rereading their employee benefits paperwork.

Unfortunately, a decision someone makes in their 20s or 30s can quietly continue for decades.

Is a Traditional 401(k) a Mistake?

Not necessarily.

A Traditional 401(k) can make sense in certain situations, particularly when someone’s current tax rate substantially exceeds the rate they expect to pay later.

Employer matching also matters.

If your employer offers a 401(k) match, taking advantage of that benefit often deserves priority regardless of whether the employer contribution lands in a Traditional or Roth account.

Your income, current tax bracket, future income needs, retirement date, Social Security strategy, investment assets, estate plan, and state taxes can all influence the decision.

That’s why framing this as simply “Roth good, Traditional bad” misses the point.

The bigger 401(k) mistake may come from making the choice once and never looking at it again.

One Question to Ask Before Your Next 401(k) Contribution

Instead of asking only:

How much can I save on taxes this year?

Consider another question:

How much control do I want over my taxes in retirement?

Retirement planning doesn’t stop with accumulating the biggest account balance possible. You also need to think about how you’ll eventually turn that balance into spendable income.

For years, I looked at my Traditional 401(k) and saw retirement savings. Now I see something slightly different.

Part of that balance belongs to me. Another portion represents a future tax obligation whose exact size I don’t yet know.

That’s why I approach my own contributions differently today.

The goal isn’t simply to build the biggest number on a statement. It’s to understand how much of that number you’ll actually get to use.

Your 401(k) Is Only One Piece of the Retirement Puzzle

Choosing between a Traditional and Roth 401(k) matters, but that decision shouldn’t happen in isolation.

Your retirement income, taxes, investments, Social Security, insurance, and estate plan all affect one another. A strategy that looks smart in one area can create unintended consequences somewhere else.

That’s why the goal isn’t simply to accumulate more money. It’s to build a retirement strategy that helps you understand what you have, what you’ll need, and how each piece works together.

The Bonfire Method brings those pieces into one coordinated plan. Over four meetings and 30 days, we look at your investments, taxes, retirement income, insurance, and estate planning to help you see the full picture before making major retirement decisions.

If you’re approaching retirement and wondering whether your current strategy is really working together, learn more about the Bonfire Method and see what your retirement plan may be missing.

Will AI Replace Your Financial Advisor?

Do You Still Need a Financial Advisor in the Age of AI?

Artificial intelligence can analyze investments, run retirement projections, compare tax strategies, and process enormous amounts of financial information in seconds.

That raises an obvious question: Do you still need a financial advisor?

AI already handles tasks that once required hours of research and analysis. Ask whether you can retire at 62, and AI can evaluate your income, investments, spending, Social Security, taxes, and life expectancy. It can test what happens if you retire earlier, spend more, convert part of an IRA to a Roth, or experience a major market decline.

Those capabilities will only improve.

But financial planning involves more than finding the mathematically correct answer. Your finances connect to your family, fears, goals, health, priorities, and behavior.

That distinction could determine what the financial advisor of the future looks like.

>> Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video. <<

AI Is Already Changing Financial Planning

Consider a couple wondering whether they can retire. The numbers say yes.

One spouse still hesitates because her father needed years of expensive care after retirement. Her husband wants to help their daughter buy a home nearby so they can spend more time with their grandchildren.

Suddenly, “Can we retire?” becomes a very different question.

What they really want to know is whether they can retire without becoming a financial burden while still helping their family.

AI can calculate the scenarios. A good financial advisor needs to uncover the question behind the question.

That human context matters because two people with identical portfolios may need very different financial plans.

One investor may value security after watching their parents struggle financially. Another may regret spending decades being overly cautious and want to enjoy more of their wealth while they remain healthy.

A spreadsheet can treat those investors the same.

A thoughtful advisor should not.

Information and Advice Aren’t the Same Thing

AI excels at processing information.

It can identify options, calculate tradeoffs, explain financial concepts, and evaluate more scenarios than a person could reasonably calculate alone.

Financial decisions rarely happen in perfect conditions, though.

Markets fall. Family members need help. Health changes. Priorities shift. Fear and excitement influence decisions.

That creates a gap between knowing what you should do and actually doing it.

Morningstar studied nearly 23,000 mutual funds and exchange-traded funds over the 10 years ending in 2025. The funds produced an aggregate annual return of 9.9%, while the average dollar invested earned 8.7%.

That represents a 1.2 percentage-point annual gap.

Morningstar notes that investor behavior does not explain every bit of that difference. People naturally add and withdraw money for legitimate reasons. Still, poorly timed buying and selling can keep investors from capturing the returns their investments generate.

In other words, owning a good investment does not guarantee a good investing experience.

Vanguard has also estimated that behavioral coaching from a financial advisor may add approximately 1.5 percentage points of value annually. That figure represents an estimate, not a guaranteed return.

The larger point matters more.

Sometimes an advisor creates value by preventing a client from making an expensive decision during the worst possible moment.

What Happens When Humans Use AI?

The future may not require choosing between a financial advisor and artificial intelligence.

Research suggests the combination could matter more.

One study partnered with a large European savings bank and compared three approaches to investment advice: AI alone, a human alone, and AI-generated recommendations reviewed by a human banker.

The experiment included 137 customers making real investment decisions.

Researchers found that human review did not reduce the quality of the AI-generated advice. Clients also followed the recommendations more closely when a person delivered AI-assisted advice, particularly when the investment involved more risk.

The human and AI combination increased adherence to the advice by 15.5 percentage points within the experiment.

Technology generated the analysis. A person helped make the recommendation usable.

That distinction matters because financial advice creates little value if someone never acts on it.

AI Can Make Professionals Better, But It Can Also Make Them Wrong

Another experiment involving 758 Boston Consulting Group consultants provides an interesting look at how AI affects professional work.

Consultants who used AI completed 12.2% more tasks and finished them 25.1% faster. On tasks suited to the technology, their performance improved by more than 30%.

The research did not specifically study financial advisors, so those numbers do not transfer directly to financial planning.

Still, the results show how AI can expand what a skilled professional can accomplish.

A financial advisor could use AI to evaluate more retirement scenarios, identify patterns across complicated financial information, prepare clearer explanations, or reduce repetitive analytical work.

Then the research uncovered an important problem.

When consultants received a task outside AI’s capabilities, those using AI became 19 percentage points less likely to reach the correct answer than consultants working without it.

Researchers described this uneven capability as the “jagged technological frontier.”

AI may solve one complicated problem extremely well and struggle with another that looks surprisingly similar.

The bigger danger comes from how convincing a bad answer can sound. An incorrect AI response may still appear polished, logical, and confident.

That means financial professionals need more than access to AI. They need enough experience and judgment to know when to question it.

Think of AI as a copilot, not an autopilot.

Do Investors Trust AI With Their Money?

Trust also changes depending on the financial question.

The FINRA Investor Education Foundation studied more than 1,000 American adults and found an interesting divide.

When participants evaluated projections about stock and bond performance, 34% trusted information from AI and 33% trusted information from a financial professional.

For general market information, the two sources essentially tied.

Personal advice produced a different result.

When participants evaluated portfolio-allocation recommendations, 37% trusted the financial professional compared with 30% who trusted AI.

As the decision became more personal, people placed greater trust in another person.

That suggests a natural division of labor.

AI can process information, perform calculations, and test possibilities at enormous speed. A qualified financial advisor can evaluate those results, apply them to a client’s actual life, and help determine which decision makes sense.

So, Will AI Replace Your Financial Advisor?

It may replace some of what financial advisors traditionally do.

If someone primarily provides investment reports, gathers information, or performs basic calculations, AI will continue to put pressure on the value of those services.

A strong financial advisor should offer much more.

They should understand what matters to you, identify risks you may overlook, explain your choices clearly, coordinate different parts of your financial life, and help you stay disciplined when emotions start driving decisions.

Technology can strengthen each of those capabilities when an advisor uses it correctly.

That leads to a better question than “AI or a financial advisor?”

Is your financial advisor using AI to give you better advice?

What Should You Expect From a Financial Advisor in the Age of AI?

Before deciding whether your advisor still provides enough value, consider three questions:

Are they acting as a fiduciary?

A fiduciary carries a responsibility to put your interests first.

Do they understand more than your numbers?

Your retirement plan should reflect your goals, family, concerns, priorities, and the life you actually want to live.

Are they using modern technology to improve your plan?

Ignoring AI makes little sense when the technology can help advisors analyze more possibilities and work more efficiently. Blindly trusting it makes equally little sense.

The strongest financial advisors may learn to do both.

They can use AI for speed, scale, and analytical power while applying human judgment before a recommendation reaches the client.

The Future of Financial Advice

AI probably will not eliminate great financial advisors.

It will change what clients should expect from them.

Calculations that once took hours may happen in seconds. Research will become easier. Scenario analysis will grow more sophisticated.

As technology handles more of that work, the human parts of financial planning may matter even more.

  • Judgment
  • Context
  • Accountability
  • Behavior
  • Trust.

You should not have to choose between better technology and a better human relationship.

The financial advisor of the future will need to provide both.

5 Things That Matter More Than Saving for Retirement

Saving for Retirement Is Only the First Step

For most of your working life, saving for retirement feels like the obvious priority. You earn money, contribute to your retirement accounts, invest consistently, and repeat the process year after year.

That strategy makes sense while you are building wealth. Eventually, though, something changes.

Your portfolio can reach a point where investment growth has a much larger impact on your future than the additional dollars you contribute each year. At that stage, continuing to save still has value, but other financial decisions may have a much greater effect on your retirement.

Taxes matter more. Investment risk carries bigger consequences. The timing of market returns becomes increasingly important. Even your own behavior can have a significant impact on whether your retirement strategy succeeds.

Here are five things that may matter more than simply saving more as your portfolio grows.

Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.

1. The Growth of Your Portfolio

Early in your investing journey, your contributions drive much of your progress.

If you have $100,000 invested and contribute another $20,000, that contribution represents a significant percentage of your portfolio.

The equation starts to change as your investments grow.

Consider a hypothetical $2 million portfolio earning an average 7% annual return. That portfolio could generate approximately $140,000 in growth during the year. A $3 million portfolio at the same hypothetical return could grow by about $210,000.

At $5 million, a 7% return would equal approximately $350,000.

These numbers illustrate an important concept: eventually your existing investments may contribute more to your wealth than the money you add each year.

Of course, investment returns fluctuate, and no portfolio earns the same return every year. The point is not to expect 7% annually. Instead, recognize how the relationship between contributions and portfolio growth changes as your assets increase.

You could call this the crossover point.

Once you reach it, finding another way to save an extra $10,000 or $20,000 each year may not have the same impact it once did.

That does not mean you should stop saving for retirement. It means your financial strategy needs to evolve.

2. Tax Planning

As your wealth increases, taxes can become one of the biggest factors affecting your retirement.

Many people spend decades asking one question:

  • How much more can I save?

A more valuable question may eventually become:

  • How much of what I have built can I keep?

Retirement accounts also have contribution limits. You can only put so much into a 401(k), IRA, Roth IRA, HSA, and other tax-advantaged accounts each year.

Tax planning creates a different opportunity.

Imagine that thoughtful tax strategies allow someone with substantial assets to reduce their annual tax burden by even 1% of their portfolio value. On a $2 million portfolio, 1% equals $20,000.

Keeping an additional $20,000 invested rather than losing it unnecessarily to taxes can create a meaningful difference over decades.

That is why retirement planning should eventually move beyond contributions.

Your strategy may need to consider questions such as:

  • Which accounts should you draw from first?
  • When could a Roth conversion make sense?
  • How might required minimum distributions affect your taxes later?
  • How will Social Security, pensions, investment income, and retirement withdrawals interact?
  • Could realizing income in one year reduce taxes in future years?

Saving builds the portfolio. Tax planning helps you preserve more of it.

3. Asset Allocation

Asset allocation can feel relatively abstract when your portfolio is small. It feels very different when you have accumulated several million dollars.

A major market decline on a $100,000 portfolio may hurt emotionally, but a similar percentage decline on a multimillion-dollar portfolio can represent hundreds of thousands or even millions of dollars.

That makes the amount of investment risk you take increasingly important.

Suppose someone reaches retirement with a $2 million portfolio invested aggressively because stocks performed well during the previous several years. If the stock market experiences a major decline, that investor could suddenly find themselves facing retirement with far fewer assets than expected.

The problem is not that stocks are inherently bad or that investors should avoid market risk. It comes from holding a portfolio that does not match your situation.

Your asset allocation should reflect three primary factors:

  1. Your time horizon. How soon will you need the money?
  2. Your risk tolerance. How much volatility can you handle without abandoning your strategy?
  3. Your financial goals. What does your portfolio actually need to accomplish?

Someone who will not touch their investments for 25 years has different needs than someone planning to retire next year.

Once your portfolio becomes substantial, the goal should not simply be maximizing returns.

You need the right amount of risk for the retirement you want.

4. Sequence of Returns Risk

Two retirees can earn the exact same average investment return and experience dramatically different outcomes.

Why?

Because the order in which those returns occur matters. This concept is known as sequence of returns risk.

Imagine saving for retirement, then retiring immediately before a major market decline. Your investments fall at the same time you begin withdrawing money to pay for retirement.

Now you face two forces working against the portfolio.

The market has reduced the value of your investments, and you are selling some of those investments to fund your lifestyle.

Those withdrawals leave fewer assets available to participate when the market eventually recovers.

Someone who experiences strong returns during their first several years of retirement may have a completely different outcome, even if both investors eventually earn similar average returns over a longer period.

That makes withdrawal planning essential.

Before retirement, you should know where your income will come from if markets decline.

A diversified account structure can help. Depending on your circumstances, you may have assets across traditional retirement accounts, Roth accounts, and taxable brokerage accounts.

Those different buckets can provide flexibility when markets or tax conditions change.

The goal is not to predict the next downturn. Nobody knows exactly when one will occur.

A better strategy prepares for the possibility before it happens.

5. Your Own Behavior

One of the greatest risks to a retirement portfolio may not come from taxes or the stock market. It may come from the investor.

When markets rise, investors often feel confident.

They may decide they can tolerate more risk. Some increase their stock exposure because recent returns look attractive.

Then the market falls.

Fear replaces confidence remarkably quickly.

Suddenly, the same investor who planned to “buy the dip” wants to sell everything.

Behavioral mistakes can create lasting financial consequences.

Investors commonly fall into patterns such as:

  • Chasing investments after strong performance
  • Selling during market declines
  • Constantly changing investment strategies
  • Taking more risk after markets rise
  • Becoming overly conservative after markets fall
  • Trying to predict short-term market movements

A strong retirement plan creates guardrails before emotions take over.

You decide how your portfolio should work while markets are calm. You establish rules for withdrawals, rebalancing, and risk management before volatility arrives.

Working with a financial professional can also add another layer of accountability. Sometimes having someone between you and a major financial decision helps prevent an emotional reaction from becoming an expensive mistake.

Saving for Retirement Is Only the First Phase

Saving for retirement remains important. But accumulating money represents only one part of a successful retirement strategy.

As your portfolio grows, your financial priorities should evolve with it.

Eventually, the bigger questions become:

  • How should your investments be structured?
  • What amount of risk should you take?
  • How can you manage taxes?
  • Where will retirement income come from during a market decline?
  • How can you prevent emotional decisions from derailing decades of work?

Those decisions may ultimately have a greater impact than squeezing another few thousand dollars into your portfolio each year.

The strategy that helped you build wealth does not automatically become the strategy that helps you preserve it.

The Bottom Line

There comes a point when saving for retirement becomes less about how much more you can contribute and more about how effectively you manage what you have already accumulated.

Portfolio growth begins doing more of the heavy lifting. Tax decisions become increasingly valuable. Asset allocation carries greater consequences. Sequence of returns risk becomes real as retirement approaches, and behavioral mistakes can undo years of disciplined investing.

That is when retirement planning needs to become more intentional.

You worked hard to build your portfolio. The next step is making sure your money, tax strategy, investments, and retirement income plan work together.

If you have built a substantial portfolio and want a second opinion on your retirement strategy, schedule a conversation with the Bonfire Financial team. We can review where you are today, identify potential gaps, and help you determine what needs to happen next.

Want to Retire Early? Do These 5 Things First

5 Things to Consider Before You Retire Early

The idea of retiring early can be incredibly appealing. More freedom. More time with family. More travel. More control over how you spend your days.

But deciding to retire early involves much more than reaching a certain number in your investment accounts.

You also need to understand how retirement could affect your taxes, Social Security benefits, healthcare costs, and investment strategy. Perhaps more importantly, you need to decide what you actually want your retirement years to look like.

Before you leave work behind, here are five important questions to consider.

Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.

1. Is Your Time More Valuable Than Earning More Money?

One of the hardest parts of retirement planning has nothing to do with spreadsheets. It comes down to deciding when you have enough.

Many people spend decades focused on accumulating wealth. They reach $1 million and want $2 million. They reach $2 million and start thinking about $5 million.

There is nothing inherently wrong with continuing to build wealth. However, there comes a point when the value of another dollar may matter less than the value of another healthy year.

We regularly see this contrast with retirees.

Some clients retire early without enormous portfolios and create fulfilling lives around travel, family, hobbies, and experiences. Others have more than enough money but continue postponing the things they say they want to do.

As people get older, their regrets rarely center around not working longer. More often, they wish they had traveled while they were healthy, spent more time with family, or enjoyed the freedom they had worked so hard to create.

If you want to retire early, start by asking a different question.

Instead of asking, “How much more can I accumulate?” ask, “What do I want this money to allow me to do?”

That answer can change the entire retirement conversation.

2. Should You Delay Social Security?

Retiring early does not necessarily mean claiming Social Security immediately. In many situations, delaying benefits can increase the amount you eventually receive each month.

That creates an important planning opportunity.

If you retire before claiming Social Security, you may be able to fund your lifestyle from other assets for several years while allowing your future benefit to grow. The right strategy depends on your assets, income needs, health, longevity expectations, and tax situation.

For someone with significant assets in an IRA or 401(k), delaying Social Security may also create an opportunity to strategically draw down tax-deferred accounts before other income sources begin.

There is no universal “best age” to claim Social Security.

The goal should be to coordinate Social Security with the rest of your financial plan rather than making the decision in isolation.

3. Take Advantage of the Tax Window After You Retire Early

The years immediately after retirement can create one of the most valuable tax-planning windows of your life. Your salary disappears, but required minimum distributions may still be years away.

That gap can potentially put you in a lower tax bracket than you experienced during your working years or may experience later in retirement.

This period may create opportunities for strategies such as Roth conversions.

For example, you might intentionally move money from a traditional IRA or 401(k) into a Roth IRA while your taxable income remains relatively low.

You will owe taxes on the conversion today, but the tradeoff may be worthwhile if it reduces future required distributions and creates more tax-free assets later.

That does not mean converting as much as possible.

Large conversions can push you into a higher tax bracket and potentially increase Medicare premiums through IRMAA once Medicare becomes relevant.

Good planning requires looking several years ahead.

Sometimes paying more tax today can reduce your lifetime tax bill. Other times, waiting makes more sense. You need to run the numbers.

4. Plan for Healthcare Before Medicare

Healthcare often becomes one of the biggest surprises for people who retire early.

Medicare generally does not begin until age 65.

If you stop working before then, you need a plan for covering the gap between employer-sponsored health insurance and Medicare eligibility.

That gap could last one year, three years, five years, or longer depending on when you retire.

Options may include coverage through the health insurance marketplace, a spouse’s employer plan, COBRA in some situations, or using available savings and HSA funds to help cover eligible healthcare expenses.

Whatever option you choose, build those costs into your retirement projections. Do not simply assume healthcare will work itself out.

Premiums, deductibles, prescriptions, and out-of-pocket expenses can add up quickly. Healthcare costs may also increase faster than many other household expenses.

If you want to retire early, healthcare deserves its own line item in your financial plan.

5. Change the Way You Think About Your Portfolio

Your investment strategy may need to change when your paycheck stops.

During your working years, your portfolio typically has one primary job: growth. You contribute to your 401(k), IRA, brokerage accounts, and other investments while continuing to earn income.

Market downturns can still hurt, but your paycheck helps support your lifestyle while your portfolio recovers.

Retirement changes that relationship. Once your investments begin funding your lifestyle, market declines can have a much larger impact. A 20% market drop feels very different when you are withdrawing money from the portfolio instead of adding to it.

That does not automatically mean becoming extremely conservative.

Your portfolio still needs enough growth to potentially support decades of retirement.

Instead, your allocation should reflect how much income you need from your investments, how much guaranteed income you receive, your risk tolerance, and how long your assets may need to last.

Someone with a pension that covers nearly all household expenses may invest very differently from someone who relies almost entirely on their portfolio.

The important point is simple.

The strategy that helped you accumulate your money may not be the same strategy you need once you retire.

So, Can You Retire Early?

There is no single portfolio balance that automatically means you are ready to retire early. Your decision depends on how your entire financial picture works together.

Before making the leap, look closely at:

  • What you want your retirement years to look like
  • When you should claim Social Security
  • How you can use your early retirement tax window
  • How you will pay for healthcare before Medicare
  • Whether your portfolio matches your new income needs

These decisions can matter just as much as the amount you have saved.

If you have spent decades building your wealth, retirement planning should help you transition from simply accumulating money to using that money intentionally.

You worked hard to build your portfolio.

Now the question becomes whether your financial plan gives you the confidence to use it.

Thinking About Retiring Early?

If you are considering an early retirement and wondering whether your savings, taxes, Social Security strategy, healthcare plan, and investments all work together, getting a second opinion can help.

At Bonfire Financial, we use the Bonfire Method to look at your full financial picture and help you understand how the different pieces of your retirement plan work together.

If you are thinking about retiring early, schedule a conversation with our team and find out whether your plan is ready for the next chapter.

5 Warning Signs You’re Not Ready to Retire

Think You’re Ready to Retire?

You’ve built the portfolio. Your think your numbers work. Your spouse is ready. On paper, retirement might look like the obvious next step.

But having enough money to retire and having a plan that is actually ready for retirement are two different things.

For high earners especially, the transition from earning a paycheck to living off your assets can expose risks that were easy to overlook during your working years.

Before you are ready to retire, here are five warning signs worth addressing.

Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.

1. Too Much of Your Wealth Is Concentrated in One Investment

Concentrated investments can be incredibly effective for building wealth. A successful company stock, a high-growth investment, or equity compensation may have played a major role in getting you where you are today.

The problem is that the same concentration that helped build your wealth can become a much bigger risk once you retire.

It is not unusual for someone approaching retirement to have 15%, 20%, or even significantly more of their portfolio tied to a single company or investment.

While you are working, market volatility may be easier to tolerate because you are still earning income and contributing to your accounts. Once that paycheck disappears, significant swings in your portfolio can feel very different.

Retirement planning requires thinking beyond growth. You also need to consider how much risk you can realistically afford to take when your portfolio becomes a primary source of income.

2. Your Portfolio Is Still Built for Accumulation

The portfolio that helped you build wealth may not be the same portfolio you want to carry into retirement.

During your working years, you may be able to tolerate an aggressive allocation because you have time to recover from market downturns. You also have income coming in, which reduces your dependence on the portfolio.

Retirement changes that equation.

Once you begin withdrawing money, you need to think about diversification, risk tolerance, your time horizon, and how much income you will need from your investments. A portfolio that remains heavily weighted toward aggressive or highly correlated investments may create more volatility than you are comfortable with once withdrawals begin.

The goal is not necessarily to eliminate risk. It is to make sure the level and type of risk you are taking fits the next stage of your financial life.

3. You Haven’t Calculated Your Real Retirement Tax Bill

One of the most common assumptions about retirement is that taxes will automatically go down.

For some retirees, they do.

For high earners with substantial assets, however, the reality can be much more complicated.

Retirement income can come from a variety of sources, including:

  • Traditional IRAs and 401(k)s
  • Brokerage accounts
  • Dividends
  • Real estate income
  • Pensions
  • Social Security
  • Other investments

Many of those sources can create taxable income.

If you need significant annual cash flow to maintain your lifestyle, your tax bill in retirement may remain much higher than expected.

This is why the years surrounding retirement can be so important for tax planning. Decisions about when to take distributions, when to complete Roth conversions, and how to manage future required minimum distributions can have consequences that extend decades into retirement.

The question should not simply be, “How much money do I have?”

It should also be, “How much of that money will I actually get to spend after taxes?”

4. You Don’t Know Your Real Retirement Burn Rate

How much do you actually expect to spend once you retire?

The answer may be higher than you think.

People often assume their spending will decline after they stop working. But the first several years of retirement can be some of the most active and expensive years.

You finally have the time to travel. You may take longer vacations, visit family more often, tackle home projects, pursue hobbies, or start checking items off your bucket list.

That is not necessarily a problem. In many ways, that is exactly what the money was built for.

The problem is failing to plan for it.

Retirees can spend substantially more during the early years of retirement because they finally have the combination of time, money, and health to enjoy it.

Your retirement plan should reflect the life you realistically intend to live, not an artificially low spending number that makes the projections look better.

Understanding your actual burn rate gives you a much clearer picture of whether your portfolio is truly prepared to support your lifestyle.

5. You Don’t Have a Withdrawal Sequence Plan

You have a traditional IRA, a brokerage account, and Roth assets.

Which one do you spend first?

That decision can be far more important than many retirees realize.

A common approach is to spend down taxable brokerage assets first, then move to traditional retirement accounts, and save Roth assets for last. While that may work in some situations, retirement income planning is rarely that simple.

The better decision can change from year to year.

One year, it may make sense to take more from a brokerage account. Another year, you may intentionally withdraw from an IRA while remaining within a particular tax bracket. In some cases, using taxable assets may create room for a Roth conversion that helps reduce future required minimum distributions.

Your income needs, tax brackets, deductions, market conditions, and future RMDs can all affect the decision.

That is why a withdrawal strategy should not be something you create once and forget.

It should be actively managed throughout retirement.

Retirement Readiness Is More Than a Portfolio Number

A large account balance can create a sense of security, but retirement planning is not simply about reaching a number.

You need to understand how your investments, taxes, spending, and withdrawal decisions interact once you stop earning a paycheck.

Before you retire, ask yourself:

  • Is too much of my wealth concentrated in one investment?
  • Is my portfolio still positioned as though I am 10 or 20 years away from retirement?
  • Do I understand what my tax bill could actually look like?
  • Have I realistically modeled what I plan to spend?
  • And do I know which accounts I should withdraw from each year?

For high earners approaching retirement, these decisions can have a significant impact on how efficiently your wealth supports you over the next 20 or 30 years. Without addressing these areas, wealth can gradually be lost to taxes, market risk, and lifestyle spending that was not properly planned for.

The objective is not simply to make it to retirement. It is to enter retirement with a plan designed for what comes next.

If you’re approaching retirement and want to make sure all the pieces of your financial life are working together, schedule a conversation with our team. Through the Bonfire Method, we look at your investments, taxes, income, insurance, and overall retirement strategy together to help identify gaps and build a more coordinated plan for what comes next.

5 Retirement Tax Planning Moves That Can Lower Your Tax Bill

Smarter Retirement Tax Planning

You can spend decades building your retirement savings and still lose more than necessary to taxes once you start taking money out.

The problem often comes down to one decision: which account should you withdraw from first?

Many retirees have money spread across several types of accounts. You may have a traditional IRA or 401(k), a taxable brokerage account, and a Roth IRA. Each account receives different tax treatment.

That gives you options. It also creates opportunities to make expensive mistakes.

A common rule of thumb says to spend from taxable accounts first, tax-deferred accounts second, and Roth accounts last. That approach can work in some situations. However, following the same withdrawal order every year may cause problems later.

For some retirees, a better approach involves coordinating withdrawals with tax brackets, Roth conversions, required minimum distributions, Medicare premiums, and other parts of their financial plan.

That is where retirement tax planning becomes important. Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.

Why Your Retirement Withdrawal Strategy Matters

Saving enough for retirement is only part of the equation.

Once your paycheck stops, you need to create income from the assets you spent years accumulating. How you create that income can affect your tax bill for decades.

Imagine spending down your taxable brokerage account early in retirement while leaving a large IRA untouched.

That IRA may continue growing tax-deferred. Eventually, required minimum distributions, or RMDs, can force increasingly large amounts of taxable income onto your return.

At that point, you have fewer choices.

A more flexible strategy may involve taking money from several account types over time instead of completely draining one before touching another.

The goal is not simply to pay the least tax this year.

Instead, good retirement tax planning looks at your lifetime tax bill.

The 3 Phases of Retirement Tax Planning

Retirement does not create one single tax-planning environment.

Your opportunities can change dramatically as you move through different stages of retirement. The transcript breaks retirement withdrawals into three general phases.

Phase 1: Retirement Before Medicare

If you retire before age 65, the years between your final paycheck and Medicare eligibility can create valuable planning opportunities.

Your earned income may drop significantly during this period. Social Security may not have started yet either. As a result, you could find yourself in a lower tax bracket than you occupied during your working years.

That lower-income window may create opportunities to withdraw money from tax-deferred accounts or complete Roth conversions at more favorable tax rates.

Not everyone gets this window. Someone who retires at 65 may move directly into the next phase.

For those who retire earlier, however, these years can become an important part of the overall tax strategy.

Phase 2: Medicare Begins, but RMDs Have Not

The next phase generally begins around age 65 and continues until required minimum distributions start.

You may still have opportunities for Roth conversions and strategic IRA withdrawals. However, another factor now enters the picture: Medicare.

Higher income can trigger Medicare Income-Related Monthly Adjustment Amounts, commonly called IRMAA.

IRMAA uses income from prior tax years when determining certain Medicare premiums. That means a large Roth conversion or IRA withdrawal today could affect what you pay for Medicare later.

This does not automatically make a Roth conversion a bad idea.

Sometimes paying a higher Medicare premium now could still make sense if the strategy reduces larger taxes in future years. The important part is understanding the tradeoff before making the decision.

Phase 3: Required Minimum Distributions Begin

Eventually, RMDs enter the equation.

At that point, the government requires you to withdraw a portion of your tax-deferred retirement accounts each year.

Those distributions generally create taxable income whether you need the money for living expenses or not. Planning during the earlier phases can make a significant difference here.

If you reduced your tax-deferred balances strategically before RMDs began, your future required distributions may become easier to manage. You may also have more flexibility to fund additional spending from taxable or Roth accounts.

The work you do before this phase can shape your tax situation for the rest of retirement.

5 Retirement Tax Planning Moves to Consider

Understanding the phases helps establish the framework. The next step involves putting that framework into practice.

Here are five strategies that may help retirees manage taxable income and preserve more flexibility.

1. Strategically Fill Lower Tax Brackets

Retiring often causes taxable income to fall.

Rather than automatically avoiding taxes during those years, it may make sense to intentionally recognize some income while your tax rate remains relatively low.

For example, you could withdraw money from a traditional IRA or convert part of an IRA to a Roth.

You would pay taxes today. In exchange, you may reduce the amount sitting in tax-deferred accounts before RMDs begin.

The key involves looking beyond the current year.

Paying tax at a lower rate today could make more sense than waiting and potentially paying a higher rate later.

Your available tax bracket depends on your income, deductions, filing status, and other factors, so the right amount will vary from person to person.

2. Look for Capital Gains Harvesting Opportunities

A lower-income year may also create opportunities inside a taxable brokerage account.

Many long-term investors accumulate positions with significant capital gains. Selling those investments can trigger capital gains taxes.

However, your tax rate on long-term capital gains depends partly on your taxable income.

That creates an opportunity.

During lower-income retirement years, you may be able to realize certain gains at a lower tax rate than you would have paid while working.

You can also coordinate gains with investment losses when appropriate.

This strategy can help you reposition a portfolio while managing the tax impact at the same time.

3. Withdraw From Multiple Accounts Strategically

Retirement withdrawals do not have to follow a rigid sequence.

You do not necessarily need to drain your brokerage account, then empty your IRA, and finally touch your Roth.

Instead, you might take some income from each account depending on the year.

For example, part of your spending could come from an IRA while the rest comes from a brokerage account. In another year, a Roth withdrawal may help prevent taxable income from moving into a higher bracket.

This approach gives you something extremely valuable in retirement: flexibility.

Different accounts create different tax consequences.

When you have several sources available, you can choose where income comes from based on your tax situation, spending needs, and long-term plan.

4. Consider Qualified Charitable Distributions

If charitable giving already plays a role in your financial life, qualified charitable distributions can become another useful tax-planning tool.

A QCD allows an eligible IRA owner to send money directly from an IRA to a qualified charity. Once RMDs begin, qualifying distributions can also count toward satisfying part or all of your required minimum distribution for the year.

That can make QCDs particularly useful for retirees who already plan to give to charity.

Rather than taking an IRA distribution, adding it to taxable income, and then making a donation separately, a properly structured QCD may provide a more tax-efficient way to accomplish the same charitable goal.

Rules and annual limits apply, so coordinate the strategy with your tax and financial professionals before making the distribution.

5. Watch the IRMAA Lookback

Medicare can add another layer to retirement tax planning.

Once you reach Medicare age, certain income decisions may affect your future premiums. A large IRA distribution, Roth conversion, or other taxable event can increase reported income. That increase may later result in higher Medicare premiums through IRMAA.

Again, this does not mean you should automatically avoid creating income. A large Roth conversion could still save substantial taxes over your lifetime even if it temporarily increases Medicare costs.

You simply want to know about the consequence before making the move.

Good planning compares both sides of the equation.

Retirement Tax Planning Is About More Than This Year’s Tax Bill

One of the biggest mistakes retirees can make is optimizing every decision for the lowest possible tax bill today.

That approach can create much larger problems later.

A year with little taxable income might feel like a win. Yet leaving a large IRA untouched could result in much larger RMDs down the road.

Likewise, intentionally paying some tax during a lower-income year can feel uncomfortable. That decision may ultimately reduce taxes over the next 20 or 30 years.

Divorce can also create new tax-planning opportunities, particularly when your income, filing status, and retirement accounts change.

That is why retirement tax planning requires a longer view. Your retirement accounts may have spent decades compounding.

Now, the way you withdraw from those accounts matters almost as much as how you accumulated them in the first place.

The Question to Ask Before You Retire

Do not stop at asking:

“Do I have enough money to retire?”

Ask another question:

“How will I actually take income from my accounts once I retire?”

You should know how your taxable accounts, traditional retirement accounts, and Roth accounts will work together.

You should also understand when Roth conversions might make sense, how RMDs could affect future taxes, and whether your income decisions may trigger higher Medicare premiums.

There is no universal withdrawal order that works for everyone. Your income, assets, tax situation, charitable goals, Social Security strategy, spending needs, and retirement date all affect the answer.

The earlier you start coordinating those pieces, the more options you may have.

If you are approaching retirement and have not mapped out where your income will come from, now is the time to start that conversation. A few decisions made before retirement begins could influence how much of your money you ultimately get to keep.

Ready to Build a Smarter Retirement Tax Planning Strategy?

The Bonfire Method brings your investments, taxes, income, and long-term goals together into one coordinated plan. If you’re approaching retirement and want to understand how each piece fits together, schedule a conversation with our team to see how the Bonfire Method can help you make more confident decisions and keep more of what you’ve built.

How Much Do I Need in Retirement? What Most Calculators Don’t Tell You

How Much Do I Need in Retirement?

If you have ever typed “how much do I need in retirement?” into a calculator, you have probably been given a fairly simple answer.

Estimate your annual spending. Multiply it by 25. Withdraw roughly 4% each year.

That can be a useful starting point. But it is not a complete retirement plan.

The 4% rule was designed to help determine how much income a portfolio may be able to support over retirement. For example, using the rule, a $1 million portfolio would initially support about $40,000 of annual withdrawals.

The problem is not necessarily the 4% rule itself. The problem is expecting one percentage to account for taxes, healthcare, Social Security, market downturns, and the way you actually withdraw money over several decades.

So if you are wondering how much do I need in retirement, the better question may be:

How much do I need, and how should my retirement income strategy be built around it?

Here are five areas that can significantly change the answer.

Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.

1. Your Retirement Accounts Are Not All Worth the Same After Taxes

Imagine two retirees each have $2 million saved.

One has nearly everything inside traditional 401(k)s and IRAs. The other has money spread across pre-tax accounts, Roth accounts, and taxable brokerage accounts.

On paper, they both have $2 million.

In practice, their retirement income could look very different.

A traditional retirement account generally creates taxable income when money is withdrawn. Roth assets may provide tax-free qualified withdrawals, while taxable brokerage accounts have their own capital gains considerations.

That is why retirement planning should include multiple tax buckets rather than simply focusing on one total savings number. There are three primary buckets: pre-tax, Roth or after-tax, and taxable accounts.

Having money available in different types of accounts can give you more flexibility when deciding where retirement income should come from each year.

So when asking how much do I need in retirement, do not only look at your account balance.

Look at where the money is located and how it may eventually be taxed.

2. Healthcare Can Change Your Retirement Number Quickly

Healthcare is one of the expenses retirement calculators can easily underestimate and one of most overlooked pieces of financial planning.

That makes healthcare worth planning for separately rather than assuming it will simply fit inside your normal retirement budget.

One potential tool is a Health Savings Account, or HSA.

For eligible individuals, an HSA can provide significant tax advantages. The strategy discussed in the episode is to contribute to the HSA, invest the balance when appropriate, and potentially pay current medical expenses from cash flow so the HSA has more time to grow for future healthcare expenses.

For someone approaching retirement with substantial assets, building a dedicated healthcare strategy can help protect the rest of the portfolio from an expense category that may continue increasing over time.

3. Social Security Can Affect How Much Your Portfolio Needs to Produce

Social Security is sometimes treated as an afterthought by high earners. It should not be.

Every dollar of dependable retirement income coming from Social Security is potentially one less dollar that has to come from your investment portfolio.

Timing matters.

The difference between claiming Social Security early and delaying benefits,  can result in a substantially larger lifetime monthly benefit.

That does not mean everyone should automatically wait until age 70.

It means Social Security should be coordinated with the rest of your retirement plan.

If you delay claiming, your portfolio may need to support more of your lifestyle during the years before Social Security begins. Later, the larger Social Security benefit could reduce the amount you need to withdraw from investments.

This is another reason the answer to how much do I need in retirement cannot always be reduced to one savings target. Your income sources matter too.

4. Your Retirement Plan Needs to Survive Bad Timing

One of the biggest risks in retirement is not simply whether the market goes down.

It is when it goes down.

Imagine retiring just before a major market decline. You are suddenly withdrawing money from a portfolio that has already fallen significantly.

That combination can be especially damaging because you are selling assets while values are depressed, leaving fewer assets available to participate in a future recovery.

This is known as sequence-of-returns risk, an important risk for retirees to manage. One potential response is creating dynamic guardrails within the retirement plan.

That could mean maintaining additional cash, positioning portions of the portfolio more conservatively, or holding assets that do not necessarily move in the same direction at the same time.

There is another side to this strategy too.

When the market performs exceptionally well, it can be tempting to permanently increase spending.

But allowing lifestyle expenses to rise every time the portfolio has a strong year can eventually put pressure on the plan.

A well-designed retirement strategy should account for both good markets and bad ones.

5. The Years After Retirement Can Create a Valuable Tax Planning Window

There can be a unique period between retirement and the beginning of required minimum distributions.

Your earned income may have dropped, but you may not yet be required to take significant distributions from traditional retirement accounts.

Those years can create an opportunity for Roth conversions.

Strategically converting portions of traditional retirement assets to Roth accounts during lower-income years, can allow you to choose when some taxes are paid instead of waiting for future required distributions.

For someone with a large traditional IRA or 401(k), this can become an important part of long-term retirement tax planning.

Rather than asking only:

How much money have I saved?

You may also want to ask:

How much control will I have over my taxable income once I retire?

So, How Much Do I Need in Retirement?

There is no single number that answers the question for everyone.

The 4% rule can provide a useful foundation, but the point is that it was never meant to function as an entire retirement plan by itself.

Your actual retirement strategy may need to account for:

  • How much you want to spend each year
  • Which accounts your money is held in
  • How withdrawals will be taxed
  • Healthcare expenses
  • Social Security timing
  • Market volatility
  • Roth conversion opportunities
  • The flexibility built into your spending plan

For someone with $2 million or more invested, those details can matter just as much as the initial withdrawal rate.

A retirement calculator can tell you whether the math looks reasonable.

A coordinated retirement plan helps determine how the money should actually work once your paycheck stops.

The Bottom Line

If you are asking how much do I need in retirement, start with your spending needs and your portfolio.

But do not stop there.

The 4% rule can help establish a baseline. Then the real planning begins.

Taxes, healthcare, Social Security, market risk, and Roth conversions all interact with one another. Coordinating those pieces can help turn a retirement savings number into a retirement income strategy designed around the life you actually want to live.

Build a Retirement Plan Around the Full Picture

Knowing how much you need in retirement is only one part of the equation. The bigger question is how your investments, taxes, income, insurance, healthcare, estate planning, and long-term goals all work together.

That is the idea behind The Bonfire Method. Instead of looking at each part of your financial life in isolation, we take a coordinated approach to help identify gaps, uncover opportunities, and build a retirement strategy around the full picture.

If you are approaching retirement and want a second set of eyes on your plan, schedule a call with Bonfire Financial. We can help you understand where you stand, what may be missing, and what steps could make your retirement strategy stronger.

What to Do When Your Financial Advisor Retires. 8 Questions to Ask Your New Advisor

New Financial Advisor? What to Ask Before You Stay

If your financial advisor is retiring, you may assume the person taking over your accounts is the natural choice to continue managing your money. That may be true, but it is worth taking the time to find out.

A new financial advisor can have a very different investment philosophy, fee structure, planning process, or approach to retirement than the advisor you have worked with for years.

That matters even more when you are approaching or already in retirement.

Before agreeing to continue the relationship, ask these eight questions to understand exactly who will be managing your money and whether they are the right fit for the years ahead.

Even if your advisor isn’t retiring now this may still be worth a read as according to J.D. Power’s 2025 Financial Advisor Satisfaction Study, 46% of financial advisors surveyed plan to retire within the next 10 years, highlighting how many investors could soon find themselves working with a new financial advisor.

Keep reading, or if you prefer to listen or watch… check out the Podcast or full YouTube video.

Why You Should Evaluate a New Financial Advisor

Advisor succession is becoming an increasingly important issue for investors. When an established advisor retires, clients may be transitioned to someone younger or to another advisor within the firm.

That transition does not necessarily mean the new advisor was selected specifically because they are the best match for you.

Financial advisory practices also have economic value. In some situations, another advisor may purchase all or part of a retiring advisor’s business. As a result, the person who takes over your accounts could have different investment strategies, services, fees, or planning philosophies.

Your retirement savings are too important to simply assume everything will remain the same.

Treat the transition as an opportunity to interview your new financial advisor and decide whether you would choose that person yourself.

1. Are You a Fiduciary at All Times?

Start with one of the most important questions you can ask a financial advisor:

Are you a fiduciary at all times?

A fiduciary is required to provide advice that is in your best interest. Understanding when and how that obligation applies can help you identify potential conflicts of interest. Some financial professionals operate under different standards depending on the account or service they are providing. That distinction may not be obvious to the client.

Ask your new financial advisor to explain their fiduciary responsibility clearly, including whether it applies to every account they manage for you.

You should understand how they are compensated as well.

Commissions, product incentives, and other forms of compensation can affect the economics of certain recommendations. Knowing how your advisor gets paid gives you additional context when evaluating their advice.

2. What Is My Total Cost in Year One?

An advisory fee is only one piece of the cost of managing an investment portfolio.

For example, an advisor may charge a percentage of the assets they manage. Additional expenses could potentially include investment costs, transaction expenses, product fees, or other charges.

Ask your new financial advisor for the total estimated cost of the relationship, not simply the headline advisory fee.

Questions may include:

  • What percentage am I paying for investment management?
  • Are there additional account or trading costs?
  • Do any of my investments carry separate fees?
  • Are commissions involved?
  • Have any fees changed since my previous advisor managed the account?

No advisor should be expected to work for free. The goal is simply to understand what you are paying and what you are receiving in return.

Fees that appear small on an annual basis can become meaningful over a long retirement.

3. Can I See an Example Financial Plan?

Investment management and financial planning are not the same thing.

A portfolio of stocks and bonds may be an important part of retirement planning, but retirees often face decisions that extend well beyond asset allocation.

Ask your new financial advisor if you can see a redacted example of a financial plan. The example can help you determine how deeply the advisor approaches retirement planning.

A comprehensive process may consider areas such as:

  • Social Security
  • Healthcare expenses
  • Tax planning
  • Roth conversions
  • Required minimum distributions
  • Withdrawal strategies
  • HSA planning
  • Estate planning
  • Investment management

Seeing the actual planning process can tell you much more than hearing someone say they provide “holistic financial planning.”

You want to know whether your advisor is building a retirement strategy or primarily managing investments.

4. How Do You Plan for the Years Between Retirement and RMDs?

The years immediately after retirement can present valuable planning opportunities.

For many retirees, there is a period between leaving the workforce and beginning required minimum distributions. Income may temporarily be lower during those years.

That window can create opportunities to evaluate strategies such as Roth conversions and other tax-planning decisions.

Ask your new financial advisor how they specifically approach those years. More importantly, find out what causes them to recommend action.

Do they have specific triggers they monitor? Will they review the opportunity every year? How do taxes factor into the decision?

A strong retirement planning process should not rely on making these decisions at the last minute.

Your advisor should have a system for evaluating opportunities as your retirement evolves.

5. How Often Will We Meet?

Communication expectations should be established before you commit to a new advisory relationship. Ask how often the advisor typically meets with retirement clients.

Some advisors schedule annual meetings. Others may meet semiannually or quarterly depending on the client’s needs and the services being provided.

The frequency itself is not necessarily the most important issue.

What matters is knowing what to expect.

Find out whether meetings are proactively scheduled by the advisor or whether clients are expected to initiate them. Ask how the advisor communicates when an issue comes up between scheduled reviews.

Retirement can involve decisions about taxes, investments, Social Security, healthcare, estate planning, and withdrawals.

You want a new financial advisor who will be available when those decisions need to be made.

6. How Did You Handle the Last Major Market Downturn?

Markets are relatively easy to discuss when they are rising.

A downturn can tell you much more about an advisor’s philosophy. Ask your prospective advisor what they told clients during the last major market decline.

Were they making significant portfolio changes? Did they encourage clients to stay disciplined? Were they attempting to predict short-term market movements?

Listen closely to the reasoning behind their decisions.

Their answer can help you determine whether their investment philosophy aligns with yours.

It may also reveal how they communicate when markets become stressful.

You are not simply evaluating performance. You are trying to understand the process behind the decisions.

7. Will You Coordinate With My Other Professionals?

Retirement planning rarely happens in isolation.

Your financial decisions may involve your CPA, estate planning attorney, insurance professionals, and other specialists.

Ask whether your new financial advisor helps coordinate those relationships.

An advisor does not need to be an expert in every area. However, someone overseeing your financial plan should understand how the different pieces work together.

For example, an estate plan may establish certain intentions for your assets. Beneficiary designations on retirement or investment accounts also need to align with those intentions.

Tax strategies can involve similar coordination.

A financial advisor who communicates with your CPA can help ensure investment and retirement decisions are considered alongside their potential tax consequences.

Think of your advisor as the quarterback of your financial life rather than simply another player on the field.

8. What Is My Exit Strategy?

It may seem strange to discuss leaving a financial advisor before you have even decided to work with them.

That is exactly why you should ask.

Find out what happens if you decide six months, two years, or even ten years from now that the relationship is no longer right for you.

  • Can your investments transfer easily?
  • Are there surrender charges?
  • Do any products have holding periods or penalties?

Certain financial products, including some annuities, can include surrender schedules that make exiting expensive for a period of time.

Understanding those restrictions before investing is considerably easier than discovering them after you decide you want to leave.

A good relationship should begin with a clear understanding of how it can end.

Don’t Automatically Stay With a New Financial Advisor

A longtime advisor retiring can feel disruptive, especially when that person has guided your finances for years. Still, the transition gives you an opportunity.

Instead of automatically remaining with whoever takes over the practice, evaluate the new financial advisor the same way you would evaluate someone you were hiring from scratch.

Ask about fiduciary responsibility, fees, retirement planning, tax strategy, communication, investment philosophy, professional coordination, and your ability to leave.

These conversations do not need to take hours. In roughly 30 minutes, you can learn a great deal about how an advisor operates and whether their approach fits what you want for your retirement.

The decision matters because small differences in fees, taxes, investment decisions, and retirement planning can compound over many years.

Your financial advisor may have retired, your responsibility for choosing who manages the next stage of your financial life has not.

Considering a New Financial Advisor?

If your financial advisor has retired, your accounts have been transferred to someone new, or you are questioning whether your current advisor is still the right fit, a second opinion can help.

At Bonfire Financial, we look beyond investment allocation to understand how your investments, retirement income, taxes, Social Security, estate planning, and long-term goals work together.

Before signing anything with a new financial advisor, take the time to understand your options.

Schedule a conversation with us to get a second set of eyes on your retirement plan.

Thank You For Your Subscription

You’re in! Thanks for subscribing to our monthly newsletter. We will be sending you market updates, financial insights and inspiring travel ideas soon but in the meantime check out our blog, join us on Instagram or pop over to Pinterest.

Your Appointment Request has been Received

Thank you for reaching out! We are excited to learn more about you. Someone from our team will be in touch shortly.

Sign up now

Join us around the fire for monthly market updates, financial insights and inspiring travel ideas.

.

Sign up now

Receive tips

Give us a call

(719) 394.3900
(844) 295.0069